

Actuarial Report (19th) on the Old Age Security Program as at 31 December 2024
25 June 2026
The Honourable Patty Hajdu, P.C., M.P.
Minister of Jobs and Families
House of Commons
Ottawa, Canada
K1A 0A6
Dear Minister:
In accordance with section 3 of the Public Pensions Reporting Act, I am pleased to submit the Actuarial Report prepared as at 31 December 2024 on the pension plan established under the Old Age Security Act.
Yours sincerely,
Assia Billig, FCIA, FSA, PhD
Chief Actuary
Table of contents
- 1 Highlights of the report
- 2 Introduction
- 3 Methodology
- 4 Best-estimate assumptions
- 5 Results
- 6 Reconciliation with previous triennial report
- 7 Actuarial opinion
- Appendix A — Summary of program provisions
- Appendix B — Data, assumptions and methodology
- Appendix C — Detailed reconciliations with previous triennial report
- Appendix D — Uncertainty of results
- Appendix E — Detailed projections of beneficiaries and expenditures
List of tables
- Table 1 Best-estimate assumptions of 19th report compared with 18th report
- Table 2 Best-estimate assumptions for benefit recipient rates of 19th report compared with 18th report
- Table 3 Population of Canada
- Table 4 Economic assumptions
- Table 5 Recipient rates
- Table 6 Beneficiaries
- Table 7 Beneficiaries
- Table 8 Expenditures and average annual benefits
- Table 9 Expenditures and average annual benefits
- Table 10 Expenditures as percentage of GDP
- Table 11 Expenditures as percentage of GDP
- Table 12 Financial results - Totals for 2022 to 2024
- Table 13 Reconciliation of expenditures as a percentage of GDP
- Table 14 Reconciliation of expenditures in billions
- Table 15 Cohort fertility rates by age and year of birth
- Table 16 Annual fertility rates by age group (per 1,000 women)
- Table 17 Annual mortality improvement rates for Canada
- Table 18 Mortality rates for Canada
- Table 19 Life expectancies for Canada, without improvements after the year shown
- Table 20 Life expectancies for Canada, with improvements after the year shown
- Table 21 Population of Canada by age
- Table 22 Analysis of population of Canada by age group
- Table 23 Births, net migrants, and deaths for Canada
- Table 24 Active population (Canada, ages 15 and over)
- Table 25 Labour force participation, employment, and unemployment rates Canada, ages 15 and over
- Table 26 Labour force participation rates (Canada)
- Table 27 Employment of male population (Canada, ages 18 to 69)
- Table 28 Employment of female population (Canada, ages 18 to 69)
- Table 29 Real wage increase and related components
- Table 30 Assumed deferral rates for cohorts reaching age 65 in 2024 and thereafter
- Table 31 Male OAS basic pension recipient rates by age and level of benefit
- Table 32 Female OAS basic pension recipient rates by age, and level of benefit
- Table 33 OAS beneficiaries affected by the OAS recovery tax
- Table 34 Financial impact of OAS recovery tax
- Table 35 Male GIS recipient rates for cohorts reaching age 65 in 2025, 2030, and 2060, by age and level of benefit
- Table 36 Female GIS recipient rates for cohorts reaching age 65 in 2025, 2030, and 2060, by age and level of benefit
- Table 37 Male Allowance recipient rates for cohorts reaching age 60 in 2025, 2030, and 2060, by age and level of benefit
- Table 38 Female Allowance recipient rates for cohorts reaching age 60 in 2025, 2030, and 2060, by age and level of benefit
- Table 39 Projected maximum monthly benefits
- Table 40 Average benefits for males as percentage of maximum rates in years 2025 and 2060, by benefit type and level
- Table 41 Average benefits for females as percentage of maximum rates in years 2025 and 2060, by benefit type and level
- Table 42 Detailed reconciliation of expenditures and GDP in billions, and cost ratio (% of GDP) (OAS, GIS and Allowance combined)
- Table 43 Individual sensitivity test assumptions
- Table 44 Sensitivity of cost ratio (expenditures as a percentage of GDP)
- Table 45 Higher and lower economic growth sensitivity tests
- Table 46 OAS basic benefit beneficiaries
- Table 47 OAS basic benefit expenditures
- Table 48 GIS beneficiaries (total)
- Table 49 GIS expenditures (total)
- Table 50 GIS beneficiaries (single)
- Table 51 GIS expenditures (single)
- Table 52 GIS beneficiaries (spouse a pensioner)
- Table 53 GIS expenditures (spouse a pensioner)
- Table 54 GIS beneficiaries (spouse not a pensioner)
- Table 55 GIS expenditures (spouse not a pensioner)
- Table 56 GIS beneficiaries (spouse with allowance)
- Table 57 GIS expenditures (spouse with allowance)
- Table 58 Allowance beneficiaries (total)
- Table 59 Allowance expenditures (total)
- Table 60 Allowance beneficiaries (regular)
- Table 61 Allowance expenditures (regular)
- Table 62 Allowance beneficiaries (survivor)
- Table 63 Allowance expenditures (survivor)
List of charts
- Chart 1 Expenditures as a proportion of GDP
- Chart 2 Historical and projected total and cohort fertility rates for Canada
- Chart 3 Life expectancies at age 65 for Canada, without improvements after the year shown
- Chart 4 Net migration rate (Canada)
- Chart 5 Age distribution of the Canadian population
- Chart 6 Population of Canada
1 Highlights of the report
Main findings 19th OAS Program Actuarial Report
Overall OAS program
- As a result of baby boomers gradually reaching age 65, the number of beneficiaries and expenditures are projected to steadily increase over the next decades.
- Expenditures are projected to increase from an estimated $92.6 billion in 2026 to $137.2 billion in 2035 and $277.7 billion by 2060.
- The cost ratio, which is represented as the ratio of OAS program expenditures to the Gross Domestic Product (GDP) is estimated to be 2.76% in 2026.
- Due to the population aging, the cost ratio is projected to reach a high of around 2.9% by the early 2030s. Afterward, this ratio is projected to gradually decrease to a level of 2.63% by 2060, mainly due to expected slower growth in inflation compared to the growth in GDP.
| OAS basic pension | Guaranteed income supplement (GIS) and allowance | |
|---|---|---|
| Beneficiaries | The number of beneficiaries of the basic pension is projected to increase at a higher pace from 2026 to 2035, growing from 7.9 million in 2026 to 9.7 million by 2035, and then reaches 12.4 million by 2060. | The number of GIS and Allowance beneficiaries is projected to increase at a higher pace from 2026 to 2035, growing from 2.7 million in 2026 to 3.4 million by 2035, and then reaches 3.6 million by 2060. |
| Expenditures | Basic pension annual expenditures are projected to increase from $70.7 billion in 2026 to $105.8 billion in 2035 and $223.4 billion by 2060. | GIS and Allowance annual expenditures are projected to increase from $21.3 billion in 2026 to $30.7 billion in 2035 and $52.9 billion by 2060. |
Uncertainty - 19th OAS Program Actuarial Report
Mortality assumption
The 19th OAS Program Actuarial Report is based on the assumption that mortality will continue to improve but at a slower pace than over the last few decades.
If longevity improves faster than assumed (projected life expectancies at age 65 in 2060 that are about 3.1 years higher), the cost ratio of expenditures to GDP in 2060 increases from 2.63% to 2.80%.
Economic growth
The 19th OAS Program Actuarial Report is based on the assumption of moderate and sustained economic growth.
If lower economic growth is assumed with total employment earnings in 2035 being 11% lower, this would result in:
- the cost ratio in 2060 increasing from 2.63% to 3.48%.
If higher economic growth is assumed with total employment earnings in 2035 being 16% higher, this would result in:
- the cost ratio in 2060 decreasing from 2.63% to 1.93%.
Scenario analysis - 19th OAS Program Actuarial Report
The 19th OAS Program Actuarial Report includes a section that uses scenario analysis to assess and illustrate relevant risks. The scenario presented is not meant to represent forecasts or predictions and should be interpreted with caution.
Acute economic event
The 19th OAS Program Actuarial Report is based on the assumption of sustained moderate economic growth.
A scenario was developed to illustrate the impact of an acute, relatively short-term economic event that unfolds over a period of 4 years starting in 2026. This scenario results in higher inflation and unemployment and lower growth in real wages. This hypothetical acute economic event scenario would result in:
- the cost ratio of expenditures to GDP in 2060 increasing from 2.63% to 2.88%.
2 Introduction
2.1 Purpose of the report
This is the 19th Actuarial Report on the Old Age Security (OAS) program since the implementation of the Old Age Security Act in 1952. The valuation date is 31 December 2024. This report has been prepared in compliance with the timing and information requirements of the Public Pensions Reporting Act, which provides that the Chief Actuary shall prepare a triennial actuarial report on the benefits under the various Parts of the Old Age Security Act, being as follows:
- Part I: OAS Basic Pension
- Part II: Guaranteed Income Supplement (GIS)
- Part III: Allowance
Another important purpose of the report is to inform the general public of the current and projected costs of the OAS program. The report provides information to evaluate the program's financial situation over a long period (until 2060), provided the program remains unchanged. Such information facilitates a better understanding of the program and the factors that influence its costs.
The previous triennial actuarial report was the 18th Actuarial Report on the Old Age Security Program as at 31 December 2021, which was tabled in the House of Commons on 3 November 2023. The next triennial report is scheduled as at 31 December 2027.
This 19th OAS Program Actuarial Report takes into account all amendments to date regarding the OAS program statute, with the most recent changes listed in the following section. It also takes into account recent demographic and economic experience data as described in section B.2 of Appendix B. Additionally, the report is based on the Chief Actuary's best-estimate assumptions, which consider various forecasts from experts in these areas.
This report presents projections of OAS program expenditures until the year 2060. Given the length of the projection period and the number of assumptions required, it is unlikely that actual future experience will develop precisely in accordance with the best-estimate projections.
This 19th OAS Program Actuarial Report is intended solely for the above purposes. It was prepared to meet those specific objectives and may not be suitable for any other purposes prior to obtaining approval from the Office of the Chief Actuary (OCA).
For any questions regarding the proper use of this report, please contact the OCA.
2.2 Recent amendments
The Old Age Security Act was subject to an amendment after 31 December 2021 as follows:
- Under An Act to amend the Old Age Security Act (Guaranteed Income Supplement), which received Royal Assent on 3 March 2022, payments of the Canada Emergency Response Benefit and other COVID-19 pandemic-related assistance payments are excluded from a person's income for the purpose of determining GIS and Allowance benefits for any month after June 2022.
There was no supplementary actuarial report prepared regarding the above amendment as the effect on expenditures of the OAS program was deemed to be negligible. This amendment is taken into account for this 19th OAS Program Actuarial Report.
2.3 Subsequent events
For this 19th OAS Program Actuarial Report, there were no subsequent events, i.e. events which became known to the Chief Actuary after the valuation date, but before the report date, and that were deemed to have an effect on the expenditures of the OAS program as at the valuation date or during the projection period.
The Canadian and global economies are going through a period of heightened uncertainty, due in part to escalating trade tensions, environmental risks, and geopolitical conflicts. The future impacts of these issues and risks on expenditures of the OAS program are still uncertain and evolving, and as such, they have not been recognized as subsequent events for the purpose of this report.
2.4 Scope of the report
Section 3 presents a general overview of the methodology used in preparing the actuarial estimates included in this report, which are based on the best-estimate assumptions described in section 4. The results are presented in section 5 and include the projections of beneficiaries, expenditures, and cost ratios. Section 6 provides the reconciliation of the results with those of the 18th OAS Program Actuarial Report, and section 7 provides the actuarial opinion.
The various appendices provide a summary of the OAS program provisions, a description of the data, assumptions and methodology employed, detailed reconciliations of the results with the previous triennial report, the uncertainty of results, and detailed projections of beneficiaries and expenditures.
3 Methodology
The actuarial examination of the OAS program involves projections of its expenditures and cost measurement base (the Gross Domestic Product (GDP)) over a long period of time so that the future impacts of historical and projected trends in demographic and economic factors can be properly assessed. The actuarial estimates in this report are based on the provisions of the Old Age Security Act as at 31 December 2024, historical experience data used for the starting point of the projections, and best‑estimate assumptions regarding future demographic and economic experience.
Since the OAS program is financed from general tax revenues on a pay‑as‑you‑go basis, there is no need to project either contributions or investment earnings. However, projected GDP is used as a basis for measuring the relative costs over the projection period.
The costing begins with a projection of the general population of Canada. This requires assumptions regarding demographic factors such as fertility, migration, and mortality.
Expenditures consist of the benefits paid out and administrative expenses. Benefits are projected by applying assumptions regarding recipient rates for various types and levels of benefits to the projected population at the relevant ages, along with assumptions regarding increases in the maximum benefit rates. Administrative expenses are projected by considering the historical relationship between expenses and total benefit expenditures.
The GDP is projected using underlying assumptions of productivity, hours worked, and employment growth as determined in the Revised 32nd Actuarial Report on the Canada Pension Plan as at 31 December 2024, which was tabled in the House of Commons on 27 May 2026 (the Revised 32nd CPP Actuarial Report). By applying these expected increases to the last known GDP value in 2025, a projection of the GDP has been derived.
The assumptions and results presented in the following sections make it possible to measure the costs of the OAS program over the projection period. A wide variety of factors influence both the current and projected costs of the program. Accordingly, the results shown in this report differ from those shown in previous reports. Likewise, future actuarial examinations will likely reveal results that differ from the projections included in this report.
4 Best-estimate assumptions
4.1 Introduction
The information required by statute, which is presented in section 5 of this report, necessitates making numerous assumptions regarding future demographic and economic trends. The projections included in this report cover a long period of time (up to the year 2060).
The assumptions are determined by examining historical short- to long-term trends and applying judgement as to the extent these trends will continue in the future. These assumptions, which do not include any margins for adverse deviations, reflect the Chief Actuary's best judgment and are referred to in this report as the best-estimate assumptions. The use of best-estimate assumptions is considered to be the most appropriate choice for projecting the costs of the OAS program over the long term. The assumptions were selected to be independently reasonable and appropriate in the aggregate, taking into account certain interrelationships between them. To the extent applicable, the assumptions are consistent with the best-estimate assumptions used in the Revised 32nd CPP Actuarial Report.
For this 19th OAS Program Actuarial Report, there were no subsequent events, i.e. events which became known to the Chief Actuary after the valuation date, but before the report date, and that were deemed to have an effect on the expenditures of the OAS program as at the valuation date or during the projection period.
Table 1 and Table 2 present a summary of the most important assumptions used in this report compared with those used in the previous triennial report. The assumptions are described in more detail in Appendix B of this report.
| Assumptions | 19th report (as at 31 December 2024) | 18th report (as at 31 December 2021) |
|---|---|---|
| Total fertility rate | 1.35 (2033+) | 1.54 (2029+) |
| Mortality | Statistics Canada Life Table (CLT 1-year table: 2019) with assumed future improvementsTable 1 Footnote 1,Table 1 Footnote 2 | Statistics Canada Life Table (CLT 1-year table: 2019) with assumed future improvementsTable 1 Footnote 2 |
| Canadian life expectancy for male at birth in 2025Table 1 Footnote 3 | 87.8 years | 86.9 years |
| Canadian life expectancy for female at birth in 2025Table 1 Footnote 3 | 91.0 years | 90.2 years |
| Canadian life expectancy for male at age 65 in 2025Table 1 Footnote 3 | 21.6 years | 21.5 years |
| Canadian life expectancy for female at age 65 in 2025Table 1 Footnote 3 | 24.1 years | 24.0 years |
| Net migration rate (including changes in non-permanent residents) | 0.72% of population (for 2051+) | 0.64% of population (for 2031+) |
| Non-permanent residents level | 2.5% of population (for 2050+)Table 1 Footnote 4 | N/ATable 1 Footnote 5 |
| Participation rate (age group 18-69) | 80.0% (2035) | 80.0% (2035) |
| Employment rate (age group 18-69) | 75.3% (2035) | 75.3% (2035) |
| Unemployment rate (age group 18-69) | 5.9% (2028+) | 5.9% (2027+) |
| Rate of increase in prices | 2.0% (2027+) | 2.0% (2026+) |
| Real wage increase | 0.8% (2025+) | 0.9% (2026+) |
Table 1 Footnotes
| ||
| Benefits | 19th report (as at 31 December 2024) | 18th report (as at 31 December 2021) | ||||
|---|---|---|---|---|---|---|
| 2025 | 2030 | 2060 | 2025 | 2030 | 2060 | |
| OAS: | 94.2% | 94.6% | 95.2% | 95.1% | 95.2% | 95.5% |
| GIS: | 31.8% | 32.5% | 26.9% | 31.9% | 32.5% | 26.8% |
| Allowance: | 2.6% | 3.0% | 2.2% | 2.8% | 3.2% | 2.3% |
Table 2 Footnotes
| ||||||
4.2 Demographic assumptions
The population projection starts with the population of Canada on 1 July 2024, to which are applied fertility, migration, and mortality assumptions. The population projection is essential in determining the future number of OAS program beneficiaries.
The age distribution of the population has changed significantly over time. The proportion of the Canadian population aged 65 and above has increased from 7.6% in 1966 to 12.1% in 1996, and reached 18.9% in 2024, which indicates an aging population. It is assumed that this shift in the age distribution will continue in the future, although at a more moderate pace.
4.2.1 Fertility
One of the causes of the aging of the Canadian population is the decline in the total fertility rate that has occurred since the late 1950s. The total fertility rate in Canada decreased rapidly from a level of about 4.0 children per woman in the late 1950s to 1.6 by the mid-1980s. The total fertility rate then hovered between 1.5 and 1.7 until 2008. Similar to the experience in other industrialized countries, Canada's total fertility rate has decreased since 2008, with steeper decreases since 2020. Canada, once in the middle of the pack amongst industrialized countries, is now positioned with Italy and Japan as one of the countries with lower fertility rates. The total fertility rate for Canada stood at 1.41 in 2020 and decreased further to 1.26 in 2023.
The rapid decrease in the total fertility rate between the late 1950s and mid-1980s occurred as a result of changes in a variety of social, medical, economic, and environmental-related factors. It is unlikely that the rate will return to historical levels in the absence of significant societal changes. Decreases in the fertility rate since 2008 could be largely attributable to the 2008 economic downturn and continuing economic uncertainty. The housing crisis, the increase in the number of non-permanent residents, which tend to have lower fertility, as well as increased anxiety and mental health issues can also help explain the steep decreases in recent years.
To project the fertility rates in Canada for most age groups, a 20-year period of data ending in 2023 was used to establish a trending model that provides the best fit using historical patterns and anticipated future movements. Some adjustments were made for age groups 25-29 and 30-34. Fertility rates for certain age groups were also adjusted upwards to account for expected effects from the Canada-Wide Early Learning and Child Care Plan (CWELCC).
The assumed age-specific fertility rates lead to an assumed total fertility rate for Canada that will increase from its 2023 level of 1.26 children per woman to an ultimate level of 1.35 in 2033. It is assumed that the increase from 2023 levels will result from the positive impact of the CWELCC, as well as a renewed rise in fertility rates among the 30-39 age group, driven by the delayed childbearing decisions.
4.2.2 Mortality
Another element that has contributed to the aging of the population is the significant reduction in the age-specific mortality rates, especially at older ages. This can be measured by the increase in life expectancy at age 65, which directly affects how long retirement benefits will be paid to beneficiaries. Calendar year male life expectancy (without future mortality improvements at age 65 increased by 43% between 1966 and 2023, rising from 13.6 to 19.5 years. For women, it increased by 31%, from 16.9 to 22.2 years over the same period. Although the overall gains in life expectancy at age 65 since 1966 are similar for males and females, 67% of the increase occurred after 1991 for males, while for females, 47% of the increase occurred during that period.
Although Statistics Canada life tables were available up to 2023 at the time of the analysis, data for calendar years 2020 to 2023 were excluded for purposes of setting long-term mortality rates. Mortality tables for these years reflect significant mortality increases related to COVID-19 and opioid-related deaths, which are assumed to be temporary. Long-term future mortality rates are therefore determined by applying assumed mortality improvement rates to Statistics Canada's 2019 life tables. The projected mortality improvement rates are assumed to gradually reduce from their 15-year average ending in 2019 to ultimate levels in 2039, which are for both sexes 1.0% per year for ages below 90, 0.6% per year for ages 90 to 94, and 0.2% per year for ages 95 and above.
The assumed ultimate mortality improvement rates are based on an analysis of the Canadian experience over the period 1954 to 2019 and the possible drivers of future mortality improvements. Consideration was also given to benchmarks from peers as well as educational notes and research published by the Canadian Institute of Actuaries, including the most recent Mortality Improvements Research paper published in April 2024.
Short-term adjustments are then applied to projected mortality rates to match historical data available (2020 to 2023) and to reflect the temporary continuing impacts of the COVID-19 pandemic and opioid crisis. The COVID-19 pandemic is assumed to have a residual effect on mortality in 2024 and 2025, followed by an assumed full recovery and reversion to the projected unadjusted mortality rates for year 2026 and onward. The short-term adjustments also reflect the expectation that the opioid crisis will be temporary, and that mortality for affected age groups will revert to unadjusted mortality rates by 2039.
Considering the above, cohort life expectancy (with assumed future mortality improvements) at age 65 in 2025 is projected to be 21.6 years for males, and 24.1 years for females.
4.2.3 Net migration
Net migration corresponds to the number of immigrants less the net number of emigrants (i.e. the number of emigrants less the number of returning Canadians) plus the net increase in the number of non-permanent residents (NPR).
To select the assumptions regarding the short-term and ultimate rates, the components of net migration were analyzed separately by considering trends in the historical data as well as qualitative factors that could influence future trends. Consideration was also given to the federal government's short-term immigration targets and to long-term perspectives of various experts regarding levels of future immigration and NPR. For this valuation, a new methodology was developed to estimate the annual levels of NPR as a proportion of the population, from which the net increase in NPR is then derived.
In line with the government's short-term immigration targets, the immigration rate is expected to decrease from 1.12% of the population in 2024 to 0.96% in 2025, 0.92% in 2026, and 0.88% in 2027. After that, it is projected to gradually decrease to an ultimate rate of 0.82% by 2034. The ultimate rate of 0.82% corresponds to the 20-year average ending in 2024, which was selected to give some weight to generally higher levels of immigration observed since 2016 while still reflecting longer term historical trends.
The historical net emigration rate has been relatively stable. The net emigration rate is expected to decrease slightly from 0.12% of the population in 2024 to 0.11% by 2026 and remain at that level thereafter.
In recent years, there has been a significant increase in the number of NPR. By the end of 2024, the number of NPR reached an unprecedented level, representing 7.3% of the population. By contrast, based on the 20-year average ending in 2024, NPR represented 2.7% of the population. In addition, for the first time ever, the government announced short-term targets for NPR, which is set at 5% of the population by the end of 2026.
To address the higher levels and volatility of the number of NPR in recent years, a new method was developed for this report to project the number of NPR separately from the rest of the population. For this purpose, an assumption is made for each year of the projection period regarding the level of NPR as a percentage of the population. The resulting annual changes in NPR can then be determined and flow through the overall net migration rate.
Based on the new NPR method, the number of NPR as a percentage of the population is expected to decrease from 7.3% of the population in 2024 to 5% of the population by 2026 as per the government's short-term targets. It is further assumed that this proportion will decrease to 4% by 2035 and to an ultimate rate of 2.5% by 2050. The ultimate rate of 2.5% was selected to give some weight to recent higher levels of NPR, while still reflecting longer-term historical trends.
As a result of the above, the net migration rate for Canada, including net changes in the level of NPR, is projected to decrease from its 2024 level of 2.88% of the populationFootnote 1 to −0.34% in 2025 and -0.29% in 2026, and is then assumed to increase to 0.82% in 2027. Thereafter, the net migration rate is assumed to gradually transition to an ultimate level of 0.72% of the population is 2051.
4.2.4 Population projections
Table 3 shows the population of Canada for three age groups (0-19, 20-64 and 65 and over) throughout the projection period. The ratio of the number of people aged 20-64 to those aged 65 and over is a measure that approximates the ratio of the number of working-age people to retirees. Because of the aging population, this ratio is projected to drop from 3.0 in 2025 to 2.1 by 2060.
The number of people reaching age 65 in any given year is a good indicator of the number of new basic pension beneficiaries coming into pay each year, which is expected to increase from 526,000 in 2025 to 627,000 by 2060.
| Year | Total | Age 0-19 | Age 20-64 | Age 65 and over | Ratio of 20-64 to 65 and over | Reaching age 65 |
|---|---|---|---|---|---|---|
| 2025 | 41,206 | 8,552 | 24,571 | 8,083 | 3.0 | 526 |
| 2026 | 41,143 | 8,526 | 24,255 | 8,362 | 2.9 | 533 |
| 2027 | 41,534 | 8,554 | 24,351 | 8,629 | 2.8 | 528 |
| 2028 | 41,863 | 8,563 | 24,400 | 8,900 | 2.7 | 540 |
| 2029 | 42,188 | 8,568 | 24,464 | 9,157 | 2.7 | 535 |
| 2030 | 42,500 | 8,571 | 24,538 | 9,392 | 2.6 | 522 |
| 2031 | 42,803 | 8,576 | 24,641 | 9,586 | 2.6 | 490 |
| 2035 | 43,914 | 8,564 | 25,166 | 10,184 | 2.5 | 475 |
| 2040 | 45,183 | 8,599 | 25,876 | 10,708 | 2.4 | 471 |
| 2045 | 46,313 | 8,762 | 26,423 | 11,128 | 2.4 | 509 |
| 2050 | 47,319 | 8,871 | 26,823 | 11,625 | 2.3 | 552 |
| 2055 | 48,504 | 8,993 | 27,286 | 12,225 | 2.2 | 613 |
| 2060 | 49,711 | 9,115 | 27,590 | 13,006 | 2.1 | 627 |
Table 3 Footnotes
| ||||||
4.3 Economic assumptions
The OAS program expenditures are presented as cost ratios using the GDP as a measurement base. This cost base is projected using economic assumptions regarding labour force participation rates, job creation rates, unemployment rates, and nominal increases in average employment earnings. For benefit projection purposes, assumptions regarding the rate of increase in prices and recipient rates for the various benefits are also required.
All economic assumptions are consistent with the Revised 32nd CPP Actuarial Report, which are based on the overall expectation of sustained moderate economic growth.
A key element underlying the best-estimate economic assumptions relates to the continued trend toward longer working lives. Older workers are expected to exit the workforce at a later age, which could alleviate the impact of the aging of the population on future labour force growth. However, despite the expected later exit ages, labour force growth is projected to weaken as the working-age population expands at a slower pace and baby boomers continue to exit the labour force.
4.3.1 Labour force
Employment levels vary with the rate of unemployment and reflect trends in increased workforce participation by women, longer periods of formal education among young adults, changes in the age structure of the working-age population, as well as changing retirement patterns of older workers.
As the population ages, older age groups with lower labour force participation increase in size. As a result, the labour force participation rate for Canadians aged 15 and over is expected to decline from an estimated value of 65.2% in 2025 to 64.4% in 2035. A more useful measure of the working-age population is the participation rate of those aged 18 to 69, which is expected to increase from an estimated 77.3% in 2025 to 80.0% in 2035. The increase in the participation rate for those aged 18 to 69 reflects several trends.
For example, it is assumed that female participation rates will continue to grow at a faster pace than male participation rates until 2035, thereby continuing to reduce the gap in participation rates between males and females, albeit at a slower pace than in the past. A part of this projected reduction can be attributed to the continuing impact of the Canada-Wide Early Learning and Child Care plan on female labour force participation.
It is also assumed that participation rates for age groups 55 and over for both sexes will increase as a result of an expected continued trend toward longer working lives.
It is expected that the projected aging of the population will create upward pressure on future participation rates as a larger proportion of the population no longer in the workforce will require services from a relatively smaller working-aged population. The participation rates for all age groups are thus expected to increase in response to this demographic shift.
Overall, the male participation rate of those aged 18 to 69 is expected to be 81.0% in 2025 and to increase to 83.1% by 2035, while the female participation rate for the same age group is expected to be 73.5% in 2025 and to increase to 76.9% by 2035. As such, the difference between male and female participation rates for the age group 18 to 69 is projected to be 7.5% in 2025 and decrease to 6.2% by 2035. Thereafter, the gap between participation rates for males and females, age group 18 to 69, is projected to vary between 6.1 and 6.2 percentage points.
The job creation rate, measured by the annual change in employment, was on average 1.6% from 1976 to 2024. Future job creation rates will depend on changes in the unemployment rates and the rate of labour force growth.
The unemployment rate (ages 15+) is projected to rise from 6.3% in 2024 to 7.0% in 2025, and then gradually decline to 6.1% by 2028.
In 2025 and 2026, the labour force is expected to contract mainly due to a decline in the NPR population. This will contribute to negative job creation during those years. Stronger job creation rates are expected in 2027 and 2028 at rates of 1.2% and 1.0%, respectively, as labour force growth resumes and unemployment falls. Starting in 2029, job creation rates are assumed to align with labour force growth, averaging 0.8% annually until 2035 and 0.4% thereafter. The aging population is the primary factor behind this slower long-term growth.
4.3.2 Price increases
On December 13, 2021, the Bank of Canada and the federal Government renewed their commitment to keep inflation between 1% and 3% with a target at the mid-point of 2% until the end of 2026. They further noted that the Bank of Canada will use the flexibility of the 1% to 3% range to actively seek the maximum sustainable level of employment to an extent that is consistent with keeping medium-term inflation expectations at 2%.
Despite the mid-point target of 2%, price increases (inflation), as measured by changes in the Consumer Price Index (CPI), will fluctuate from year to year. For instance, global imbalances in supply and demand during the COVID-19 outbreak, pent-up demand following the lifting of restrictions in 2021 and 2022, as well as the war in Ukraine that commenced in February 2022, contributed to upward pressure on prices, resulting in inflation peaking at 8.1% in June 2022. As the pandemic became more manageable, fiscal stimulus wound down. This, combined with demand and supply returning to equilibrium, allowed the inflation rate to gradually align with the Bank's 2% target, which it hit in August 2024. On an annual basis, the average inflation rate in 2024 was 2.4%. In 2025, the inflation rate had largely stabilized near the Bank's target. Although energy prices increased in early 2026 due to the conflict in the Middle East, inflation remained within the Bank of Canada's 1–3 per cent target range.
In this report, the inflation rate in Canada is assumed to be 2.2% in 2025, decreasing to 2.1% in 2026 and returning to the 2.0% target for 2027 and thereafter. These assumed price increases are based on short-term forecasts from various economists as well as the expectation that the Bank of Canada and federal Government will continue to renew the inflation target of 2.0%, and that the Bank of Canada will be successful in keeping inflation at its mid-point target in the long term.
4.3.3 Gross Domestic Product
The long-term GDP is projected using underlying assumptions of productivity, hours worked, and employment growth as determined in the Revised 32nd CPP Actuarial Report. The short-term GDP projection is informed by the 2025 Canadian federal budget. The resulting real GDP growth assumption is shown in Table 4.
4.3.4 Real wage increases
Wage increases affect the financial balance of the OAS program in two ways. In the short term, an increase in the average wage translates into higher GDP, with little immediate impact on benefits. Therefore, costs in relation to this measurement will decrease. Over the longer term, higher average wages in relation to the level of prices could be expected to produce lower payouts for income-tested benefits such as the GIS and Allowance. The difference between nominal wage increases and inflation represents increases in the real wage, which is also referred to in this report as the real wage increase.
Two wage measures are used in this report: the average annual earnings (AAE) and the average weekly earnings (AWE). The assumed increase in AAE is used to project the income of future beneficiaries, while the assumed increase in the AWE is used to project the increase in the Year's Maximum Pensionable Earnings (YMPE) from one year to the next. The two measures are assumed to grow at the same pace over the projection period.
Real AAE and real AWE are projected to increase by 0.8% in 2025 and for every year thereafter. This assumption is developed taking into account historical trends and future views on labour productivity, average hours worked and other contributing factors. The ultimate real AAE and real AWE increase assumption combined with the ultimate price increase assumption results in an assumed increase in nominal AAE and nominal AWE of 2.8% in 2027 and thereafter.
Table 4 summarizes the main economic assumptions over the projection period.
| Year | Real increase GDP | Real increase average weekly/annual earnings | Price increase | Labour force (Canada, 15+) | |||
|---|---|---|---|---|---|---|---|
| Participation rate | Job creation rate | Unemployment rate | Labour force annual increase | ||||
| 2025 | 2.3 | 0.8 | 2.2 | 65.2 | (0.7) | 7.0 | 0.0 |
| 2026 | 1.2 | 0.8 | 2.1 | 64.8 | (0.4) | 6.7 | (0.7) |
| 2027 | 2.0 | 0.8 | 2.0 | 64.7 | 1.2 | 6.4 | 0.9 |
| 2028 | 1.9 | 0.8 | 2.0 | 64.6 | 1.0 | 6.1 | 0.7 |
| 2029 | 2.0 | 0.8 | 2.0 | 64.5 | 0.7 | 6.1 | 0.7 |
| 2030 | 1.6 | 0.8 | 2.0 | 64.4 | 0.7 | 6.1 | 0.7 |
| 2035 | 1.6 | 0.8 | 2.0 | 64.4 | 0.7 | 6.1 | 0.7 |
| 2040 | 1.3 | 0.8 | 2.0 | 64.0 | 0.4 | 6.1 | 0.4 |
| 2045 | 1.3 | 0.8 | 2.0 | 63.7 | 0.4 | 6.1 | 0.4 |
| 2050 | 1.2 | 0.8 | 2.0 | 63.2 | 0.2 | 6.1 | 0.2 |
| 2055 | 1.2 | 0.8 | 2.0 | 62.7 | 0.3 | 6.1 | 0.3 |
| 2060 | 1.2 | 0.8 | 2.0 | 62.1 | 0.3 | 6.1 | 0.3 |
4.3.5 Recipient rates
OAS recipient rates represent the proportion of the Canadian population that has received (historically), receives, or is projected to receive OAS program benefits. Recipient rates are different than coverage or eligibility rates for benefits, which are higher, since individuals upon becoming eligible for benefits don't necessarily apply for them immediately, but may rather defer application and commencement of their benefits (for reasons such as to receive increased benefits for voluntary deferrals or to increase benefits from partial to full amounts by accruing more years of residence).
Recipient rates for the OAS basic pension presented in this report exclude the impact of the OAS Recovery Tax. The impact of the OAS Recovery Tax on the basic pension recipient rates is discussed in section 5 of Appendix B of this report.
Similar to the previous OAS report, the predominant trend observed for this current report remains an increase in the number of beneficiaries deferring commencement of their OAS basic pension. As shown in Table 5, the overall basic pension recipient rates for males and females are projected to slightly increase from 93.5% in 2025 to 94.7% in 2060 for males and from 94.9% to 95.6% for females over the same period. The rates for both sexes increase over time primarily due to the aging of the population.
Historical OAS recipient rates by age and sex over the 10 years ending in 2024 were used as the starting point for determining the corresponding best-estimate assumptions.
GIS and Allowance recipient rates by age, sex, type and level of benefit for year 2024 were used as the starting point for determining the corresponding best-estimate assumptions.
GIS and Allowance recipient rates are projected under the assumption that initial retirement income increases in line with the rate of wage growth, where such retirement income mainly comprises CPP and Quebec Pension Plan (QPP) benefits (including additional CPP and QPP benefits). At the same time, it is assumed that the income limits for the GIS and Allowance will have increased in line with inflation prior to retirement. Together, this would normally result in a lower proportion of new retirees becoming eligible for these benefits over the projection period. However, the effect of income from Tax-Free Savings Accounts (TFSAs) being excluded for GIS and Allowance benefits is projected to partially offset the expected decline in recipient rates for these benefits.
Table 5 presents a summary of the projected recipient rates by type of benefit.
| Benefit | Males | Females | ||||
|---|---|---|---|---|---|---|
| 2025 | 2030 | 2060 | 2025 | 2030 | 2060 | |
| OAS | 93.5 | 94.0 | 94.7 | 94.9 | 95.1 | 95.6 |
| GIS-Single | 13.1 | 13.2 | 11.3 | 23.4 | 24.1 | 21.8 |
| GIS-Spouse a pensioner | 11.4 | 11.8 | 8.7 | 9.8 | 10.3 | 7.7 |
| GIS-Spouse not a pensioner | 3.3 | 3.1 | 2.2 | 0.9 | 0.9 | 0.6 |
| GIS-Spouse with allowance | 1.2 | 1.1 | 0.9 | 0.2 | 0.2 | 0.1 |
| GIS-AllTable 5 Footnote 3 | 28.8 | 29.2 | 23.1 | 34.3 | 35.4 | 30.2 |
| Allowance-Regular | 0.6 | 0.7 | 0.6 | 3.2 | 4.0 | 3.4 |
| Allowance-Survivor | 0.2 | 0.2 | 0.1 | 1.2 | 1.0 | 0.3 |
| Allowance-AllTable 5 Footnote 3 | 0.8 | 0.9 | 0.7 | 4.3 | 4.9 | 3.8 |
Table 5 Footnotes
| ||||||
5 Results
5.1 Overview
The key observations and findings of this report are described below.
- Demographic changes, notably the aging of the Canadian population, will have a major impact on the ratio of the number of people aged 20 to 64 to those aged 65 and over. This ratio is projected to fall from about 2.9 in 2026 to 2.1 in 2060.
- The number of beneficiaries of the OAS basic pension is projected to increase at a higher pace from 2026 to 2035, growing from an estimated 7.9 million in 2026 to 9.7 million by 2035, mainly due to the continuing retirement of the baby boom generation reaching age 65 over that period. Thereafter, the growth in the number of beneficiaries is projected to be lower. By 2060, the number of OAS basic pension beneficiaries is projected to reach 12.4 million.
- OAS basic pension annual expenditures are projected to increase from an estimated $70.7 billion in 2026 to $105.8 billion in 2035 and $223.4 billion by 2060.
- The number of GIS and Allowance beneficiaries is projected to increase at a higher pace from 2026 to 2035, growing from an estimated 2.7 million in 2026 to 3.4 million by 2035. The GIS recipient rate (i.e., the proportion of the Canadian population that has received, receives, or is projected to receive the GIS) is projected to slowly increase from 31.9% in 2026 to 32.5% in 2035 and to then slowly decrease to 26.9% by 2060.
- GIS and Allowance annual expenditures are projected to increase from an estimated $21.3 billion in 2026 to $30.7 billion in 2035 and $52.9 billion by 2060.
- Total annual OAS program expenditures (including administrative expenses) are projected to increase from an estimated $92.6 billion in 2026 to $137.2 billion in 2035 and $277.7 billion by 2060.
- The cost ratio of expenditures to GDP is projected to be 2.69% in 2025 and 2.76% in 2026. Thereafter, as shown in Chart 1, this ratio is projected to reach a high of around 2.9% between 2031 and 2036 due to the retirement of the baby boomers. After 2036, the ratio of expenditures to GDP is projected to gradually decrease to a level of 2.63% by the late 2050s, which is comparable to the historical levels of the early 1990s. This reduction is mainly attributable to expected slower growth in inflation compared to growth in wages and GDP and increases in additional CPP and QPP benefits.
Over time, price indexation of benefits that increases more slowly than the rate of growth in average employment earnings means that benefits will replace a decreasing share of an individual's pre-retirement earnings. One of the sensitivity tests shown in Appendix D of this report provides an indication of the impact on projected results if benefit rates were increased to partially reflect the growth in real wages.
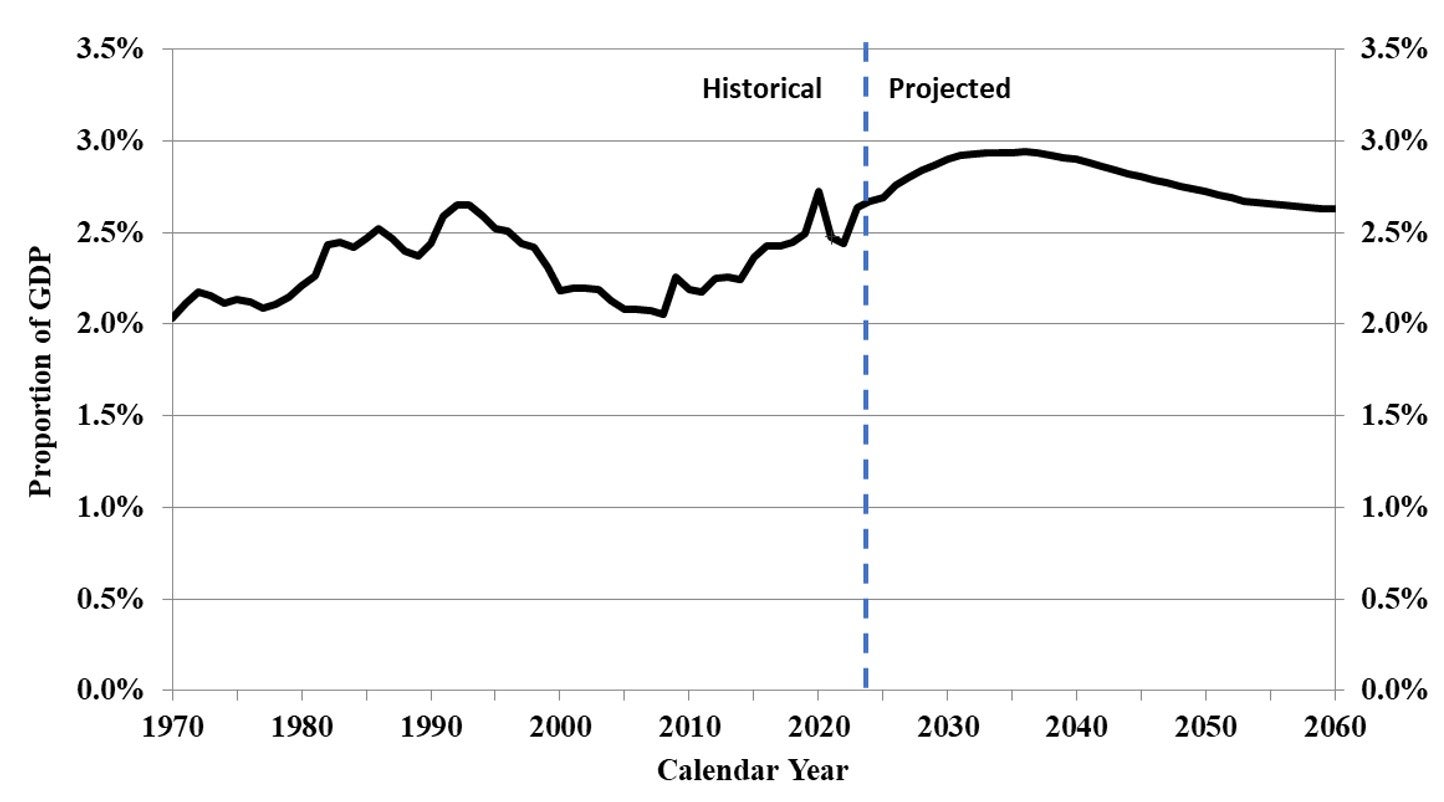
Chart 1 - Text version
| Calendar Year | Proportion of GDP |
|---|---|
| 1970 | 2.03% |
| 1971 | 2.11% |
| 1972 | 2.17% |
| 1973 | 2.15% |
| 1974 | 2.12% |
| 1975 | 2.14% |
| 1976 | 2.12% |
| 1977 | 2.09% |
| 1978 | 2.11% |
| 1979 | 2.15% |
| 1980 | 2.21% |
| 1981 | 2.26% |
| 1982 | 2.43% |
| 1983 | 2.44% |
| 1984 | 2.42% |
| 1985 | 2.47% |
| 1986 | 2.52% |
| 1987 | 2.47% |
| 1988 | 2.40% |
| 1989 | 2.38% |
| 1990 | 2.44% |
| 1991 | 2.59% |
| 1992 | 2.65% |
| 1993 | 2.65% |
| 1994 | 2.59% |
| 1995 | 2.52% |
| 1996 | 2.51% |
| 1997 | 2.44% |
| 1998 | 2.42% |
| 1999 | 2.31% |
| 2000 | 2.18% |
| 2001 | 2.20% |
| 2002 | 2.20% |
| 2003 | 2.19% |
| 2004 | 2.13% |
| 2005 | 2.08% |
| 2006 | 2.08% |
| 2007 | 2.07% |
| 2008 | 2.05% |
| 2009 | 2.26% |
| 2010 | 2.19% |
| 2011 | 2.18% |
| 2012 | 2.25% |
| 2013 | 2.26% |
| 2014 | 2.24% |
| 2015 | 2.37% |
| 2016 | 2.43% |
| 2017 | 2.43% |
| 2018 | 2.45% |
| 2019 | 2.49% |
| 2020 | 2.73% |
| 2021 | 2.48% |
| 2022 | 2.44% |
| 2023 | 2.64% |
| 2024 | 2.67% |
| Calendar Year | Proportion of GDP |
|---|---|
| 2025 | 2.68% |
| 2026 | 2.74% |
| 2027 | 2.78% |
| 2028 | 2.82% |
| 2029 | 2.85% |
| 2030 | 2.89% |
| 2031 | 2.91% |
| 2032 | 2.91% |
| 2033 | 2.92% |
| 2034 | 2.92% |
| 2035 | 2.92% |
| 2036 | 2.92% |
| 2037 | 2.92% |
| 2038 | 2.91% |
| 2039 | 2.90% |
| 2040 | 2.88% |
| 2041 | 2.87% |
| 2042 | 2.85% |
| 2043 | 2.83% |
| 2044 | 2.81% |
| 2045 | 2.79% |
| 2046 | 2.77% |
| 2047 | 2.76% |
| 2048 | 2.74% |
| 2049 | 2.72% |
| 2050 | 2.71% |
| 2051 | 2.69% |
| 2052 | 2.68% |
| 2053 | 2.66% |
| 2054 | 2.65% |
| 2055 | 2.64% |
| 2056 | 2.64% |
| 2057 | 2.63% |
| 2058 | 2.62% |
| 2059 | 2.62% |
| 2060 | 2.62% |
5.2 Number of beneficiaries
Table 6 and Table 7 present the historical and projected number of beneficiaries along with the respective overall recipient rates. The projected number of beneficiaries is derived from the product of the projected population and the relevant assumed recipient rates, which vary by year, age, sex, and type and level of benefit. Beneficiaries include those who receive benefits outside Canada.
The recipient rates shown in Table 7 reflect the eligible ages for program benefits, that is age 65 and over for the OAS basic pension and GIS, and ages 60 to 64 for the Allowance benefit. The OAS and GIS recipient rates also account for voluntary deferrals, which became effective 1 July 2013. The OAS basic pension recipient rates and number of beneficiaries shown in Table 6 and Table 7 are on a gross basis; that is, they have not been adjusted to account for the application of the OAS Recovery Tax, which is a provision of the Income Tax Act.
The OAS Recovery Tax, which applies to high-income pensioners, effectively reduces recipient rates, since very high-income pensioners may have their benefit completely reduced. In 2026, it is projected that 8.2% (or 646,000) of all OAS pensioners will be subject to the Recovery Tax, including 2.7% (213,000) whose OAS pensions are completely reduced. In 2060, it is projected that 10.5% (1.30 million) of all OAS pensioners will be subject to the Recovery Tax, including 3.5% (434,000) whose OAS pensions are completely reduced. Section 5 of Appendix B presents more detailed information on the projected impacts of the OAS Recovery Tax on the number of OAS basic pension beneficiaries and total amounts payable.
As shown in Table 7, the number of OAS pensioners is expected to increase at a higher pace from 2026 to 2035, growing from 7.9 million in 2026 to 9.7 million by the end of 2035. After 2035, due to the relative stability in the growth of the population aged 65 and over and in the basic pension recipient rates, the number of beneficiaries is expected to continue to increase but at a slower pace to reach 12.4 million by 2060.
The number of GIS beneficiaries is projected to increase at a higher pace from 2026 to 2035, growing from 2.7 million in 2026 to 3.3 million by 2035. Over that period, the increase in the number of basic pension and GIS beneficiaries is mainly a result of the aging of the population and the retirement of the baby boomers.
To determine whether an individual is eligible for the GIS or Allowance, retirement income from sources such as a Registered Retirement Savings Plan (RRSP), locked-in RRSP, and base and additional CPP and QPP benefits is compared to the GIS and Allowance income thresholds. Since these thresholds are indexed to inflation while CPP and QPP benefits are projected in line with wage growth before retirement, GIS and Allowance eligibility tends to decrease over time. However, throughout the projection period, it is assumed that the increased usage of TFSAs will have the opposite effect on eligibility.
The number of Allowance beneficiaries is projected to slightly increase over the period 2026 to 2030, going from an estimated 70,000 in 2026 to 71,000 by 2030, with the recipient rates slightly increasing from 2.6% to 3.0% over the same period. After 2030, the Allowance recipient rate stabilizes before slowly decreasing. In 2060, the Allowance recipient rate is expected to be 2.2%.
| Year | Population age 65+ (thousands) | Number of beneficiaries (thousands) | Recipient rates (percentages) | ||||
|---|---|---|---|---|---|---|---|
| OAS | GIS | Allowance | OAS | GIS | Allowance | ||
| 1966 | 1,222 | 1,199 | no data- | no data- | 98.1 | no data- | no data- |
| 1970 | 1,716 | 1,689 | 816 | no data- | 98.4 | 47.6 | no data- |
| 1975 | 1,957 | 1,925 | 1,069 | 72 | 98.4 | 54.6 | 8.0 |
| 1980 | 2,306 | 2,259 | 1,191 | 77 | 98.0 | 51.7 | 8.1 |
| 1985 | 2,648 | 2,595 | 1,290 | 119 | 98.0 | 48.7 | 10.5 |
| 1990 | 3,124 | 3,036 | 1,325 | 121 | 97.2 | 42.4 | 10.3 |
| 1995 | 3,506 | 3,447 | 1,338 | 108 | 98.3 | 38.2 | 8.9 |
| 2000 | 3,851 | 3,781 | 1,363 | 95 | 98.2 | 35.4 | 7.6 |
| 2005 | 4,214 | 4,163 | 1,515 | 94 | 98.8 | 35.9 | 6.2 |
| 2010 | 4,803 | 4,732 | 1,614 | 92 | 98.5 | 33.6 | 4.6 |
| 2015 | 5,722 | 5,597 | 1,798 | 77 | 97.8 | 31.4 | 3.4 |
| 2019 | 6,573 | 6,362 | 2,052 | 73 | 96.8 | 31.2 | 2.9 |
| 2020 | 6,810 | 6,581 | 2,095 | 74 | 96.6 | 30.8 | 2.9 |
| 2021 | 7,046 | 6,773 | 2,193 | 76 | 96.1 | 31.1 | 2.9 |
| 2022 | 7,298 | 6,953 | 2,271 | 71 | 95.3 | 31.1 | 2.7 |
| 2023 | 7,558 | 7,138 | 2,418 | 71 | 94.4 | 32.0 | 2.7 |
| 2024 | 7,820 | 7,354 | 2,515 | 68 | 94.0 | 32.2 | 2.5 |
Table 6 Footnotes
| |||||||
| Year | Population age 65+ (thousands) | Number of beneficiaries (thousands) | Recipient rates (percentages) | ||||
|---|---|---|---|---|---|---|---|
| OAS | GIS | Allowance | OAS | GIS | Allowance | ||
| 2025 | 8,083 | 7,617 | 2,568 | 70 | 94.2 | 31.8 | 2.6 |
| 2026 | 8,362 | 7,884 | 2,670 | 70 | 94.3 | 31.9 | 2.6 |
| 2027 | 8,629 | 8,143 | 2,772 | 71 | 94.4 | 32.1 | 2.7 |
| 2028 | 8,900 | 8,402 | 2,876 | 71 | 94.4 | 32.3 | 2.8 |
| 2029 | 9,157 | 8,652 | 2,978 | 71 | 94.5 | 32.5 | 2.9 |
| 2030 | 9,392 | 8,884 | 3,056 | 71 | 94.6 | 32.5 | 3.0 |
| 2031 | 9,586 | 9,082 | 3,115 | 70 | 94.7 | 32.5 | 2.9 |
| 2032 | 9,747 | 9,251 | 3,169 | 69 | 94.9 | 32.5 | 2.9 |
| 2033 | 9,897 | 9,406 | 3,218 | 68 | 95.0 | 32.5 | 2.9 |
| 2034 | 10,042 | 9,554 | 3,264 | 66 | 95.1 | 32.5 | 2.8 |
| 2035 | 10,184 | 9,696 | 3,307 | 65 | 95.2 | 32.5 | 2.8 |
| 2040 | 10,708 | 10,223 | 3,457 | 61 | 95.5 | 32.3 | 2.5 |
| 2045 | 11,128 | 10,623 | 3,493 | 60 | 95.5 | 31.4 | 2.2 |
| 2050 | 11,625 | 11,081 | 3,510 | 63 | 95.3 | 30.2 | 2.2 |
| 2055 | 12,225 | 11,638 | 3,473 | 64 | 95.2 | 28.4 | 2.0 |
| 2060 | 13,006 | 12,378 | 3,496 | 67 | 95.2 | 26.9 | 2.2 |
Table 7 Footnotes
| |||||||
5.3 Expenditures and average annual benefits
The historical and projected expenditures and average annual benefits by type are presented in Table 8 and Table 9. The amounts of OAS basic pension benefits presented in Table 8 and Table 9 do not account for the OAS Recovery Tax in the determination of benefits. The OAS Recovery Tax reduces the OAS basic pension by 15 cents for each dollar of income above a minimum threshold. It is estimated that in 2026 approximately 8.2% (or 646,000) of all OAS pensioners will be affected by the Recovery Tax, resulting in the repayment of about $3.3 billion or 4.6% of the total amount of basic pensions payable. Section 5 of Appendix B presents more detailed information on the projected impact of the OAS Recovery Tax on the basic pensions payable.
Total OAS basic pension expenditures are projected to increase from $70.7 billion in 2026 to $105.8 billion by 2035 and $223.4 billion by 2060. The projected average annual basic pension for beneficiaries aged 65 to 74 of $8,609 in 2026 is equal to about 95.6% of the projected maximum annual OAS pension at age 65 for 2026. The projected average annual basic pension for beneficiaries aged 75 and older of $9,210 in 2026 is equal to about 93.0% of the projected maximum annual OAS pension at age 75 for 2026. The OAS basic pension expenditures and average benefits account for voluntary deferrals, which became effective 1 July 2013, and the 10% increase in the pension payable to beneficiaries aged 75 and older, effective 1 July 2022.
The amounts of GIS and Allowance expenditures presented in Table 9 account for additional CPP and QPP benefits. For each benefit, total expenditures are the product of the number of beneficiaries and respective average benefit by age, sex, and type and level of benefit.
Total GIS expenditures are projected to increase from $20.7 billion in 2026 to $30.1 billion by 2035 and $52.1 billion by 2060. The projected average annual GIS benefit is $7,749 in 2026, which is about 58% of the projected maximum annual GIS single rate for 2026. In the long term, the interaction of TFSAs and additional CPP and QPP benefits results in the average GIS benefit slightly decreasing to about 56% of the maximum GIS single rate by the end of the projection period.
Total Allowance expenditures are projected to increase from $611 million in 2026 to $629 million by 2035 and $864 million by 2060. The projected overall average annual Allowance benefit is $8,696 in 2026, which is about 51% of the projected maximum regular annual benefit for 2026. The interaction of TFSAs and additional CPP and QPP benefits results in the average Allowance benefit decreasing to about 38% of the maximum Allowance regular rate by the end of the projection period.
Projected total annual OAS program expenditures for all benefits and administrative expenses are $92.6 billion in 2026, rising to $137.2 billion in 2035 and $277.7 billion by 2060. OAS basic pension benefits are projected to be 76% of total expenditures in 2026, and this proportion is expected to increase to 80% by 2060.
| Year | Expenditures ($ million) | Average annual benefit ($) | ||||||
|---|---|---|---|---|---|---|---|---|
| OAS | GIS | Allowance | Administrative expenses | Total | OAS | GIS | Allowance | |
| 1966 | 1,007 | - | - | 5 | 1,012 | 840 | - | - |
| 1970 | 1,611 | 274 | - | 9 | 1,894 | 954 | 336 | - |
| 1975 | 2,883 | 896 | 13 | 10 | 3,802 | 1,498 | 838 | 185 |
| 1980 | 5,147 | 1,772 | 169 | 34 | 7,122 | 2,279 | 1,488 | 2,186 |
| 1985 | 8,696 | 3,278 | 295 | 60 | 12,329 | 3,351 | 2,542 | 2,478 |
| 1990 | 12,484 | 3,954 | 452 | 67 | 16,957 | 4,112 | 2,985 | 3,732 |
| 1995 | 15,832 | 4,601 | 411 | 106 | 20,950 | 4,593 | 3,439 | 3,802 |
| 2000 | 18,669 | 5,019 | 389 | 89 | 24,166 | 4,937 | 3,682 | 4,087 |
| 2005 | 22,701 | 6,334 | 469 | 104 | 29,608 | 5,453 | 4,182 | 4,978 |
| 2010 | 27,984 | 7,807 | 550 | 126 | 36,467 | 5,913 | 4,837 | 5,999 |
| 2015 | 36,167 | 10,240 | 512 | 159 | 47,078 | 6,462 | 5,695 | 6,692 |
| 2019 | 43,945 | 12,901 | 558 | 263 | 57,667 | 6,907 | 6,287 | 7,678 |
| 2020 | 46,110 | 13,573 | 566 | 310 | 60,559 | 7,007 | 6,479 | 7,646 |
| 2021 | 48,035 | 13,862 | 550 | 340 | 62,787 | 7,093 | 6,320 | 7,230 |
| 2022 | 53,495 | 15,386 | 542 | 400 | 69,823 | 7,694 | 6,776 | 7,582 |
| 2023 | 59,353 | 17,622 | 608 | 555 | 78,138 | 8,315 | 7,289 | 8,541 |
| 2024 | 63,433 | 18,853 | 628 | 579 | 83,493 | 8,626 | 7,495 | 9,199 |
Table 8 Footnotes
| ||||||||
| Year | Expenditures ($ million) | Average annual benefit ($) | ||||||
|---|---|---|---|---|---|---|---|---|
| OAS | GIS | Allowance | Administrative expenses | Total | OAS | GIS | Allowance | |
| 2025 | 66,666 | 19,557 | 597 | 608 | 87,428 | 8,752 | 7,616 | 8,585 |
| 2026 | 70,654 | 20,690 | 611 | 644 | 92,599 | 8,962 | 7,749 | 8,696 |
| 2027 | 74,625 | 21,835 | 623 | 641 | 97,724 | 9,165 | 7,876 | 8,799 |
| 2028 | 78,708 | 23,013 | 632 | 635 | 102,988 | 9,368 | 8,002 | 8,894 |
| 2029 | 82,844 | 24,210 | 639 | 625 | 108,318 | 9,575 | 8,129 | 8,991 |
| 2030 | 86,937 | 25,312 | 643 | 610 | 113,502 | 9,786 | 8,283 | 9,087 |
| 2031 | 90,838 | 26,315 | 643 | 589 | 118,385 | 10,002 | 8,447 | 9,223 |
| 2032 | 94,574 | 27,272 | 642 | 612 | 123,100 | 10,223 | 8,605 | 9,324 |
| 2033 | 98,281 | 28,211 | 639 | 636 | 127,767 | 10,449 | 8,767 | 9,435 |
| 2034 | 102,020 | 29,149 | 634 | 659 | 132,462 | 10,678 | 8,931 | 9,546 |
| 2035 | 105,802 | 30,091 | 629 | 683 | 137,205 | 10,912 | 9,099 | 9,650 |
| 2040 | 124,083 | 34,561 | 624 | 796 | 160,064 | 12,138 | 9,998 | 10,180 |
| 2045 | 142,664 | 38,478 | 652 | 909 | 182,703 | 13,430 | 11,014 | 10,883 |
| 2050 | 164,251 | 42,551 | 710 | 1,038 | 208,550 | 14,822 | 12,122 | 11,359 |
| 2055 | 190,285 | 46,801 | 787 | 1,189 | 239,062 | 16,351 | 13,474 | 12,323 |
| 2060 | 223,399 | 52,057 | 864 | 1,382 | 277,702 | 18,048 | 14,890 | 12,796 |
Table 9 Footnotes
| ||||||||
5.4 Cost ratios
Since the program is financed from general revenues on a pay-as-you-go basis, it is useful to express its annual expenditures in relative terms rather than in absolute dollar terms. For this reason, the expenditures are presented as cost ratios using GDP as a measurement basis.
The GDP is projected using underlying assumptions of productivity, hours worked, and employment growth as projected under the Revised 32nd CPP Actuarial Report as at 31 December 2024. Table 10 and Table 11 present the historical and projected annual expenditures as a percentage of GDP.
The cost ratio of OAS program expenditures to GDP is projected to be 2.69% in 2025 and 2.76% in 2026. The retirement of the baby boomers is projected to increase the expenditures of the program, and the ratio is projected to reach a high of 2.9% during the 2030s. Thereafter, although the impacts of TFSAs reduce the amount of income for benefit calculation purposes and tend to increase this ratio over the long term, the growth in additional CPP and QPP benefits and the fact that OAS benefits are indexed to inflation as opposed to wages drive down the cost of the OAS program relative to the GDP over the long term. As a result, annual expenditures are expected to gradually fall to 2.63% of GDP by the late 2050s, which is comparable to the historical levels of the early 1990s.
The projected expenditures shown in Table 11 reflect the eligible ages for program benefits, that is, age 65 and over for the OAS basic pension and GIS, and ages 60 to 64 for the Allowance benefit. The OAS and GIS expenditures also account for voluntary deferrals, which became effective 1 July 2013, and the 10% increase in the OAS pension in July 2022 for beneficiaries aged 75 and older.
| Year | Gross domestic product ($ billion) | Expenditures as % of gross domestic productTable 10 Footnote 1 | ||||
|---|---|---|---|---|---|---|
| OAS | GIS | Allowance | Administrative expenses | Total | ||
| 1966 | 67 | 1.51 | no data - | no data - | 0.01 | 1.52 |
| 1970 | 93 | 1.73 | 0.29 | no data - | 0.01 | 2.03 |
| 1975 | 178 | 1.62 | 0.50 | 0.01 | 0.01 | 2.14 |
| 1980 | 323 | 1.59 | 0.55 | 0.05 | 0.01 | 2.21 |
| 1985 | 500 | 1.74 | 0.66 | 0.06 | 0.01 | 2.47 |
| 1990 | 696 | 1.79 | 0.57 | 0.06 | 0.01 | 2.44 |
| 1995 | 832 | 1.90 | 0.55 | 0.05 | 0.01 | 2.52 |
| 2000 | 1,106 | 1.69 | 0.45 | 0.04 | 0.01 | 2.18 |
| 2005 | 1,422 | 1.60 | 0.45 | 0.03 | 0.01 | 2.08 |
| 2010 | 1,666 | 1.68 | 0.47 | 0.03 | 0.01 | 2.19 |
| 2015 | 1,990 | 1.82 | 0.51 | 0.03 | 0.01 | 2.37 |
| 2019 | 2,314 | 1.90 | 0.56 | 0.02 | 0.01 | 2.49 |
| 2020 | 2,221 | 2.08 | 0.61 | 0.03 | 0.01 | 2.73 |
| 2021 | 2,536 | 1.89 | 0.55 | 0.02 | 0.01 | 2.48 |
| 2022 | 2,864 | 1.87 | 0.54 | 0.02 | 0.01 | 2.44 |
| 2023 | 2,965 | 2.00 | 0.59 | 0.02 | 0.02 | 2.64 |
| 2024 | 3,109 | 2.04 | 0.61 | 0.02 | 0.02 | 2.69 |
Table 10 Footnotes
| ||||||
| Year | Gross domestic product ($ billion) | Expenditures as % of gross domestic productTable 11 Footnote 1 | ||||
|---|---|---|---|---|---|---|
| OAS | GIS | Allowance | Administrative expenses | Total | ||
| 2025 | 3,249 | 2.05 | 0.60 | 0.02 | 0.02 | 2.69 |
| 2026 | 3,355 | 2.11 | 0.62 | 0.02 | 0.02 | 2.76 |
| 2027 | 3,492 | 2.14 | 0.63 | 0.02 | 0.02 | 2.80 |
| 2028 | 3,629 | 2.17 | 0.63 | 0.02 | 0.02 | 2.84 |
| 2029 | 3,775 | 2.19 | 0.64 | 0.02 | 0.02 | 2.87 |
| 2030 | 3,911 | 2.22 | 0.65 | 0.02 | 0.02 | 2.90 |
| 2031 | 4,052 | 2.24 | 0.65 | 0.02 | 0.01 | 2.92 |
| 2032 | 4,199 | 2.25 | 0.65 | 0.02 | 0.01 | 2.93 |
| 2033 | 4,352 | 2.26 | 0.65 | 0.01 | 0.01 | 2.94 |
| 2034 | 4,509 | 2.26 | 0.65 | 0.01 | 0.01 | 2.94 |
| 2035 | 4,672 | 2.26 | 0.64 | 0.01 | 0.01 | 2.94 |
| 2040 | 5,523 | 2.25 | 0.63 | 0.01 | 0.01 | 2.90 |
| 2045 | 6,514 | 2.19 | 0.59 | 0.01 | 0.01 | 2.80 |
| 2050 | 7,654 | 2.15 | 0.56 | 0.01 | 0.01 | 2.72 |
| 2055 | 9,007 | 2.11 | 0.52 | 0.01 | 0.01 | 2.65 |
| 2060 | 10,565 | 2.11 | 0.49 | 0.01 | 0.01 | 2.63 |
Table 11 Footnotes
| ||||||
6 Reconciliation with previous triennial report
6.1 Introduction
The results presented in this report differ from those presented in the previous triennial report, the 18th Actuarial Report on the OAS program as at 31 December 2021, for a variety of reasons. Differences between the actual experience from 2022 through 2024 and that projected in the 18th Actuarial Report on the OAS program are addressed in subsection 6.2 below. Since historical results provide the starting point for the projections shown in this report, these historical differences between actual and projected experience have an effect on the projections. Detailed reconciliations of the projected expenditures are presented in Appendix C.
6.2 Experience update – 2022 to 2024
The components of change in the program expenditures from 31 December 2021 to 31 December 2024 are summarized in Table 12.
| Expenditures | Actual | ExpectedTable 12 Footnote 2 | Difference Actual less expected |
|---|---|---|---|
| Expenditures for the OAS | 176,281 | 176,929 | (648) |
| Expenditures for the GIS | 51,861 | 50,856 | 1,005 |
| Expenditures for the Allowance | 1,778 | 1,714 | 64 |
| Administrative expenses | 1,534 | 1,148 | 386 |
| Total expenditures | 231,454 | 230,647 | 807 |
Table 12 Footnotes
| |||
OAS basic pension expenditures during the period were $648 million lower than projected. For the most part, this is because there were about 1.2% fewer beneficiaries due to higher deferrals than expected. GIS expenditures were $1,005 million higher than projected and Allowance expenditures were $64 million higher than projected. Administrative expenses were $386 million higher than expected over the period.
6.3 Changes in expenditures as a percentage of the GDP
Table 13 presents the main elements of all changes in the expenditures expressed as a percentage of the GDP since the 18th Actuarial Report on the OAS program.
The main methodology changes were related to improvements in modeling NPR, which had the effect of decreasing the cost ratio over the long term. The experience update over the period 2022 to 2024 had the impact of increasing both the projected expenditures because of higher inflation and the GDP, which resulted in a net decrease in the cost ratio. The combined changes in demographic assumptions decreased the cost ratio mainly due to migration, but this effect was counterbalanced in the long term by a decrease in the fertility rates. The combined changes in economic assumptions resulted in the decrease of the projected GDP, and therefore the increase in the cost ratio, mainly due to lower real wage growth.
Overall, the update in experience and changes in all assumptions lead to lower cost ratios for most of the projection period compared to the previous 18th Actuarial Report on the OAS program. In 2030, the cost ratio is 2.90% compared to 2.98% under the previous actuarial report. By 2060, the cost ratio stays stable and is projected to 2.63% compared to 2.64% under the previous actuarial report.
| Reconciliation of expenditures | 2025 | 2030 | 2060 |
|---|---|---|---|
| 18th Actuarial Report on the OAS Program | 2.78 | 2.98 | 2.64 |
Legislated amendment
| 0.00 | 0.00 | 0.00 |
| Total amendments | 0.00 | 0.00 | 0.00 |
| Improvements in methodology | 0.00 | 0.01 | (0.11) |
| Experience update (2022 to 2024) | (0.06) | (0.06) | (0.05) |
| Changes in demographic assumptions | (0.11) | (0.07) | 0.01 |
| Changes in economic assumptions | 0.08 | 0.06 | 0.13 |
| Changes in benefit assumptions | 0.00 | 0.00 | 0.01 |
| Changes in other assumptions | 0.01 | 0.00 | 0.00 |
| 19th Actuarial Report on the OAS Program | 2.69 | 2.90 | 2.63 |
6.4 Changes in expenditures
Table 14 presents the main elements of all changes in the expenditures since the 18th Actuarial Report on the OAS program.
Changes related to improvements in the methodology used to model NPR led to a decrease in expenditures. The net impact of all changes in the expenditures is minor, and the projected expenditures in this report are similar to the expenditures projected under the 18th Actuarial Report on the OAS program.
| Reconciliation of expenditures | 2025 | 2030 | 2060 |
|---|---|---|---|
| 18th Actuarial Report on the OAS Program | 87.99 | 113.49 | 276.52 |
Legislated amendment
| 0.00 | 0.00 | 0.00 |
| Total amendments | 0.00 | 0.00 | 0.00 |
| Improvements in methodology | (0.17) | (0.34) | (12.15) |
| Experience update (2022 to 2024) | (0.55) | 0.42 | 5.09 |
| Changes in demographic assumptions | 0.02 | (0.06) | 6.22 |
| Changes in economic assumptions | (0.05) | 0.11 | 1.21 |
| Changes in benefit assumptions | 0.02 | (0.15) | 0.81 |
| Changes in other assumptions | 0.17 | 0.05 | 0.00 |
| 19th Actuarial Report on the OAS Program | 87.44 | 113.51 | 277.71 |
7 Actuarial opinion
In our opinion, considering that this 19th Actuarial Report on the Old Age Security program as at 31 December 2024 was prepared pursuant to the Public Pensions Reporting Act:
- the data on which this report is based are sufficient and reliable for the purposes of this report;
- the assumptions used are, individually and in aggregate, reasonable and appropriate for the purposes of this report; and
- the methods employed are appropriate for the purposes of this report.
This report has been prepared, and our opinions given, in accordance with accepted actuarial practice in Canada, in particular, the General Standards and the Practice-Specific Standards for Social Security Programs of the Standards of Practice of the Canadian Institute of Actuaries.
As of the date of the signing of this report, we have not learned of any events that would have a material impact on the actuarial review of the OAS program as at 31 December 2024.
Assia Billig, FCIA, FSA
Chief Actuary
Laurence Frappier, FCIA, FSA
Senior Actuary
François Boulé, FCIA, FSA
Senior Actuary
Jean-François Lussier, FCIA, FSA
Senior Actuary
Ottawa, Canada
25 June 2026
Appendix A — Summary of program provisions
A.1 Introduction
The Old Age Security Act came into force on 1 January 1952. Benefits provided under the Old Age Security Act include the basic pension, the Guaranteed Income Supplement, and the Allowance, which started being paid in 1952, 1967, and 1975, respectively. The Allowance for the survivor benefit started in 1985.
Since the inception of the Old Age Security program, the Old Age Security Act has been amended several times. The Old Age Security Act was most recently amended by An Act to amend the Old Age Security Act (Guaranteed Income Supplement) (Bill C-12), which received Royal Assent on 3 March 2022.
Bill C-12 amended the Old Age Security Act to exclude Canada Emergency Response Benefits and other COVID-19 pandemic-related assistance payments from a person's income when determining the amount of GIS or Allowance benefits for any month after June 2022.
This Appendix A is meant only to provide a summary of the provisions of the OAS program. The legislation shall prevail if there is any discrepancy between it and this summary.
A.2 Financing
All benefits provided under the Old Age Security Act are financed on a pay-as-you go basis and paid out of the Consolidated Revenue Fund.
A.3 Basic pension
The OAS basic pension is a monthly benefit available, on application, to anyone age 65 or over who meets the residence and legal status requirements specified in the Old Age Security Act.
A.3.1 Eligibility conditions
To qualify for an OAS basic pension, a person must be 65 years of age or older, and
- must be a Canadian citizen or a legal resident of Canada on the day preceding the approval of their application; or
- if the person no longer lives in Canada, must have been a Canadian citizen or a legal resident of Canada on the day preceding the day they stopped living in Canada.
To qualify for an OAS basic pension payable in Canada, an individual must have resided in Canada for at least 10 years after age 18. To receive the OAS pension while living outside Canada, at least 20 years of residence in Canada after age 18 is required. International social security agreements may help individuals meet these residence requirements. As of 1 January 2011, the OAS basic pension is not payable to incarcerated individuals, in accordance with the provisions of the Eliminating Entitlements for Prisoners Act.
A.3.2 Amount of benefits
The amount of a person's pension is determined by their age and the total length of time they have lived in Canada, according to the following rules:
- The OAS pension payable to a person aged 75 or older is increased by 10%.
- A person who has lived in Canada, after reaching age 18, for periods that total at least 40 years may qualify for a full OAS pension.
- A person who has not lived in Canada for 40 years after reaching age 18 may still qualify for a full pension if, on 1 July 1977, he or she was 25 years of age or over, and
- lived in Canada on that date, or
- had lived in Canada before that date and after reaching age 18, or
- possessed a valid immigration visa on that date.
In such cases, the individual must have lived in Canada for the 10 years immediately prior to the approval of the application for the pension. Absences during this 10-year period may be offset if, after reaching age 18, the applicant was present in Canada before those 10 years for a total period that was at least three times the length of absence. In this instance, however, the applicant must also have lived in Canada for at least one year immediately prior to the date of the approval of the application.
- A person who cannot meet the requirements for the full OAS pension may qualify for a partial pension. A partial pension is earned at the rate of 1/40th of the full monthly pension for each complete year of residence in Canada after reaching age 18. Once a partial pension has been approved, it may not be increased as a result of additional years of residence in Canada.
Effective 1 July 2013, individuals may opt to defer receiving the OAS basic pension by up to five years after the eligible age (i.e., age 65 or older for those meeting the minimum residency requirement after age 65) in exchange for a higher pension. The deferred pensions are increased by 0.6% for each month after the eligible age until the month in which the application for the pension is approved (the deferral period) but in no case later than age 70. For those eligible for a basic pension at age 65, the maximum pension adjustment is 36% at age 70. In the case where an individual, who is entitled to a partial pension, chooses to defer receipt of the pension, the pension amount paid is the greater of the increased pension over the individual's deferral period and the higher pension resulting from accruing additional years of residency over that period.
The OAS basic pension is subject to income tax. The amount of the pension paid to persons with high incomes is also reduced through a provision of the Income Tax Act often referred to as the "OAS Recovery Tax". For this purpose, an individual's total net annual income is after pension income splitting, if that option is elected by OAS beneficiaries who are married or common-law partners.
OAS Recovery Tax deductions are withheld at source. The deductions are estimates of the tax owed and are recalculated in July of each year based on the OAS recipient's previous year's net income. The Recovery Tax actually owed for a given year is determined the following year and compared to the deductions made, with the given year's tax liability adjusted accordingly.
The income threshold for the Recovery Tax is indexed upward in accordance with increases in the CPI. For every dollar of income above this limit, the amount of the basic pension is reduced by 15 cents. Income earned within a TFSA or withdrawals made from a TFSA are excluded from total net annual income for the purpose of determining the amount of the OAS Recovery Tax, which could then result in a higher basic pension payable.
A.4 Guaranteed Income Supplement
The GIS is a monthly benefit paid to residents of Canada who receive an OAS basic pension (either the full amount or a partial amount) and who have little or no other income.
Payment of the GIS may begin in the same month as payment of the basic pension. The amount of the benefit varies according to income (see below). Most individuals receiving the GIS can continue to do so by filing their income tax returns, rather than making a new application each year. The amount of monthly payments may increase or decrease according to reported changes in a person's yearly income. Any income earned within a TFSA or withdrawals made from a TFSA are not considered as income for the purpose of determining the level of GIS benefit entitlement.
Unlike the OAS basic pension, the GIS is not subject to income tax. The GIS is not payable outside Canada beyond a period of six months following the month of departure from Canada, regardless of how long the person previously lived in Canada.
A.4.1 Eligibility conditions
To receive the GIS, a person must be receiving an OAS basic pension. Eligibility for the GIS is determined every year based on the previous year's income. Income (as defined for purposes of the GIS and Allowance benefits under the Old Age Security Act) received in the previous year is used to calculate the amount of benefits paid during the period starting on 1 July of a calendar year and ending on 30 June of the following calendar year.
In general, income as defined under the Income Tax Act is included subject to certain exemptions. Exemptions from income include any payments received under the OAS program (basic pension, GIS, and Allowance benefits), the first $5,000 of employment or self-employment income and 50% of employment or self-employment income between $5,000 and $15,000. In combination, the full and partial employment income exemption can result in a maximum total employment income exemption of $10,000.
The resulting estimated income of an individual (or, the combined income of the individual and their spouse or common-law partner) cannot exceed certain limits.
Persons admitted to Canada as sponsored immigrants after 6 March 1996 and qualifying for benefits after January 2001 are not eligible, generally speaking, to receive the GIS for the duration of a sponsorship, up to a maximum of ten years. Exceptions are made, however, if an immigrant's sponsor dies, is incarcerated for a period of more than six months, is convicted of a criminal offence relating to the sponsored individual, or undergoes personal bankruptcy.
A spouse or common-law partner who becomes involuntarily separated due to, for example, incarceration or institutionalization of their spouse or partner, is considered to be single in regard to applying for the GIS benefit.
Since a person may only receive the GIS if also in receipt of the OAS basic pension, the GIS is not payable to incarcerated individuals as per the provisions of the Eliminating Entitlements for Prisoners Act.
A.4.2 Amount of benefits
The amount of the GIS to which a person is entitled depends on their length of residence in Canada, marital status, and income. If the person is married or living in a common‑law relationship, the combined income of the person and their spouse or common-law partner is taken into consideration when the amount of the GIS benefit is calculated.
To be entitled to a full GIS benefit, applicants must have resided in Canada for at least 10 years after reaching age 18. For applicants who are admitted to Canada after 6 March 1996 and qualify for OAS benefits after January 2001, and who have less than 10 years of residence in Canada after age 18, a partial benefit is payable provided, as noted in the previous section, that the person is not a sponsored immigrant who is still in the period of sponsorship. The partial benefit is calculated at the rate of 1/10th of the amount of the full benefit for each complete year of residence in Canada after age 18. The proportion payable is recalculated each year, taking into account additional residence in Canada during the previous year, building gradually to a full benefit after 10 years.
There are two rates of payment for a GIS benefit. The single rate applies to single individuals – including widowed, divorced or separated persons as well as individuals who have never been married and to persons for whom their spouses or common-law partners do not receive either the OAS pension or the Allowance. The single rate also applies to spouses or common-law partners who become involuntarily separated from their spouses or partners as mentioned above.
The married rate applies both to married couples and to couples living in common‑law relationships, where either both spouses are OAS pensioners or where one spouse is eligible for the Allowance benefit.
The single rate is higher than the married rate, reflecting the higher cost of living alone. However, each member of a married or common-law couple is entitled to their own benefit, so the combined benefits for a couple are higher than those for a single person.
As of 1 July 2011, top-up benefits are payable to GIS recipients who receive benefits at the single rate, as described above, and to couples that include a GIS recipient. The top-ups are reduced by 25 cents for every dollar of income in excess of $2,000 for GIS single recipients and $4,000 of combined income for couples.
A special provision applies to persons who receive a partial OAS pension. In this case, the supplement is increased by the difference between the maximum OAS pension and the partial OAS pension in order to provide the same combined monthly pension and supplement to beneficiaries with the same level of income. The additional amount may result in the supplement exceeding the maximum GIS payable.
For a single, widowed, divorced or separated person, the maximum monthly GIS benefit is reduced by 50 cents for every dollar of monthly income (i.e., annual income divided by 12). This reduction is in addition to any reduction to the top-up.
If both spouses or common-law partners are receiving the OAS basic pension, the maximum monthly GIS of each person is reduced by 25 cents for every dollar of other combined monthly income, which is in addition to any reduction applied to the top-up.
A special provision applies in the case of a couple in which only one spouse or common-law partner is a pensioner, and the other is not eligible for either the OAS pension or the Allowance. In this instance, the pensioner can receive the GIS at the higher rate paid to those who are single. Moreover, the maximum monthly GIS is reduced by 25 cents for every dollar of the couple's combined monthly income, and the reduction of 25 cents is applied only when the combined monthly income of the couple exceeds the maximum monthly OAS pension, where that amount, if not a multiple of $4, is rounded to the next higher multiple of $4. This reduction is in addition to any reduction applied to the top-up benefit.
In the case of a couple in which one spouse or common-law partner receives the GIS and the other receives the Allowance, the GIS is paid at the rate paid to those who are married, and the maximum monthly GIS is reduced by 25 cents for every dollar of the couple's combined monthly income. The reduction of 25 cents is applied only when the combined monthly income of the couple exceeds four-thirds times the maximum monthly OAS pension, where that pension, if not a multiple of $3, is rounded to the next higher multiple of $3. This reduction is in addition to any reduction applied to the top-up.
GIS recipients whose spouse or common-law partner is incarcerated are considered to be single recipients for the purpose of determining the amount of the GIS benefit.
All GIS benefits including top-ups are adjusted quarterly in line with changes in the CPI, as described in subsection 6. No increase is applied to GIS benefits payable to OAS pensioners who defer receiving their basic pensions in exchange for increased pensions.
A.5 Allowance
The Allowance monthly benefit is designed to recognize the difficult circumstances faced by couples living on the pension of only one spouse as well as by many widowed persons. Since 1999, most of those receiving the Allowance can continue to do so by filing their income tax returns, rather than making a new application each year. Effective 1 July 1999, income (as defined for purposes of the GIS and the Allowance benefits under the Old Age Security Act) received in the previous calendar year is used to calculate the amount of benefits paid during the period starting on 1 July of a calendar year and ending on 30 June of the following calendar year.
Like the GIS, Allowance benefits are not subject to income tax. In addition, also like the GIS, Allowance benefits are not payable outside Canada beyond a period of six months following the month of departure from Canada, regardless of how long the person previously lived in Canada.
A.5.1 Eligibility conditions
The Allowance may be paid to the spouse or common-law partner of a senior receiving OAS and GIS benefits, or to a survivor, who, in each case, is between the ages of 60 and 64 and who has lived in Canada for at least 10 years after reaching age 18. An applicant must also be a Canadian citizen or a legal resident of Canada on the day preceding the approval of the application. The same income exclusions and deductions that apply to the GIS also apply to the Allowance benefit.
The Allowance stops being paid when the person becomes eligible for a basic pension at age 65, leaves Canada for more than six months, or dies. For a couple, the Allowance stops being paid if the older spouse or common-law partner ceases to be eligible for the GIS, or if the spouses separate, divorce, or dissolve their common-law partnership. In addition, in the case of survivors, the Allowance ceases if the person remarries. Sponsored immigrants are subject to the same conditions regarding eligibility as are described in the preceding section regarding the GIS.
As of 1 January 2011, the Allowance is not payable to any individual incarcerated in an institution in accordance with the provisions of the Eliminating Entitlements for Prisoners Act. However, Allowance benefits paid to spouses or common-law partners of incarcerated individuals remain payable.
A.5.2 Amount of benefits
The Allowance is an income tested benefit. Like the GIS, if the recipient is married or living in a common law relationship, the combined income of the recipient and their spouse or common-law partner is taken into account in determining the amount of the Allowance. In addition, to be entitled to the full or partial Allowance benefits, the same rules apply as for GIS benefits regarding admittance to and years of residence in Canada and the recalculation of benefits, described above in section A.4.2.
As of 1 July 2011, top-up benefits are payable to Allowance recipients for both the regular benefit (i.e., Allowance for spouses and common-law partners of GIS recipients) and the survivor benefit. The top-ups are reduced by 25 cents for every dollar of income in excess of $2,000 for Allowance (survivor) recipients and $4,000 of combined income for couples.
The maximum amount payable to the spouse of a pensioner under the regular Allowance benefit is equal to the combination of a full OAS pension and the maximum GIS at the married rate. The maximum amount payable for the survivor Allowance benefit is higher than the regular Allowance benefit, recognizing the higher cost of living alone.
The OAS‑equivalent portion of the maximum monthly Allowance benefit (regular and survivor) is reduced at a rate of 75 cents for every dollar of the person's or couple's monthly income until this portion is reduced to zero. Up to this level of income the GIS portion remains payable at the maximum. For the regular Allowance benefit, both the GIS‑equivalent portion of the Allowance and the pensioner's GIS are then reduced by 25 cents for every additional dollar of the couple's combined monthly income. For the survivor Allowance benefit, the GIS‑equivalent portion is reduced by 50 cents for every additional dollar of monthly income. The reductions to the Allowance benefits are in addition to any applied to the top-ups.
In the case where a pensioner of a spouse of common-law partner is incarcerated, the couple's monthly income for the purpose of determining the spousal Allowance benefit is the monthly income of the spouse or common-law partner only.
All Allowance benefits including top-ups are adjusted quarterly in line with changes in the CPI, as described in subsection 6. No increase is applied to Allowance benefits payable to spouses or common-law partners of OAS pensioners who defer receiving their basic pensions in exchange for increased pensions.
A.6 Inflation adjustments
All benefit amounts under the Old Age Security Act are adjusted at the beginning of each calendar quarter in line with changes in the CPI. However, if the CPI decreases, benefit amounts do not decrease, but are held constant until the CPI exceeds its previous peak.
Appendix B — Data, assumptions and methodology
B.1 Introduction and context
This Appendix describes the data, assumptions, and methodology that underlie the financial projections in the Results section 5 of this report.
Future expenditures and cost ratios are projected over a long period of time, i.e., up to the year 2060, and depend on assumptions such as those regarding fertility, mortality, migration, labour force participation, job creation, unemployment, inflation, and employment earnings. These assumptions form the basis for the projections of future expenditures of the OAS program and cost measurement base (GDP).
Although the demographic and economic assumptions represent the Chief Actuary's best estimates, the resulting estimates in this report should be interpreted with caution. These estimates are not intended to be predictions, but rather projections of the costs of the program. The assumptions used in this report are generally consistent with the best-estimate assumptions used in the Revised 32nd CPP Actuarial Report as at 31 December 2024.
The future expenditures of the OAS program depend on many economic factors. It is important to define the individual economic assumptions in the context of a long‑term overall economic perspective. The Canadian and global economies are going through a period of heightened uncertainty, due in part to escalating trade tensions, environmental risks, and geopolitical conflicts.
Furthermore, the projected continued aging of the population in the future, albeit at a slower pace than observed in the past, combined with the continued retirement of the baby boom generation will certainly create significant social and economic changes. It is possible that the evolution of the working-age population, especially the active population, will be quite different from what has been historically observed and what has been assumed for the purpose of this report.
For this report, it is assumed that, despite the current uncertain outlook for major economies and the projected continued aging of the Canadian population, a moderate and sustained growth in the Canadian and global economies will persist throughout the projection period.
As all the above-mentioned events evolve, the economic and demographic environments continue to be subject to sustained volatility and unpredictability. The OCA will continue to monitor current and emerging trends and will adjust assumptions as needed in future reports.
B.2 Data
The data used for this report are the same as for the Revised 32nd CPP Actuarial Report (see Table 38 of that report). In addition, historical data on OAS program beneficiaries were obtained from Employment and Social Development Canada (ESDC), and the Canada Revenue Agency (CRA) provided income tax return information.
The data used in this report are based on either sex at birth or gender identity, depending on availability from the data. The choice of variable has no material impact on the results. For simplicity, the terms "sex," "male," and "female" are used throughout this report.
B.3 Demographic assumptions
The historical and projected populations of Canada are required for the calculation of future benefits.
The population of Canada as at 1 July 2024 is used as a starting point. The population is then projected by age and sex from one year to the next by adding births and net migrants and subtracting deaths. The annual numbers of births, net migrants (other than for non-permanent residents), and deaths are determined by applying the fertility, migration, and mortality assumptions to the starting population. For non-permanent residents (NPR), however, only fertility and migration assumptions are applied, mortality is not modeled. This reflects the stable demographic profile of this group: individuals frequently enter and exit the NPR population, but the overall composition of the group used for the population projection remains consistent from year to year. Specifically, the average age and sex distributions are held constant, as NPR are assumed to re-enter the population each year with the same characteristics. As a result, NPR are not aged forward in the same way as the rest of the population.
B.3.1 Initial Population as at 1 July 2024
The starting point for the demographic projections is based on the most recent Statistics Canada population estimates as at 1 July 2024 for Canada, by age and sex. The estimates are based on the 2021 Census. These estimates are adjusted by ungrouping ages 100 and older into individual ages using the observed distribution in 2024 of OAS program beneficiaries by age for ages 100 and older.
B.3.2 Fertility rates
There are two definitions for the fertility rate: the total fertility rate and the cohort fertility rate. The total (or synthetic) fertility rate corresponds to the average number of children born in a given calendar year. Specifically, it is the sum of the fertility rates by age group for women aged 15 to 49 in a given calendar year. In comparison, the cohort fertility rate is the average number of children born to a woman in her lifetime, for women born in a specific year. It gives an idea of trends and variations between different generations over time.
The total fertility rate in Canada has declined significantly since the baby boom period, when the rate peaked at nearly 4.0 children per woman in the late 1950s. The baby bust period that followed in the mid-1960s initiated a decline in total fertility rates, resulting in a then-record low of 1.6 children per woman by the mid-1980s. The total fertility rate rose slightly from the late 1980s to the early 1990s, but then generally declined further to a level of 1.5 by the year 2000. Starting in the 2000s, Canada was one of many industrialized countries that saw their total fertility rates increase. By 2008, the total fertility rate for Canada reached 1.7. However, in some industrialized countries, including Canada, the total fertility rate has decreased overall since 2008, which could be largely attributable to the 2008 economic downturn and continuing economic uncertainty. Since 2020, aside from a temporary increase in 2021, fertility rates followed a steep decline. Canada, once in the middle of the pack amongst industrialized countries, is now positioned with Italy and Japan as one of the countries with low fertility rates.
The total fertility rate for Canada stood at 1.41 in 2020. It increased slightly to 1.44 in 2021 but has decreased since then to 1.26 in 2023. The housing crisis, economic uncertainty, anxiety regarding climate change, and the general population's mental health are all factors that may have contributed to the steady decline in the fertility rate in recent years. As well, the increase in the number of NPR may have had a downward effect on the Canadian fertility rate since NPR are less likely to have children during their non-permanent resident status.
Fertility rates are affected by many factors, including social attitudes, reproductive technologies, as well as economic and environmental conditions. Although there have been periods of growth in the total fertility rate in recent decades, it is unlikely that the rate will return to historical levels in the absence of significant societal changes.
In 2021, the Government of Canada worked with provinces and territories to establish a Canada-Wide Early Learning and Child Care (CWELCC) plan. Consistent with what was experienced in Quebec with the introduction of the Childcare Centers, the CWELCC plan could lead to an increase in fertility rates for certain age groups and hence was considered in setting the assumptions for this report. The effect on the fertility rates is assumed to occur over the first several years following the adoption of the system before leveling out.
To determine the ultimate total fertility rate for Canada, the historical fertility rate of each age group was studied and projected independently. For most age groups, a 20-year period of data was used to establish a trending model that provides the best fit using historical patterns and anticipated future movements. The age group 25-29 fertility rate is sensitive to data of recent years, and as such, only partial credibility was used for the most recent years. The age group 30-34 fertility rate does not align well with trending models. Its projection was therefore established based on professional judgment. Some age group rates were also adjusted upward to account for expected effects from the CWELCC plan.
Based on historical analysis and the factors mentioned above, it is assumed that the total fertility rate from 2033 onward for Canada will be 1.35 children per woman, which is lower than the ultimate rate of 1.54 assumed for the 18th OAS Program Actuarial Report.
Although the historical age group rates and resulting total fertility rates are used to set the assumption for the future, it is nonetheless useful and informative to consider the historical progression of the cohort fertility rates. Over time, the assumed age group rates lead to cohort fertility rates which converge to the total fertility rate assumption, as shown for Canada in Table 15.
The cohort fertility rates in Canada have declined over time. For females born in the year 1940, who reached the end of their childbearing years (turned age 49) in 1989, the cohort rate was 2.69. However, for females reaching the end of their childbearing years in 2023 (born in 1974), the cohort fertility rate was 1.83.
| Year of birth of womanTable 15 Footnote 1 | Annual fertility rates by age group (per 1,000 women)Table 15 Footnote 2 | Cohort fertility rates per womanTable 15 Footnote 2 | ||||||
|---|---|---|---|---|---|---|---|---|
| 15-19 | 20-24 | 25-29 | 30-34 | 35-39 | 40-44 | 45-49 | ||
| 1940 | 59.7 | 231.6 | 152.6 | 70.5 | 20.3 | 3.1 | 0.1 | 2.69 |
| 1945 | 54.7 | 161.4 | 130.4 | 65.7 | 19.9 | 3.3 | 0.1 | 2.18 |
| 1950 | 45.0 | 118.9 | 126.2 | 67.6 | 23.3 | 4.2 | 0.2 | 1.93 |
| 1955 | 37.4 | 103.7 | 121.1 | 73.6 | 29.0 | 5.2 | 0.2 | 1.85 |
| 1960 | 31.3 | 91.3 | 117.5 | 86.1 | 32.6 | 6.1 | 0.4 | 1.83 |
| 1965 | 26.0 | 76.8 | 121.2 | 84.9 | 36.1 | 7.9 | 0.5 | 1.77 |
| 1970 | 22.7 | 76.5 | 104.7 | 91.2 | 48.6 | 10.7 | 0.8 | 1.78 |
| 1975 | 25.6 | 64.6 | 99.0 | 108.0 | 53.4 | 11.7 | 0.9 | 1.82 |
| 1980 | 20.0 | 54.5 | 102.0 | 108.5 | 57.1 | 12.7 | 1.1* | 1.78* |
| 1985 | 15.1 | 52.7 | 96.4 | 108.0 | 56.1 | 12.7* | 1.2* | 1.71* |
| 1990 | 13.9 | 44.7 | 87.3 | 98.0 | 58.6* | 13.2* | 1.3* | 1.59* |
| 1995 | 12.1 | 37.2 | 68.4 | 98.6* | 62.1* | 13.3* | 1.3* | 1.47* |
| 2000 | 7.8 | 25.2 | 65.7* | 104.0* | 62.8* | 13.3* | 1.3* | 1.40* |
| 2005 | 4.4 | 21.3* | 67.1* | 105.0* | 62.8* | 13.3* | 1.3* | 1.38* |
| 2007 | 4.0* | 20.3* | 67.4* | 105.0* | 62.8* | 13.3* | 1.3* | 1.37* |
| 2009 | 3.7* | 19.2* | 67.4* | 105.0* | 62.8* | 13.3* | 1.3* | 1.36* |
| 2011 | 3.4* | 18.2* | 67.4* | 105.0* | 62.8* | 13.3* | 1.3* | 1.36* |
| 2013 | 3.1* | 18.2* | 67.4* | 105.0* | 62.8* | 13.3* | 1.3* | 1.36* |
| 2015+ | 2.8* | 18.2* | 67.4* | 105.0* | 62.8* | 13.3* | 1.3* | 1.35* |
Table 15 Footnotes
| ||||||||
Table 16 below shows the assumed fertility rates of each age group and the resulting assumed total fertility rates by calendar year, while Chart 2 shows the historical and projected total and cohort fertility rates for Canada.
| Year | 15-19 | 20-24 | 25-29 | 30-34 | 35-39 | 40-44 | 45-49 | Total |
|---|---|---|---|---|---|---|---|---|
| 2025 | 3.8 | 22.4 | 65.0 | 95.8 | 56.6 | 12.5 | 1.0 | 1.29 |
| 2026 | 3.7 | 21.8 | 65.4 | 97.2 | 57.6 | 12.6 | 1.0 | 1.30 |
| 2027 | 3.5 | 21.3 | 65.7 | 98.6 | 58.6 | 12.7 | 1.1 | 1.31 |
| 2028 | 3.4 | 20.8 | 66.0 | 100.1 | 59.6 | 12.8 | 1.1 | 1.32 |
| 2029 | 3.2 | 20.3 | 66.3 | 101.1 | 60.2 | 12.9 | 1.1 | 1.33 |
| 2030 | 3.1 | 19.8 | 66.5 | 102.0 | 60.9 | 13.0 | 1.2 | 1.33 |
| 2031 | 2.9 | 19.2 | 66.8 | 103.0 | 61.5 | 13.1 | 1.2 | 1.34 |
| 2032 | 2.8 | 18.7 | 67.1 | 104.0 | 62.1 | 13.2 | 1.2 | 1.35 |
| 2033+ | 2.6 | 18.2 | 67.4 | 105.0 | 62.8 | 13.3 | 1.3 | 1.35 |
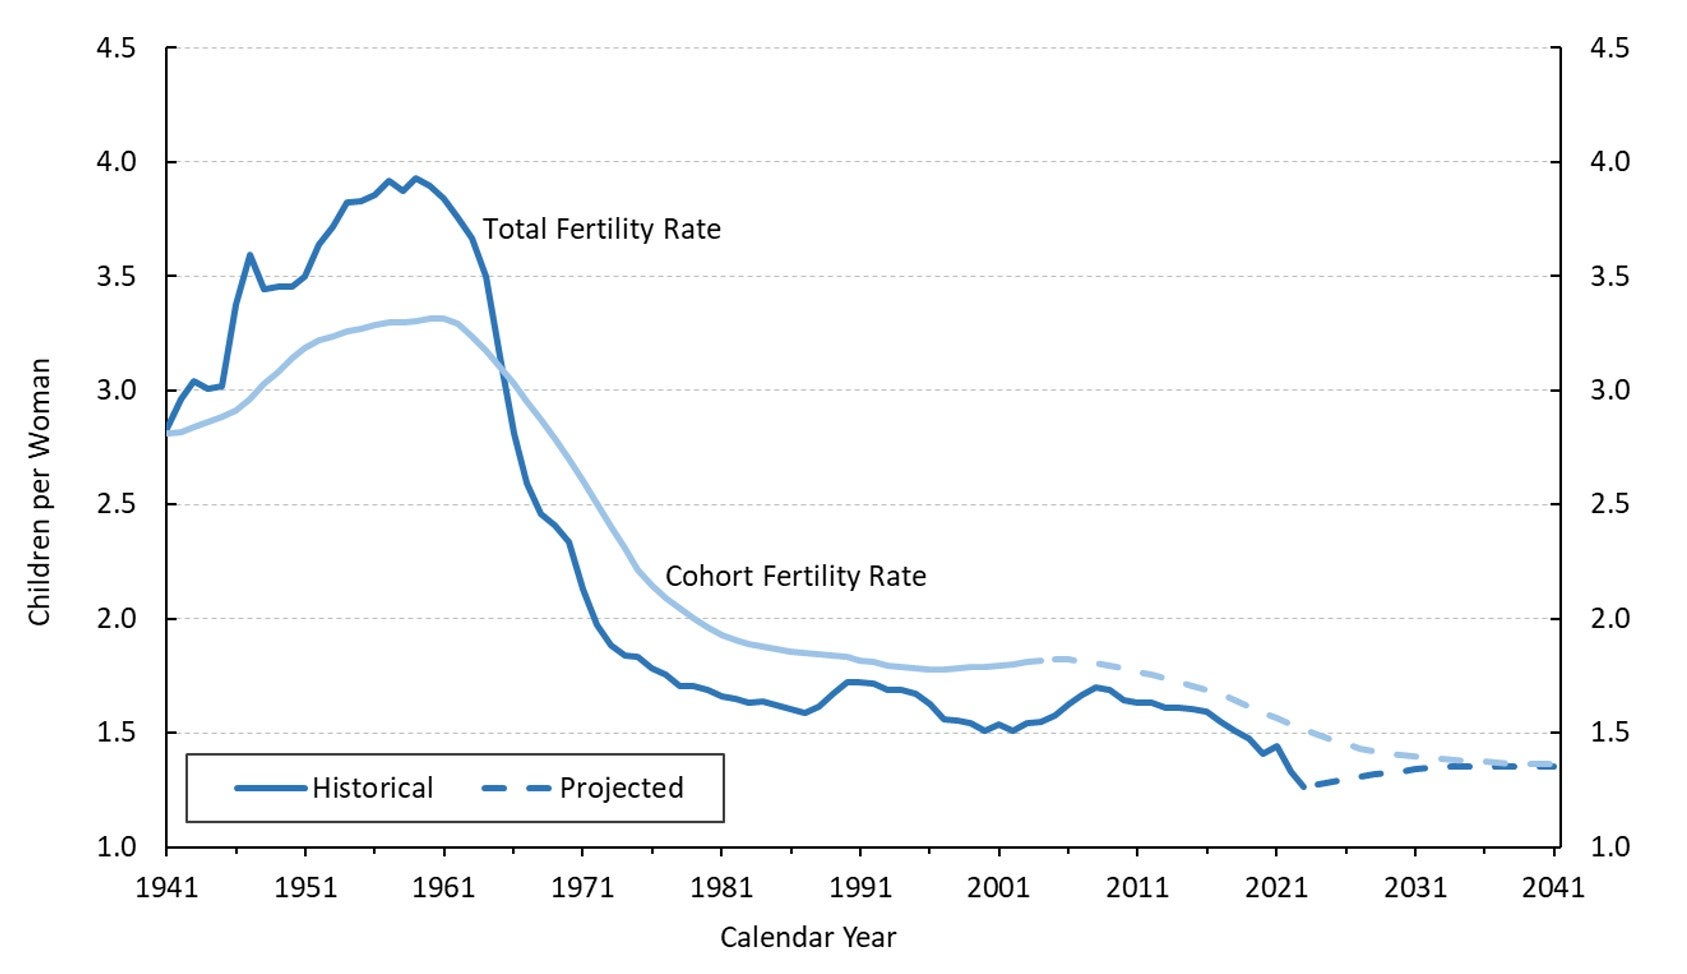
Chart 2 - Text version
| Calendar Year | Total Fertility Rates Historical | Cohort turned 30 in | Cohort Fertility Rates Historical |
|---|---|---|---|
| 1941 | 2,831 | 1941 | 2,808 |
| 1942 | 2,962 | 1942 | 2,816 |
| 1943 | 3,040 | 1943 | 2,839 |
| 1944 | 3,008 | 1944 | 2,864 |
| 1945 | 3,017 | 1945 | 2,883 |
| 1946 | 3,373 | 1946 | 2,911 |
| 1947 | 3,594 | 1947 | 2,963 |
| 1948 | 3,440 | 1948 | 3,026 |
| 1949 | 3,455 | 1949 | 3,080 |
| 1950 | 3,451 | 1950 | 3,140 |
| 1951 | 3,498 | 1951 | 3,186 |
| 1952 | 3,637 | 1952 | 3,216 |
| 1953 | 3,715 | 1953 | 3,237 |
| 1954 | 3,823 | 1954 | 3,256 |
| 1955 | 3,826 | 1955 | 3,271 |
| 1956 | 3,854 | 1956 | 3,288 |
| 1957 | 3,920 | 1957 | 3,295 |
| 1958 | 3,875 | 1958 | 3,295 |
| 1959 | 3,928 | 1959 | 3,302 |
| 1960 | 3,893 | 1960 | 3,316 |
| 1961 | 3,838 | 1961 | 3,316 |
| 1962 | 3,755 | 1962 | 3,289 |
| 1963 | 3,668 | 1963 | 3,236 |
| 1964 | 3,500 | 1964 | 3,174 |
| 1965 | 3,145 | 1965 | 3,104 |
| 1966 | 2,811 | 1966 | 3,028 |
| 1967 | 2,595 | 1967 | 2,951 |
| 1968 | 2,457 | 1968 | 2,873 |
| 1969 | 2,409 | 1969 | 2,791 |
| 1970 | 2,336 | 1970 | 2,699 |
| 1971 | 2,130 | 1971 | 2,606 |
| 1972 | 1,971 | 1972 | 2,505 |
| 1973 | 1,883 | 1973 | 2,403 |
| 1974 | 1,837 | 1974 | 2,305 |
| 1975 | 1,833 | 1975 | 2,214 |
| 1976 | 1,783 | 1976 | 2,147 |
| 1977 | 1,756 | 1977 | 2,093 |
| 1978 | 1,706 | 1978 | 2,043 |
| 1979 | 1,706 | 1979 | 1,998 |
| 1980 | 1,686 | 1980 | 1,959 |
| 1981 | 1,658 | 1981 | 1,927 |
| 1982 | 1,646 | 1982 | 1,904 |
| 1983 | 1,634 | 1983 | 1,888 |
| 1984 | 1,637 | 1984 | 1,877 |
| 1985 | 1,621 | 1985 | 1,867 |
| 1986 | 1,603 | 1986 | 1,857 |
| 1987 | 1,587 | 1987 | 1,850 |
| 1988 | 1,615 | 1988 | 1,845 |
| 1989 | 1,668 | 1989 | 1,840 |
| 1990 | 1,721 | 1990 | 1,830 |
| 1991 | 1,721 | 1991 | 1,818 |
| 1992 | 1,714 | 1992 | 1,808 |
| 1993 | 1,688 | 1993 | 1,796 |
| 1994 | 1,690 | 1994 | 1,786 |
| 1995 | 1,673 | 1995 | 1,782 |
| 1996 | 1,628 | 1996 | 1,777 |
| 1997 | 1,561 | 1997 | 1,779 |
| 1998 | 1,552 | 1998 | 1,781 |
| 1999 | 1,541 | 1999 | 1,786 |
| 2000 | 1,511 | 2000 | 1,788 |
| 2001 | 1,537 | 2001 | 1,794 |
| 2002 | 1,511 | 2002 | 1,800 |
| 2003 | 1,541 | 2003 | 1,808 |
| 2004 | 1,551 | 2004 | 1,818 |
| 2005 | 1,576 | 2005 | no data - |
| 2006 | 1,626 | 2006 | no data - |
| 2007 | 1,668 | 2007 | no data - |
| 2008 | 1,701 | 2008 | no data - |
| 2009 | 1,690 | 2009 | no data - |
| 2010 | 1,645 | 2010 | no data - |
| 2011 | 1,630 | 2011 | no data - |
| 2012 | 1,632 | 2012 | no data - |
| 2013 | 1,609 | 2013 | no data - |
| 2014 | 1,612 | 2014 | no data - |
| 2015 | 1,603 | 2015 | no data - |
| 2016 | 1,594 | 2016 | no data - |
| 2017 | 1,550 | 2017 | no data - |
| 2018 | 1,510 | 2018 | no data - |
| 2019 | 1,477 | 2019 | no data - |
| 2020 | 1,411 | 2020 | no data - |
| 2021 | 1,440 | 2021 | no data - |
| 2022 | 1,329 | 2022 | no data - |
| 2023 | 1,263 | 2023 | no data - |
| Calendar Year | Total Fertility Rates Projected | Cohort turned 30 in | Cohort Fertility Rates Projected |
|---|---|---|---|
| 2005 | no data - | 2005 | 1,822 |
| 2006 | no data - | 2006 | 1,820 |
| 2007 | no data - | 2007 | 1,812 |
| 2008 | no data - | 2008 | 1,805 |
| 2009 | no data - | 2009 | 1,793 |
| 2010 | no data - | 2010 | 1,780 |
| 2011 | no data - | 2011 | 1,765 |
| 2012 | no data - | 2012 | 1,754 |
| 2013 | no data - | 2013 | 1,740 |
| 2014 | no data - | 2014 | 1,723 |
| 2015 | no data - | 2015 | 1,705 |
| 2016 | no data - | 2016 | 1,687 |
| 2017 | no data - | 2017 | 1,670 |
| 2018 | no data - | 2018 | 1,645 |
| 2019 | no data - | 2019 | 1,616 |
| 2020 | no data - | 2020 | 1,588 |
| 2021 | no data - | 2021 | 1,564 |
| 2022 | no data - | 2022 | 1,536 |
| 2023 | no data - | 2023 | 1,512 |
| 2024 | 1,274 | 2024 | 1,491 |
| 2025 | 1,285 | 2025 | 1,470 |
| 2026 | 1,296 | 2026 | 1,451 |
| 2027 | 1,307 | 2027 | 1,430 |
| 2028 | 1,319 | 2028 | 1,417 |
| 2029 | 1,326 | 2029 | 1,409 |
| 2030 | 1,332 | 2030 | 1,401 |
| 2031 | 1,339 | 2031 | 1,394 |
| 2032 | 1,346 | 2032 | 1,389 |
| 2033 | 1,353 | 2033 | 1,384 |
| 2034 | 1,353 | 2034 | 1,380 |
| 2035 | 1,353 | 2035 | 1,376 |
| 2036 | 1,353 | 2036 | 1,373 |
| 2037 | 1,353 | 2037 | 1,369 |
| 2038 | 1,353 | 2038 | 1,366 |
| 2039 | 1,353 | 2039 | 1,363 |
| 2040 | 1,353 | 2040 | 1,363 |
| 2041 | 1,353 | 2041 | 1,363 |
Chart 2 Footnotes
- Chart 2 Footnote 1
Cohort fertility rates are based on the age of a woman being 30 in a given calendar year. For instance, the cohort fertility rate for the year 2023 pertains to women born in 1993.
Finally, in accordance with the average experience over the last 10, 20, and 25 years, the assumed ratio of male to female newborns is 1.053, which is the same as for the 18th OAS Program Actuarial Report.
B.3.3 Mortality
Although Canada Life Tables (CLT) for years 2020 to 2023 from Statistics Canada were available in December 2024, they were excluded for purposes of setting long-term mortality rates. Mortality tables for these years reflect significant mortality increases related to COVID-19 and opioid-related deaths, which are assumed to be temporary. For reference, year 2023 life expectancies at birth (without any assumed future mortality improvements) were lower than those in 2019 by 0.6 of a year for males and 0.4 of a year for females.
Long-term future mortality rates are therefore determined by applying assumed mortality improvement rates to Statistics Canada's 2019 CLT. According to the updated 2019 CLT released in December 2024 by Statistics Canada, life expectancies at birth in 2019 without any assumed future improvements in mortality for males and females in Canada were 80.1 and 84.3 years, respectively, compared to 80.3 and 84.4 years under the 18th OAS Program Actuarial Report. At age 65 in 2019, life expectancies for males and females, respectively, were 19.5 and 22.3 years according to Statistics Canada, compared to 19.6 and 22.4 years under the 18th OAS Program Actuarial ReportFootnote 2.
The average annual mortality improvement rates experienced in Canada over the 15-year period from 2004 to 2019 by age and sex were used as the starting point for projecting annual mortality improvement rates from 2020 onward. Improvement rates by age and sex for years 2020 to 2039 were determined by cubic interpolation between:
- the 15-year average improvement rates ending in 2019; and
- the assumed ultimate improvement rates described below in respect of the period 2039 and thereafter.
For the year 2039 and thereafter for Canada, the assumed ultimate annual rates of mortality improvement vary by age only and not by sex or calendar year. The assumed ultimate mortality improvement rates are derived using a combination of backward- and forward-looking approaches. The analysis of the Canadian experience over the period from 1954 to 2019 was combined with an analysis of the possible drivers of future mortality improvements. Consideration was also given to benchmarks from peers as well as educational notes and research published by the Canadian Institute of Actuaries, including the Mortality Improvements Research paper published in April 2024. Mortality improvement rates for males at most ages are currently higher than those for females but are assumed to decrease to the same level as female rates from 2039 onward.
The ultimate mortality improvement rate for both sexes for ages 0 to 89 is set at 1.0% per year from 2039 onward for Canada. For ages above 89, the ultimate improvement rate is set to reduce from 0.6% for the age group 90-94 to 0.2% for those aged 95 and older. For comparison, under the 18th OAS Program Actuarial Report, the rate was set at 0.8%, 0.5%, and 0.2% for ages 0-89, 90-94, and 95 and older, respectively, from 2039 onward.
Once the projected mortality rates were calculated using the assumed mortality improvement rates described above, the projected mortality rates were replaced with the actual values for years 2020 to 2023 from the Statistics Canada CLT, and additional adjustments were then applied in order to reflect expected additional increases in mortality rates due to the COVID-19 pandemic as well as to account for the impact of the opioid crisis.
For the year 2024, the COVID-19 mortality adjustment factors by age group were determined using data on the number of COVID-19 deaths from both the Health Infobase of the Public Health Agency of Canada and Statistics Canada. These adjustment factors are phased out by 2026. The pandemic is therefore assumed to have a residual effect on mortality in 2024 and 2025, followed by an assumed full recovery and reversion to the projected unadjusted mortality rates for year 2026 and onward. The COVID-19 adjustment factors for 2024 and 2025 amount to overall increases in mortality rates of 1.5% and 0.5%, respectively.
Over the last decade, Canada has been faced with a significant increase in accidental drug poisoning deaths, and the COVID-19 pandemic has exacerbated the issue. Opioid overdose is a subset of accidental drug poisoning deaths. It is more prevalent in the 25 to 49 age group and among men. Since 2021, there has been a plateau in the yearly opioid-related deaths. The duration and pace of the recovery remain highly uncertain. Thus, in order to reflect the impact of the opioid crisis in the future along with its uncertainty, the mortality rates for the age group 20 to 49 are projected as interpolated rates from the year 2023 actual mortality rates to the projected unadjusted 2039 mortality rates. This reflects the assumption that, over the next decade, the opioid crisis in Canada will subside gradually due to several government initiatives to increase awareness and reduce opioid supply.
Table 17 shows the adjustment (2025), intermediate (2026 to 2038), and ultimate (2039+) assumed annual mortality rates, including all assumed effects from COVID-19 and the opioid crisis, for Canada. The mortality improvement rates shown for the period 2026 to 2038 represent the average rates over that period.
| Age | Males | Females | ||||
|---|---|---|---|---|---|---|
| 2025 | 2026-2038Table 17 Footnote 1 | 2039+ | 2025 | 2026-2038Table 17 Footnote 1 | 2039+ | |
| 0 | 1.6 | 1.1 | 1.0 | 1.7 | 1.1 | 1.0 |
| 1-19 | 2.6 | 1.5 | 1.0 | 1.8 | 1.3 | 1.0 |
| 20-49 | 1.6 | 2.4 | 1.0 | 1.8 | 2.7 | 1.0 |
| 50-64 | 1.9 | 1.2 | 1.0 | 1.8 | 1.2 | 1.0 |
| 65-74 | 2.1 | 1.3 | 1.0 | 1.7 | 1.1 | 1.0 |
| 75-84 | 2.5 | 1.3 | 1.0 | 2.1 | 1.1 | 1.0 |
| 85-89 | 2.6 | 1.3 | 1.0 | 2.4 | 1.2 | 1.0 |
| 90-94 | 2.2 | 0.9 | 0.6 | 2.1 | 0.9 | 0.6 |
| 95+ | 1.3 | 0.3 | 0.2 | 1.3 | 0.4 | 0.2 |
Table 17 Footnotes
| ||||||
The resulting projected mortality rates in Table 18 indicate a continuous decrease in mortality rates over the long term. For example, the mortality rate at age 65 for males is expected to decrease from about 10 deaths per thousand people in 2025 to 7 deaths per thousand people by 2060. The gap in mortality rates between males and females at most ages is also expected to decrease over the projection period.
| Age | Males | Females | ||||
|---|---|---|---|---|---|---|
| 2025 | 2030 | 2060 | 2025 | 2030 | 2060 | |
| 0 | 4.56 | 4.32 | 3.19 | 3.60 | 3.40 | 2.51 |
| 10 | 0.07 | 0.06 | 0.05 | 0.07 | 0.06 | 0.05 |
| 20 | 0.63 | 0.57 | 0.41 | 0.35 | 0.30 | 0.20 |
| 30 | 1.21 | 1.08 | 0.73 | 0.62 | 0.54 | 0.35 |
| 40 | 1.85 | 1.57 | 0.97 | 0.98 | 0.84 | 0.54 |
| 50 | 2.64 | 2.48 | 1.82 | 1.69 | 1.59 | 1.17 |
| 60 | 6.14 | 5.65 | 4.13 | 3.92 | 3.64 | 2.67 |
| 65 | 9.84 | 9.10 | 6.67 | 6.37 | 5.95 | 4.38 |
| 70 | 15.84 | 14.63 | 10.71 | 10.52 | 9.85 | 7.25 |
| 75 | 26.21 | 24.29 | 17.81 | 17.98 | 16.95 | 12.51 |
| 80 | 44.10 | 40.94 | 30.05 | 31.35 | 29.60 | 21.88 |
| 85 | 74.10 | 68.22 | 49.88 | 54.78 | 51.16 | 37.64 |
| 90 | 132.15 | 123.71 | 97.44 | 100.72 | 94.58 | 74.60 |
| 100 | 342.39 | 332.74 | 300.12 | 292.62 | 283.19 | 254.96 |
Chart 3 shows the historical and projected life expectancies at age 65 since 1966, based on each given year's mortality rates (i.e. without assumed future mortality improvements). Table 19 shows the projected Canadian life expectancies at various ages for the specified calendar years, also based on each given year's mortality rates (without future improvements). Table 20 is similar to Table 19, the only difference being that it takes into account the assumed mortality improvements after the specified calendar years (with future improvements).
Given the continuing trend in increased longevity, Table 20 is considered to be more realistic than Table 19. At the same time, the extended length of the projection period increases the uncertainty of the results presented in Table 20 for younger ages.
From 2025 to 2060, Canadian life expectancy at age 65 (with assumed future mortality improvements) is projected to grow from 21.6 to 24.1 years for males and from 24.1 to 26.4 years for females, as shown in Table 20.
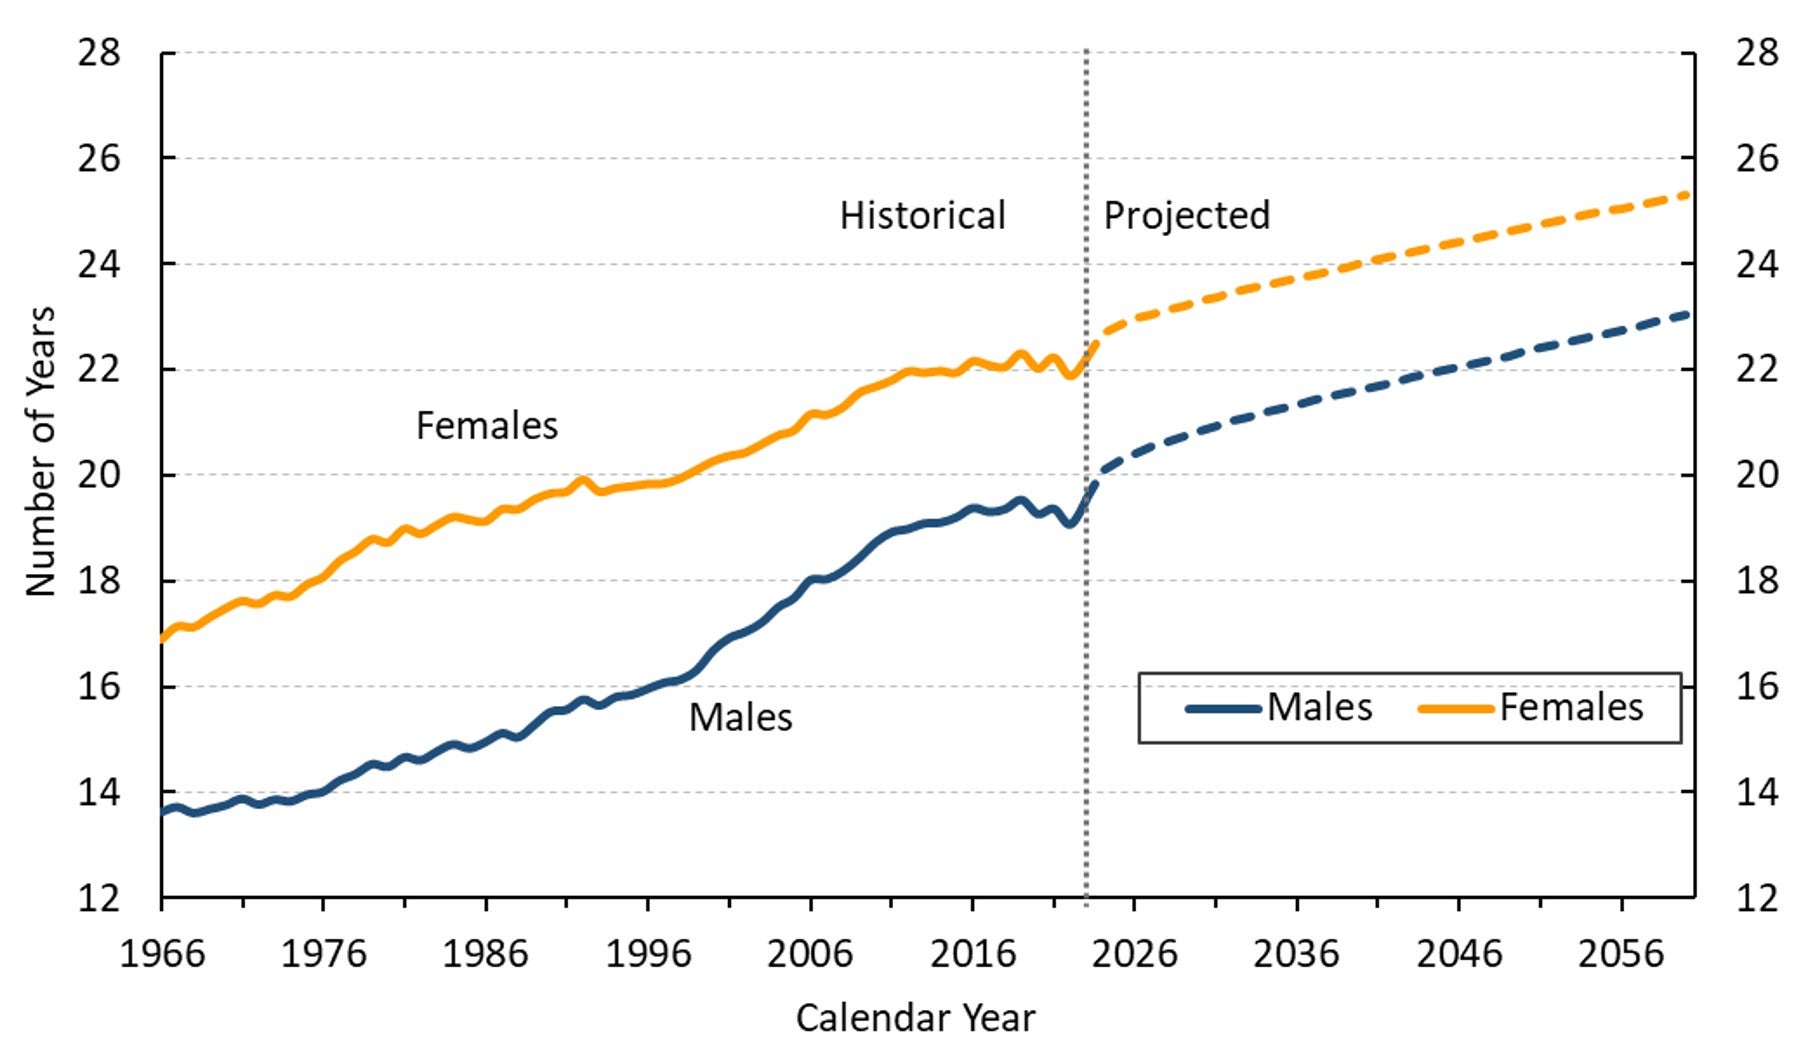
Chart 3 - Text version
| Year | Males - historical | Females - historical |
|---|---|---|
| 1966 | 13.6 | 16.9 |
| 1967 | 13.7 | 17.2 |
| 1968 | 13.6 | 17.1 |
| 1969 | 13.7 | 17.3 |
| 1970 | 13.8 | 17.5 |
| 1971 | 13.9 | 17.6 |
| 1972 | 13.8 | 17.6 |
| 1973 | 13.9 | 17.7 |
| 1974 | 13.8 | 17.7 |
| 1975 | 14.0 | 17.9 |
| 1976 | 14.0 | 18.1 |
| 1977 | 14.2 | 18.4 |
| 1978 | 14.4 | 18.6 |
| 1979 | 14.5 | 18.8 |
| 1980 | 14.5 | 18.7 |
| 1981 | 14.7 | 19.0 |
| 1982 | 14.6 | 18.9 |
| 1983 | 14.8 | 19.1 |
| 1984 | 14.9 | 19.2 |
| 1985 | 14.8 | 19.2 |
| 1986 | 15.0 | 19.1 |
| 1987 | 15.1 | 19.4 |
| 1988 | 15.0 | 19.4 |
| 1989 | 15.3 | 19.5 |
| 1990 | 15.5 | 19.7 |
| 1991 | 15.6 | 19.7 |
| 1992 | 15.8 | 19.9 |
| 1993 | 15.6 | 19.7 |
| 1994 | 15.8 | 19.8 |
| 1995 | 15.9 | 19.8 |
| 1996 | 16.0 | 19.8 |
| 1997 | 16.1 | 19.9 |
| 1998 | 16.1 | 20.0 |
| 1999 | 16.3 | 20.1 |
| 2000 | 16.7 | 20.3 |
| 2001 | 16.9 | 20.4 |
| 2002 | 17.0 | 20.4 |
| 2003 | 17.2 | 20.6 |
| 2004 | 17.5 | 20.8 |
| 2005 | 17.7 | 20.9 |
| 2006 | 18.0 | 21.2 |
| 2007 | 18.0 | 21.1 |
| 2008 | 18.2 | 21.3 |
| 2009 | 18.4 | 21.6 |
| 2010 | 18.7 | 21.7 |
| 2011 | 18.9 | 21.8 |
| 2012 | 19.0 | 22.0 |
| 2013 | 19.1 | 21.9 |
| 2014 | 19.1 | 22.0 |
| 2015 | 19.2 | 21.9 |
| 2016 | 19.4 | 22.2 |
| 2017 | 19.3 | 22.1 |
| 2018 | 19.4 | 22.1 |
| 2019 | 19.5 | 22.3 |
| 2020 | 19.3 | 22.0 |
| 2021 | 19.4 | 22.2 |
| 2022 | 19.1 | 21.9 |
| 2023 | 19.5 | 22.2 |
| Year | Males - projected | Females - projected |
|---|---|---|
| 2023 | 19.5 | 22.2 |
| 2024 | 20.1 | 22.7 |
| 2025 | 20.3 | 22.8 |
| 2026 | 20.4 | 23.0 |
| 2027 | 20.5 | 23.0 |
| 2028 | 20.6 | 23.1 |
| 2029 | 20.7 | 23.2 |
| 2030 | 20.8 | 23.3 |
| 2031 | 20.9 | 23.4 |
| 2032 | 21.0 | 23.4 |
| 2033 | 21.1 | 23.5 |
| 2034 | 21.2 | 23.6 |
| 2035 | 21.3 | 23.7 |
| 2036 | 21.3 | 23.7 |
| 2037 | 21.4 | 23.8 |
| 2038 | 21.5 | 23.9 |
| 2039 | 21.6 | 23.9 |
| 2040 | 21.6 | 24.0 |
| 2041 | 21.7 | 24.1 |
| 2042 | 21.8 | 24.1 |
| 2043 | 21.8 | 24.2 |
| 2044 | 21.9 | 24.3 |
| 2045 | 22.0 | 24.3 |
| 2046 | 22.1 | 24.4 |
| 2047 | 22.1 | 24.5 |
| 2048 | 22.2 | 24.5 |
| 2049 | 22.3 | 24.6 |
| 2050 | 22.3 | 24.7 |
| 2051 | 22.4 | 24.7 |
| 2052 | 22.5 | 24.8 |
| 2053 | 22.5 | 24.9 |
| 2054 | 22.6 | 24.9 |
| 2055 | 22.7 | 25.0 |
| 2056 | 22.8 | 25.1 |
| 2057 | 22.8 | 25.1 |
| 2058 | 22.9 | 25.2 |
| 2059 | 23.0 | 25.2 |
| 2060 | 23.0 | 25.3 |
Chart 3 Footnotes
- Chart 3 Footnote 1
These are calendar year life expectancies based on the mortality rates of the given attained year.
| Age | Males | Females | ||||
|---|---|---|---|---|---|---|
| 2025 | 2030 | 2060 | 2025 | 2030 | 2060 | |
| 0 | 80.7 | 81.6 | 84.8 | 84.8 | 85.5 | 88.2 |
| 10 | 71.1 | 72.0 | 75.1 | 75.1 | 75.8 | 78.5 |
| 20 | 61.2 | 62.1 | 65.3 | 65.3 | 65.9 | 68.6 |
| 30 | 51.7 | 52.6 | 55.6 | 55.5 | 56.2 | 58.7 |
| 40 | 42.4 | 43.2 | 46.0 | 45.9 | 46.5 | 48.9 |
| 50 | 33.3 | 34.0 | 36.5 | 36.5 | 37.0 | 39.3 |
| 60 | 24.4 | 25.1 | 27.4 | 27.2 | 27.7 | 29.9 |
| 65 | 20.3 | 20.8 | 23.0 | 22.8 | 23.3 | 25.3 |
| 70 | 16.4 | 16.9 | 18.9 | 18.6 | 19.1 | 20.9 |
| 75 | 12.8 | 13.2 | 15.0 | 14.7 | 15.1 | 16.8 |
| 80 | 9.6 | 10.0 | 11.5 | 11.2 | 11.5 | 13.0 |
| 85 | 6.9 | 7.2 | 8.3 | 8.1 | 8.4 | 9.5 |
| 90 | 4.7 | 4.9 | 5.6 | 5.6 | 5.8 | 6.5 |
| 100 | 2.2 | 2.2 | 2.4 | 2.5 | 2.6 | 2.8 |
Table 19 Footnotes
| ||||||
| Age | Males | Females | ||||
|---|---|---|---|---|---|---|
| 2025 | 2030 | 2060 | 2025 | 2030 | 2060 | |
| 0 | 87.8 | 88.2 | 90.7 | 91.0 | 91.4 | 93.4 |
| 10 | 77.4 | 77.8 | 80.3 | 80.7 | 81.1 | 83.1 |
| 20 | 66.6 | 67.1 | 69.6 | 70.0 | 70.4 | 72.5 |
| 30 | 56.1 | 56.6 | 59.2 | 59.5 | 59.9 | 62.1 |
| 40 | 45.8 | 46.3 | 48.8 | 49.0 | 49.4 | 51.6 |
| 50 | 35.8 | 36.2 | 38.6 | 38.7 | 39.1 | 41.3 |
| 60 | 26.1 | 26.5 | 28.8 | 28.8 | 29.2 | 31.2 |
| 65 | 21.6 | 22.0 | 24.1 | 24.1 | 24.4 | 26.4 |
| 70 | 17.3 | 17.7 | 19.6 | 19.6 | 19.9 | 21.7 |
| 75 | 13.5 | 13.8 | 15.5 | 15.4 | 15.7 | 17.3 |
| 80 | 10.0 | 10.3 | 11.8 | 11.7 | 11.9 | 13.3 |
| 85 | 7.1 | 7.4 | 8.5 | 8.4 | 8.6 | 9.7 |
| 90 | 4.8 | 4.9 | 5.6 | 5.7 | 5.9 | 6.6 |
| 100 | 2.2 | 2.2 | 2.4 | 2.5 | 2.6 | 2.8 |
Table 20 Footnotes
| ||||||
B.3.4 Net migration
Net migration refers to the number of immigrants less the number of net emigrants (i.e. the number of emigrants less the number of returning Canadians) plus the net increase in the number of NPR. Net migration is generally recognized as being a volatile component of population growth since it is subject to a variety of demographic, economic, social, and political factors. In more recent years, it has been even more volatile.
The level of net migration for Canada as a percentage of the population from 2000 to 2015 has varied between 0.5% and 0.8%. In 2016, net migration began accelerating, surpassing 0.8% in part due to the introduction of the Express Entry system by the Government of Canada. By 2019, net migration reached 1.19% of the population. Since then, net migration has been more volatile. In 2020 and 2021, there was a significant decrease in net migration as a percentage of the population, with the rate dropping to 0.86% and 0.39%, respectively in 2020 and 2021. The COVID-19 pandemic led to border closures making travel between countries difficult, which negatively impacted migration. In 2022, 2023, and 2024, net migration increased to historically high levels of 1.68%, 2.83%, and 2.88% of the population, respectively. This was due in particular to the removal of various pandemic-related safety measures, such as Canadian borders fully reopening in October 2022, along with efforts to fill job vacancies in key sectors of the labour market by the admittance of a large number of NPR.
The level of NPR as a percentage of the population has increased steadily but remained considerably below 5% for the years prior to the COVID-19 pandemic. Since 2021, the number of international students and temporary workers with permits under the International Mobility Program has grown substantially. They represent the two largest groups within NPR, accounting for more than three quarters of NPR in each of the past 10 years. By the end of 2024, the number of NPR reached unprecedented levels, representing 7.3% of the population. By contrast, based on the 20-year average ending in 2024, NPR represented 2.7% of the population.
To select the assumptions regarding the short-term and ultimate net migration rates, the components of net migration were analyzed separately by considering trends in the historical data as well as qualitative factors that could influence future trends. Consideration was also given to the federal government's short-term immigration targets and to long-term perspectives of various experts regarding levels of future immigration and non-permanent residents.
In the 2024 Annual Report to Parliament on Immigration, the Government of Canada released details on its Immigration Levels Plan for 2025 to 2027. The target numbers of new immigrants are set at 395,000 in 2025, 380,000 in 2026, and 365,000 in 2027. Also, the government announced, for the first time ever, short-term targets for the level of NPR, specifically: NPR inflows subject to targets set for students and workers to achieve an NPR level (as a % of the population) of 5.0% by the end of 2026.
Considering the historical experience and the immigration plan of the government, immigration as a percentage of the population is assumed in the short term to decelerate but remain above pre-COVID-19 levels due to the continuing need to fill skill shortages in the labour market and maintain a growing population. In the long term, it is assumed that higher sustained immigration will be necessary to maintain population and economic growth, aligning with forecasts from other experts.
The immigration rate is expected to decrease from 1.12% of the population in 2024 to 0.96% in 2025, 0.92% in 2026, and 0.88% in 2027. After that, it is projected to gradually decrease to an ultimate rate of 0.82% by 2034. The ultimate rate of 0.82% corresponds to the 20-year average ending in 2024, which was selected to give some weight to generally higher levels of immigration observed since 2016 while still reflecting longer-term historical trends.
The historical net emigration rate has been relatively stable since the late 2000s. The ultimate assumption for that component is based on an 8-year average ending in 2024 considering that Statistics Canada revised its methodology for reporting emigration data in 2017. The net emigration rate is expected to decrease slightly from 0.12% of the population in 2024 to 0.11% by 2026 and remain at that level thereafter.
Regarding the assumed level of NPR, current government NPR targets are short-term, and there is limited consensus among other experts on future NPR trends. To address the higher levels and volatility of the number of NPR in recent years, a new method was developed for this report to project the number of NPR separately from the rest of the population. For this purpose, an assumption is made for each year of the projection period regarding the level of NPR as a percentage of the population. The resulting annual changes in the number of NPR can then be determined and flow through the overall net migration rate.
The NPR assumption is divided into three periods. The first period reflects government targets ending in 2027. The second period addresses demographic aging up to 2035, with the NPR level assumed to reduce but remain elevated. The third period, ending in 2050, assumes the level of NPR will return to levels that are more in line with longer-term historical averages. As such, the level of NPR as a percentage of the population is assumed to trend down linearly across these periods: from 7.3% observed in 2024, to 5% in 2026, 4.0% in 2035, and then to an ultimate rate of 2.5% in 2050, remaining at that level thereafter. The ultimate rate of 2.5% was selected to give some weight to recent higher levels of NPR, while still reflecting longer-term historical trends.
Based on the foregoing, the actual net migration rate in 2024 of 2.88% of the Canadian population is assumed to decrease to -0.34% in 2025 and -0.29% in 2026, and is then assumed to increase to 0.82% in 2027. Thereafter, the net migration rate is assumed to gradually transition to an ultimate level of 0.72% of the population in 2051 (as shown in Chart 4).
Although the net migration rate represents the combined effect of all migration components, the largest fluctuations in the early projection years shown in Chart 4 are due to the Government of Canada's short-term targets and the assumed changes in net migration components as percentages of the population. Thereafter, the assumed changes in the immigration rate and NPR levels result in a decrease in the net migration rate until 2050, after which the net migration rate stabilizes at 0.72%.
The distributions of immigrants, net emigrants, and NPR by age and sex used for the demographic projections are averaged over the historical 10-year period from 2010 to 2019 due to the significant volatility in more recent years.
Chart 4 shows the net migration experience since 1972 and the projected rates starting in 2025.
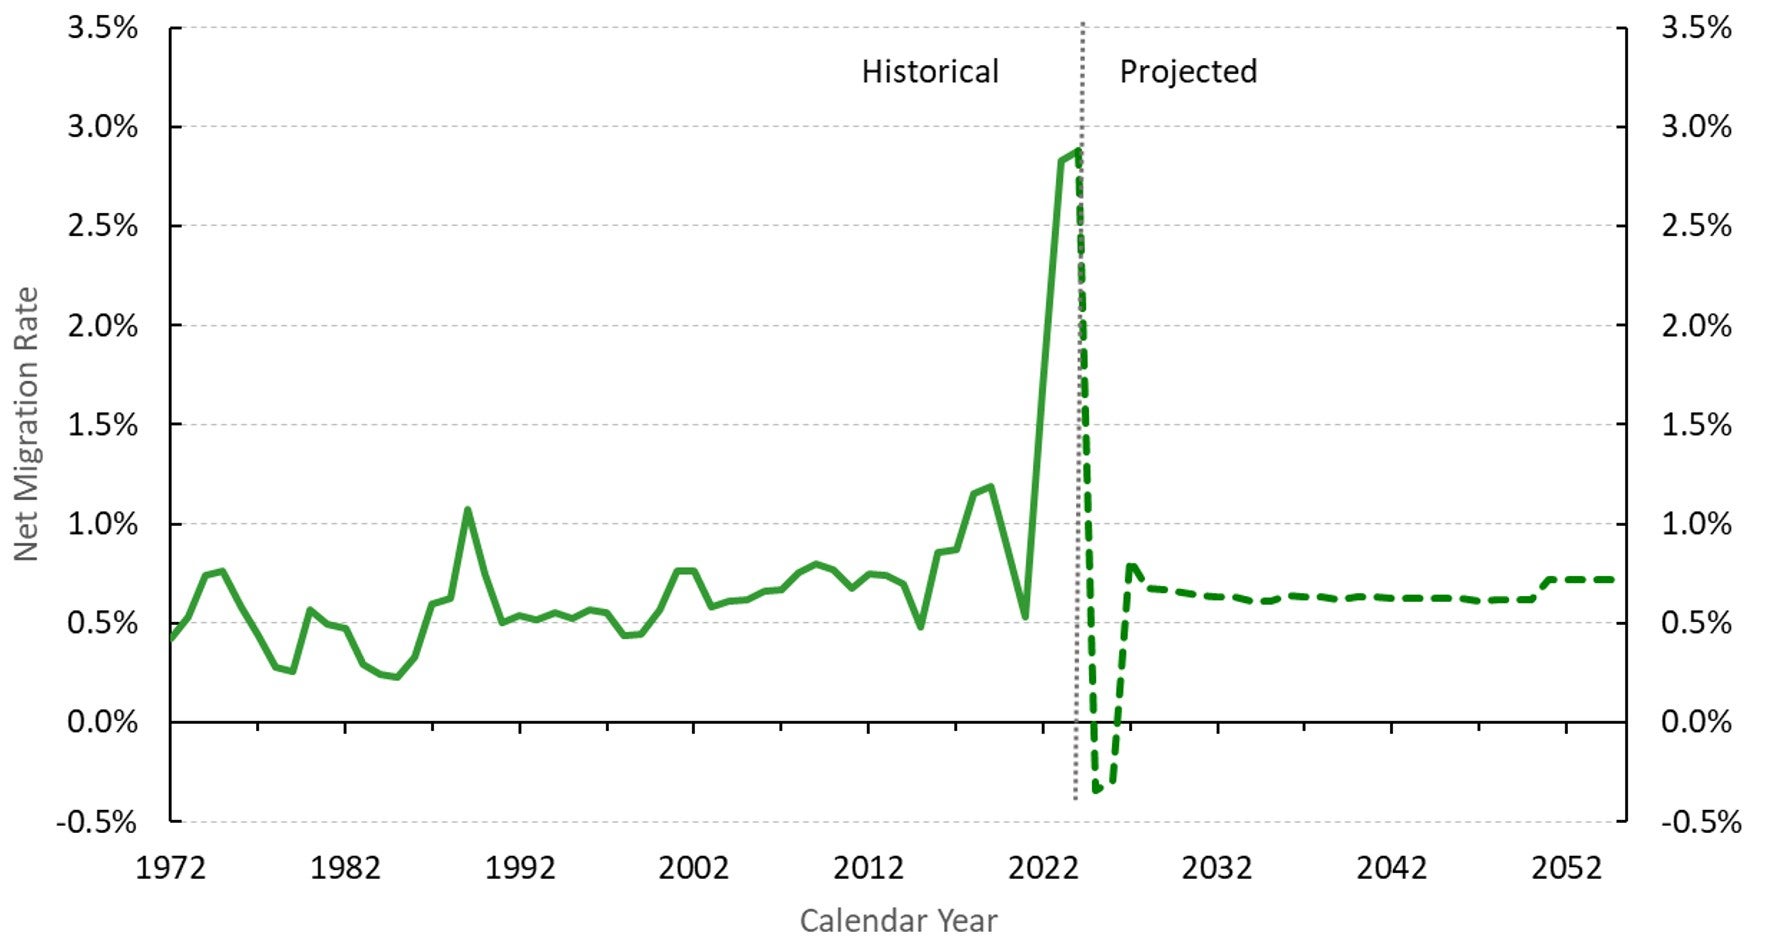
Chart 4 - Text version
| Year | Historical |
|---|---|
| 1972 | 0.42% |
| 1973 | 0.53% |
| 1974 | 0.74% |
| 1975 | 0.76% |
| 1976 | 0.58% |
| 1977 | 0.44% |
| 1978 | 0.28% |
| 1979 | 0.25% |
| 1980 | 0.56% |
| 1981 | 0.49% |
| 1982 | 0.47% |
| 1983 | 0.29% |
| 1984 | 0.24% |
| 1985 | 0.23% |
| 1986 | 0.33% |
| 1987 | 0.60% |
| 1988 | 0.63% |
| 1989 | 1.07% |
| 1990 | 0.75% |
| 1991 | 0.50% |
| 1992 | 0.54% |
| 1993 | 0.51% |
| 1994 | 0.55% |
| 1995 | 0.52% |
| 1996 | 0.57% |
| 1997 | 0.55% |
| 1998 | 0.44% |
| 1999 | 0.45% |
| 2000 | 0.57% |
| 2001 | 0.76% |
| 2002 | 0.76% |
| 2003 | 0.58% |
| 2004 | 0.61% |
| 2005 | 0.62% |
| 2006 | 0.66% |
| 2007 | 0.67% |
| 2008 | 0.75% |
| 2009 | 0.80% |
| 2010 | 0.77% |
| 2011 | 0.67% |
| 2012 | 0.75% |
| 2013 | 0.74% |
| 2014 | 0.70% |
| 2015 | 0.48% |
| 2016 | 0.86% |
| 2017 | 0.87% |
| 2018 | 1.15% |
| 2019 | 1.19% |
| 2020 | 0.86% |
| 2021 | 0.53% |
| 2022 | 1.68% |
| 2023 | 2.83% |
| 2024 | 2.88% |
| Year | Projected |
|---|---|
| 2024 | 2.88% |
| 2025 | -0.34% |
| 2026 | -0.29% |
| 2027 | 0.82% |
| 2028 | 0.67% |
| 2029 | 0.67% |
| 2030 | 0.65% |
| 2031 | 0.64% |
| 2032 | 0.63% |
| 2033 | 0.63% |
| 2034 | 0.61% |
| 2035 | 0.61% |
| 2036 | 0.64% |
| 2037 | 0.63% |
| 2038 | 0.63% |
| 2039 | 0.62% |
| 2040 | 0.63% |
| 2041 | 0.63% |
| 2042 | 0.63% |
| 2043 | 0.63% |
| 2044 | 0.63% |
| 2045 | 0.62% |
| 2046 | 0.62% |
| 2047 | 0.61% |
| 2048 | 0.62% |
| 2049 | 0.62% |
| 2050 | 0.62% |
| 2051 | 0.72% |
| 2052 | 0.72% |
| 2053 | 0.72% |
| 2054 | 0.72% |
| 2055 | 0.72% |
B.3.5 Projected population and its characteristics
The historical and projected evolution of the Canadian population age distribution since 1966 is shown in Chart 5. One can easily observe that the triangular shape of the 1960s has become more rectangular over time. This is projected to continue and indicates an aging population. The chart also reveals that the number of people aged 85 and over is expected to increase dramatically over the coming decades.
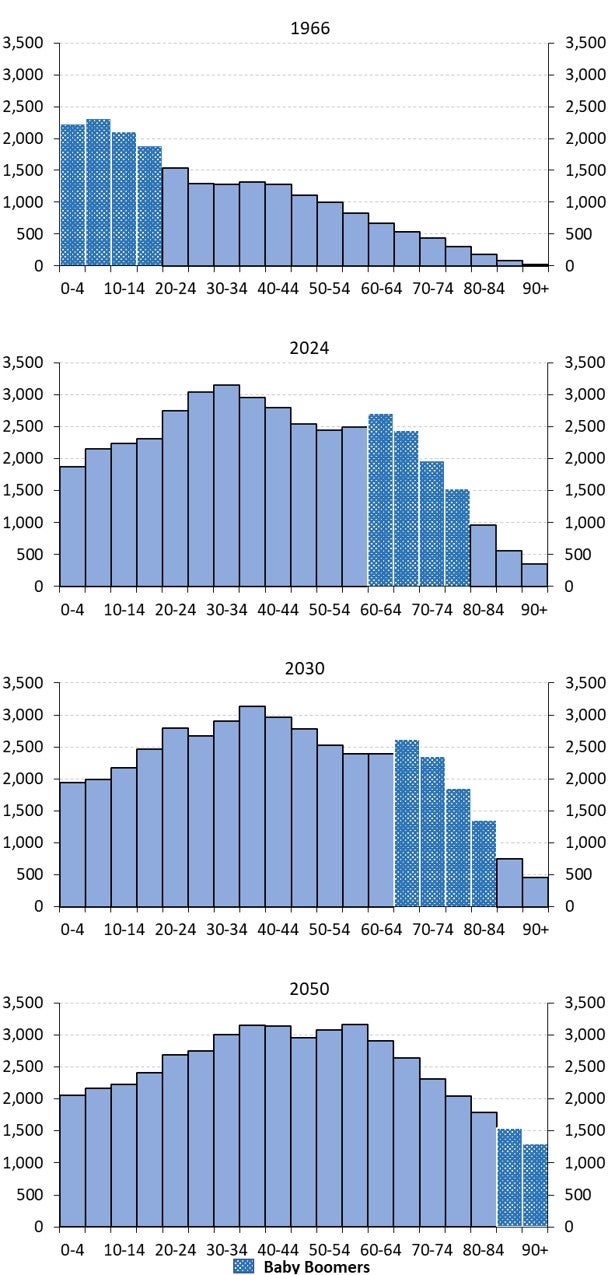
Chart 5 - Text version
| Age group | 1966 | 2024 | 2030 | 2050 |
|---|---|---|---|---|
| 0-4 | 2,226,705 | 1,873,533 | 1,939,941 | 2,060,887 |
| 5-9 | 2,318,937 | 2,155,845 | 1,992,510 | 2,167,175 |
| 10-14 | 2,112,657 | 2,235,131 | 2,178,887 | 2,230,644 |
| 15-19 | 1,887,515 | 2,315,434 | 2,459,261 | 2,411,791 |
| 20-24 | 1,540,390 | 2,744,222 | 2,790,445 | 2,680,842 |
| 25-29 | 1,294,403 | 3,042,351 | 2,673,828 | 2,751,841 |
| 30-34 | 1,282,018 | 3,152,014 | 2,898,670 | 3,001,472 |
| 35-39 | 1,313,123 | 2,955,034 | 3,129,971 | 3,153,848 |
| 40-44 | 1,282,480 | 2,800,440 | 2,964,624 | 3,138,398 |
| 45-49 | 1,104,061 | 2,541,391 | 2,777,706 | 2,953,986 |
| 50-54 | 1,002,328 | 2,446,595 | 2,520,095 | 3,072,794 |
| 55-59 | 826,590 | 2,493,717 | 2,389,170 | 3,165,750 |
| 60-64 | 671,713 | 2,712,771 | 2,393,328 | 2,904,462 |
| 65-69 | 537,983 | 2,442,561 | 2,618,853 | 2,643,682 |
| 70-74 | 432,206 | 1,972,708 | 2,355,926 | 2,310,024 |
| 75-79 | 303,746 | 1,532,797 | 1,851,947 | 2,038,139 |
| 80-84 | 179,383 | 960,179 | 1,353,080 | 1,785,566 |
| 85-89 | 77,830 | 554,453 | 748,548 | 1,548,072 |
| 90+ | 26,799 | 357,423 | 463,700 | 1,299,750 |
The population of Canada as at 1 July 2024 is 41.3 million. Table 21 presents the projected population of Canada as at 1 July for selected age groups and years. The number of people reaching age 65 is a good indicator of the number of new OAS basic pension beneficiaries coming into pay each year.
| Year | 0-17 | 18-69 | 70+ | 0-19 | 20-64 | 65+ | Total | Reaching age 65 |
|---|---|---|---|---|---|---|---|---|
| 2025 | 7,527 | 28,082 | 5,597 | 8,552 | 24,571 | 8,083 | 41,206 | 526 |
| 2026 | 7,507 | 27,811 | 5,826 | 8,526 | 24,255 | 8,362 | 41,143 | 533 |
| 2027 | 7,513 | 27,960 | 6,061 | 8,554 | 24,351 | 8,629 | 41,534 | 528 |
| 2028 | 7,516 | 28,047 | 6,300 | 8,563 | 24,400 | 8,900 | 41,863 | 540 |
| 2029 | 7,523 | 28,130 | 6,535 | 8,568 | 24,464 | 9,157 | 42,188 | 535 |
| 2030 | 7,526 | 28,201 | 6,773 | 8,571 | 24,538 | 9,392 | 42,500 | 522 |
| 2031 | 7,526 | 28,267 | 7,010 | 8,576 | 24,641 | 9,586 | 42,803 | 490 |
| 2033 | 7,521 | 28,404 | 7,456 | 8,574 | 24,910 | 9,897 | 43,381 | 464 |
| 2035 | 7,514 | 28,547 | 7,852 | 8,564 | 25,166 | 10,184 | 43,914 | 475 |
| 2040 | 7,603 | 29,170 | 8,410 | 8,599 | 25,876 | 10,708 | 45,183 | 471 |
| 2045 | 7,756 | 29,835 | 8,722 | 8,762 | 26,423 | 11,128 | 46,313 | 509 |
| 2050 | 7,861 | 30,476 | 8,982 | 8,871 | 26,823 | 11,625 | 47,319 | 552 |
| 2055 | 7,972 | 31,157 | 9,375 | 8,993 | 27,286 | 12,225 | 48,504 | 613 |
| 2060 | 8,069 | 31,713 | 9,929 | 9,115 | 27,590 | 13,006 | 49,711 | 627 |
Chart 6 shows the evolution of the population of Canada, split by age groups 0 to 19, 20 to 64, and 65 and older, from 1970 to 2060. Table 22 shows the variations in the relative proportions of various age groups for Canada throughout the projection period. The proportion of people aged 65 and over is expected to increase significantly from 19.6% of the total population in 2025 to 26.2% by 2060. The number of people aged 65 and older as a proportion of the number of people aged 20 to 64 increases over the same period, from 32.9% in 2025 to 47.1% by 2060. This proportion significantly affects the ratio of OAS program benefit expenditures to GDP.
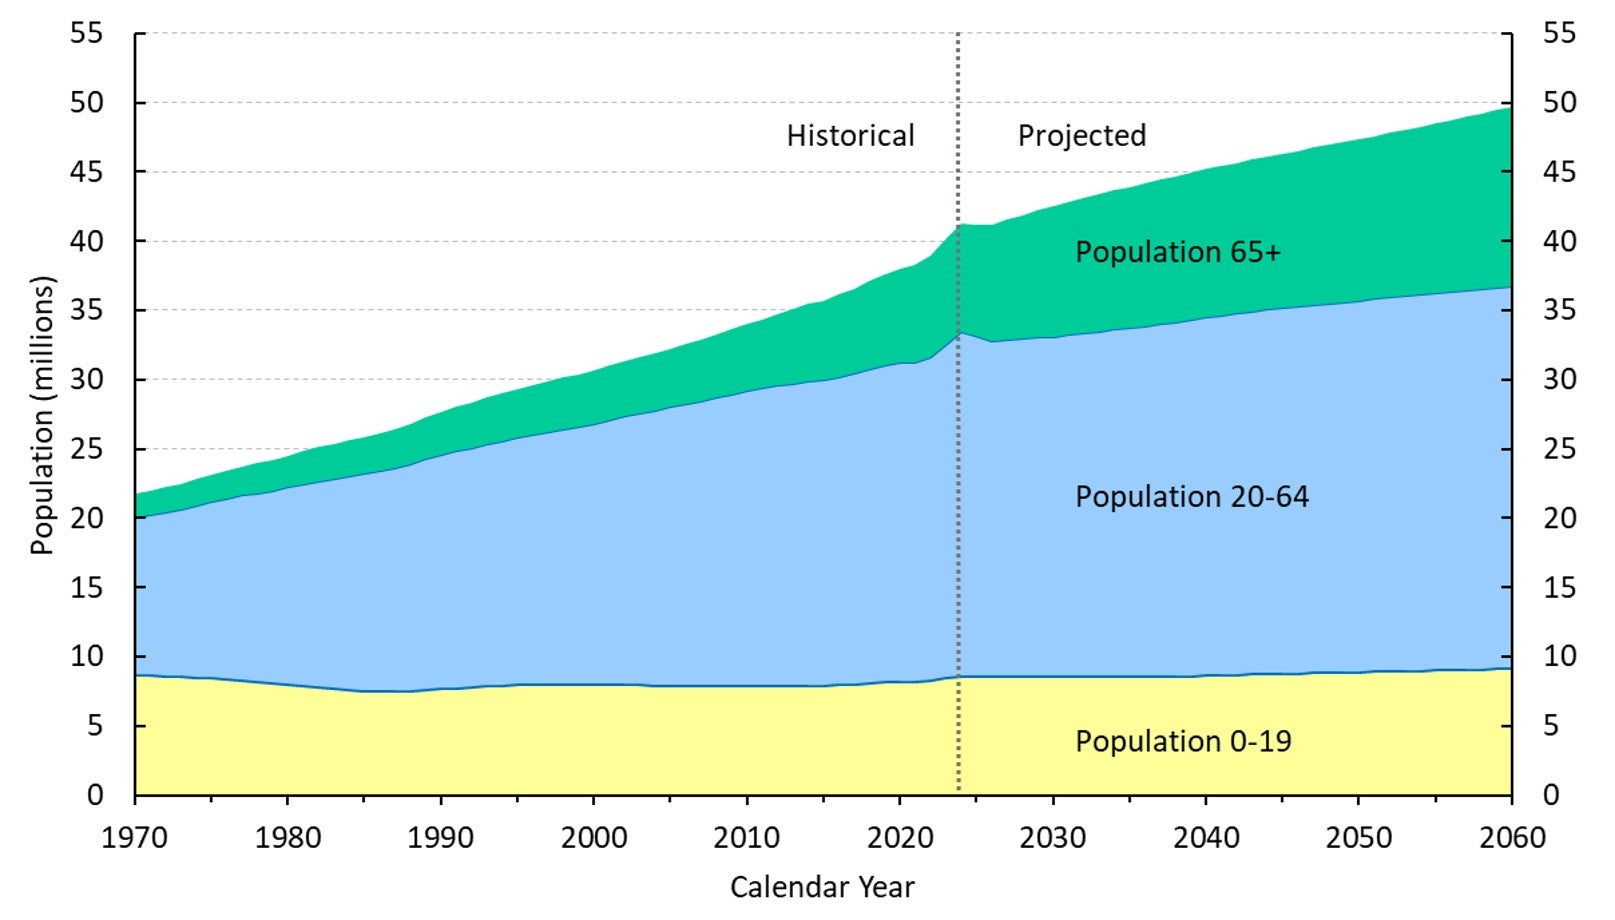
Chart 6 - Text version
| Year | Population 0-19 | Population 20-64 | Population 65+ |
|---|---|---|---|
| 1970 | 8,638,898 | 11,391,656 | 1,715,942 |
| 1971 | 8,597,358 | 11,602,264 | 1,762,410 |
| 1972 | 8,560,270 | 11,850,776 | 1,807,417 |
| 1973 | 8,511,358 | 12,125,455 | 1,854,964 |
| 1974 | 8,457,516 | 12,446,000 | 1,904,453 |
| 1975 | 8,407,717 | 12,778,483 | 1,957,075 |
| 1976 | 8,349,900 | 13,077,319 | 2,022,589 |
| 1977 | 8,273,227 | 13,363,187 | 2,089,429 |
| 1978 | 8,177,708 | 13,630,034 | 2,155,461 |
| 1979 | 8,074,962 | 13,896,479 | 2,230,103 |
| 1980 | 7,993,606 | 14,216,313 | 2,305,748 |
| 1981 | 7,902,370 | 14,540,582 | 2,376,963 |
| 1982 | 7,818,879 | 14,856,607 | 2,441,456 |
| 1983 | 7,714,177 | 15,153,392 | 2,498,882 |
| 1984 | 7,610,176 | 15,433,590 | 2,563,287 |
| 1985 | 7,520,596 | 15,673,087 | 2,648,433 |
| 1986 | 7,472,733 | 15,890,982 | 2,736,563 |
| 1987 | 7,483,331 | 16,123,976 | 2,839,294 |
| 1988 | 7,519,797 | 16,343,214 | 2,928,736 |
| 1989 | 7,594,715 | 16,654,277 | 3,027,789 |
| 1990 | 7,668,201 | 16,898,777 | 3,124,160 |
| 1991 | 7,723,080 | 17,101,852 | 3,212,488 |
| 1992 | 7,799,279 | 17,280,761 | 3,291,224 |
| 1993 | 7,858,191 | 17,460,429 | 3,366,144 |
| 1994 | 7,917,798 | 17,648,377 | 3,434,488 |
| 1995 | 7,955,693 | 17,840,138 | 3,506,480 |
| 1996 | 7,995,697 | 18,035,277 | 3,579,244 |
| 1997 | 8,005,887 | 18,245,732 | 3,654,329 |
| 1998 | 8,011,074 | 18,420,025 | 3,724,074 |
| 1999 | 7,993,938 | 18,621,859 | 3,785,489 |
| 2000 | 7,979,400 | 18,855,077 | 3,851,253 |
| 2001 | 7,966,623 | 19,132,410 | 3,921,822 |
| 2002 | 7,955,075 | 19,414,926 | 3,989,198 |
| 2003 | 7,922,457 | 19,659,631 | 4,060,373 |
| 2004 | 7,897,071 | 19,905,932 | 4,135,804 |
| 2005 | 7,875,351 | 20,153,868 | 4,213,513 |
| 2006 | 7,859,988 | 20,392,351 | 4,318,854 |
| 2007 | 7,855,627 | 20,612,312 | 4,420,947 |
| 2008 | 7,871,149 | 20,835,737 | 4,540,412 |
| 2009 | 7,881,106 | 21,080,392 | 4,668,571 |
| 2010 | 7,874,947 | 21,327,457 | 4,803,498 |
| 2011 | 7,863,549 | 21,520,517 | 4,955,155 |
| 2012 | 7,860,485 | 21,698,179 | 5,154,731 |
| 2013 | 7,864,185 | 21,864,171 | 5,352,636 |
| 2014 | 7,878,306 | 22,013,872 | 5,541,888 |
| 2015 | 7,895,568 | 22,087,223 | 5,721,707 |
| 2016 | 7,957,933 | 22,233,185 | 5,919,685 |
| 2017 | 8,009,245 | 22,410,347 | 6,125,483 |
| 2018 | 8,081,516 | 22,653,664 | 6,337,440 |
| 2019 | 8,142,894 | 22,902,342 | 6,573,259 |
| 2020 | 8,180,034 | 23,039,083 | 6,809,521 |
| 2021 | 8,149,439 | 23,044,435 | 7,045,990 |
| 2022 | 8,265,033 | 23,372,468 | 7,298,433 |
| 2023 | 8,418,210 | 24,107,547 | 7,557,727 |
| 2024 | 8,579,943 | 24,888,535 | 7,820,121 |
| Year | Population 0-19 | Population 20-64 | Population 65+ |
|---|---|---|---|
| 2025 | 8,551,960 | 24,570,944 | 8,083,474 |
| 2026 | 8,525,954 | 24,255,365 | 8,361,790 |
| 2027 | 8,554,026 | 24,350,841 | 8,629,432 |
| 2028 | 8,562,617 | 24,400,138 | 8,900,177 |
| 2029 | 8,567,658 | 24,463,542 | 9,157,162 |
| 2030 | 8,570,598 | 24,537,837 | 9,392,055 |
| 2031 | 8,575,656 | 24,641,240 | 9,585,743 |
| 2032 | 8,576,342 | 24,771,167 | 9,747,114 |
| 2033 | 8,574,084 | 24,909,994 | 9,896,607 |
| 2034 | 8,570,698 | 25,038,453 | 10,041,833 |
| 2035 | 8,563,564 | 25,166,158 | 10,183,854 |
| 2036 | 8,557,914 | 25,303,377 | 10,320,668 |
| 2037 | 8,557,728 | 25,454,118 | 10,431,301 |
| 2038 | 8,565,202 | 25,605,654 | 10,526,682 |
| 2039 | 8,578,354 | 25,746,769 | 10,615,674 |
| 2040 | 8,598,602 | 25,876,255 | 10,707,778 |
| 2041 | 8,627,760 | 25,998,379 | 10,792,855 |
| 2042 | 8,656,042 | 26,120,732 | 10,873,377 |
| 2043 | 8,699,185 | 26,224,909 | 10,952,019 |
| 2044 | 8,735,065 | 26,326,075 | 11,035,738 |
| 2045 | 8,761,660 | 26,423,481 | 11,127,601 |
| 2046 | 8,786,501 | 26,513,331 | 11,224,197 |
| 2047 | 8,811,072 | 26,595,846 | 11,319,140 |
| 2048 | 8,832,966 | 26,677,640 | 11,417,590 |
| 2049 | 8,852,456 | 26,754,622 | 11,518,657 |
| 2050 | 8,870,496 | 26,823,391 | 11,625,233 |
| 2051 | 8,895,314 | 26,930,018 | 11,732,871 |
| 2052 | 8,919,914 | 27,038,585 | 11,837,241 |
| 2053 | 8,943,971 | 27,142,268 | 11,945,892 |
| 2054 | 8,968,037 | 27,226,688 | 12,073,225 |
| 2055 | 8,992,660 | 27,286,347 | 12,224,976 |
| 2056 | 9,017,743 | 27,340,154 | 12,383,133 |
| 2057 | 9,042,729 | 27,399,978 | 12,537,011 |
| 2058 | 9,067,376 | 27,461,645 | 12,691,695 |
| 2059 | 9,091,683 | 27,526,377 | 12,846,505 |
| 2060 | 9,115,418 | 27,589,567 | 13,006,447 |
| Year | % of total populationTable 22 Footnote 1 | Age 65+ as % of age 20-64 | ||
|---|---|---|---|---|
| 0-19 | 20-64 | 65+ | ||
| 2025 | 20.8 | 59.6 | 19.6 | 32.9 |
| 2026 | 20.7 | 59.0 | 20.3 | 34.5 |
| 2027 | 20.6 | 58.6 | 20.8 | 35.4 |
| 2028 | 20.5 | 58.3 | 21.3 | 36.5 |
| 2029 | 20.3 | 58.0 | 21.7 | 37.4 |
| 2030 | 20.2 | 57.7 | 22.1 | 38.3 |
| 2031 | 20.0 | 57.6 | 22.4 | 38.9 |
| 2033 | 19.8 | 57.4 | 22.8 | 39.7 |
| 2035 | 19.5 | 57.3 | 23.2 | 40.5 |
| 2040 | 19.0 | 57.3 | 23.7 | 41.4 |
| 2045 | 18.9 | 57.1 | 24.0 | 42.1 |
| 2050 | 18.7 | 56.7 | 24.6 | 43.3 |
| 2055 | 18.5 | 56.3 | 25.2 | 44.8 |
| 2060 | 18.3 | 55.5 | 26.2 | 47.1 |
Table 22 Footnotes
| ||||
Table 23 shows the projected components of population growth, which is defined as the projected number of births plus net migrants less the projected number of deaths from 2025 to 2060. The number of births is projected to exceed deaths until 2034. Thereafter, all population growth is projected to come from migration.
The population of Canada is projected to decline by about 0.2% in each of 2025 and 2026, followed by an increase of 1.0% in 2027. Population growth is then projected to slowly decrease by about 0.5% by 2040 and remain at that level thereafter. The population of Canada is expected to reach 49.7 million by 2060.
| Year | Population 1st July | Births | Net migrants | Deaths | Change in population | Annual percentage change (%) | ||
|---|---|---|---|---|---|---|---|---|
| 20-64 | 65+ | Total | ||||||
| 2025 | 41,206 | 369 | (142) | 310 | (82) | (1.3) | 3.4 | (0.2) |
| 2026 | 41,143 | 372 | (121) | 315 | (63) | (1.3) | 3.4 | (0.2) |
| 2027 | 41,534 | 373 | 340 | 322 | 391 | 0.4 | 3.2 | 1.0 |
| 2028 | 41,863 | 377 | 281 | 329 | 329 | 0.2 | 3.1 | 0.8 |
| 2029 | 42,188 | 379 | 283 | 337 | 325 | 0.3 | 2.9 | 0.8 |
| 2030 | 42,500 | 380 | 277 | 345 | 312 | 0.3 | 2.6 | 0.7 |
| 2031 | 42,803 | 381 | 274 | 353 | 302 | 0.4 | 2.1 | 0.7 |
| 2033 | 43,381 | 383 | 273 | 369 | 286 | 0.6 | 1.5 | 0.7 |
| 2035 | 43,914 | 383 | 267 | 387 | 263 | 0.5 | 1.4 | 0.6 |
| 2040 | 45,183 | 390 | 285 | 433 | 242 | 0.5 | 0.9 | 0.5 |
| 2045 | 46,313 | 399 | 289 | 472 | 216 | 0.4 | 0.8 | 0.5 |
| 2050 | 47,319 | 400 | 293 | 500 | 193 | 0.3 | 0.9 | 0.4 |
| 2055 | 48,504 | 402 | 349 | 515 | 236 | 0.2 | 1.3 | 0.5 |
| 2060 | 49,711 | 408 | 358 | 519 | 247 | 0.2 | 1.2 | 0.5 |
Table 23 Footnotes
| ||||||||
B.4 Economic assumptions
The list of assumptions required to project the various economic indices, benefit expenditures, and cost measurement base is quite extensive. The following sections cover the main assumptions.
The economic outlook rests on the assumed evolution of the labour market, that is, labour force participation, employment, unemployment, inflation, and the increase in average employment earnings, as well as the increase in the GDP. All of these factors must be considered together and form part of an overall economic perspective.
The projected expenditures presented in this report are also expressed as cost ratios relative to the GDP. The GDP is projected using underlying assumptions of productivity, hours worked, and employment growth as determined in the Revised 32 nd CPP Actuarial Report as at 31 December 2024.
B.4.1 Labour market
Below are the main components of the labour market that are used to determine the employed population.
Total population is split between:
- Population aged 0 to 14 years old;
- Population aged 15 years old and over, which is split between:
- Active population (labour force)Section B.4.1 Footnote *
- Employed;
- Unemployed and looking for employment.
- Inactive populationSection B.4.1 Footnote *
- Active population (labour force)Section B.4.1 Footnote *
Section B.4.1 Footnotes
- Section B.4.1 Footnote *
An active person is one who is in the labour force, meaning the person is either employed or is looking for employment (unemployed). A person is said to be inactive in all other cases.
B.4.1.1 Active population
Table 24 to Table 26 provide projections of the active and employed populations and associated labour force participation, employment, and unemployment rates for Canada.
| Year | PopulationTable 24 Footnote 1 | Active population | Employed | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Males | Females | Total | Males | Females | Total | Males | Females | Total | |
| 2025 | 16,884 | 17,102 | 33,986 | 11,707 | 10,438 | 22,144 | 10,848 | 9,746 | 20,594 |
| 2026 | 16,821 | 17,108 | 33,929 | 11,597 | 10,390 | 21,988 | 10,784 | 9,731 | 20,514 |
| 2027 | 17,003 | 17,299 | 34,301 | 11,695 | 10,493 | 22,188 | 10,911 | 9,857 | 20,768 |
| 2028 | 17,152 | 17,463 | 34,615 | 11,769 | 10,579 | 22,348 | 11,017 | 9,967 | 20,985 |
| 2029 | 17,298 | 17,627 | 34,926 | 11,845 | 10,668 | 22,513 | 11,089 | 10,051 | 21,140 |
| 2030 | 17,441 | 17,787 | 35,228 | 11,921 | 10,756 | 22,677 | 11,159 | 10,134 | 21,293 |
| 2031 | 17,579 | 17,942 | 35,521 | 12,000 | 10,848 | 22,847 | 11,233 | 10,221 | 21,454 |
| 2033 | 17,835 | 18,235 | 36,070 | 12,168 | 11,041 | 23,209 | 11,391 | 10,403 | 21,793 |
| 2035 | 18,058 | 18,497 | 36,555 | 12,322 | 11,228 | 23,550 | 11,535 | 10,578 | 22,113 |
| 2040 | 18,561 | 19,092 | 37,653 | 12,611 | 11,502 | 24,113 | 11,805 | 10,837 | 22,642 |
| 2045 | 19,026 | 19,630 | 38,657 | 12,868 | 11,742 | 24,611 | 12,047 | 11,063 | 23,110 |
| 2050 | 19,438 | 20,105 | 39,542 | 13,058 | 11,927 | 24,985 | 12,224 | 11,236 | 23,461 |
| 2055 | 19,955 | 20,636 | 40,591 | 13,296 | 12,146 | 25,442 | 12,447 | 11,444 | 23,890 |
| 2060 | 20,509 | 21,186 | 41,695 | 13,530 | 12,368 | 25,898 | 12,666 | 11,652 | 24,318 |
Table 24 Footnotes
| |||||||||
| Year | Labour force participation rate | Employment rate | Unemployment rate | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Year | Males | Females | Total | Males | Females | Total | Males | Females | Total |
| 2025 | 69.3 | 61.0 | 65.2 | 64.3 | 57.0 | 60.6 | 7.3 | 6.6 | 7.0 |
| 2026 | 68.9 | 60.7 | 64.8 | 64.1 | 56.9 | 60.5 | 7.0 | 6.3 | 6.7 |
| 2027 | 68.8 | 60.7 | 64.7 | 64.2 | 57.0 | 60.5 | 6.7 | 6.1 | 6.4 |
| 2028 | 68.6 | 60.6 | 64.6 | 64.2 | 57.1 | 60.6 | 6.4 | 5.8 | 6.1 |
| 2029 | 68.5 | 60.5 | 64.5 | 64.1 | 57.0 | 60.5 | 6.4 | 5.8 | 6.1 |
| 2030 | 68.3 | 60.5 | 64.4 | 64.0 | 57.0 | 60.4 | 6.4 | 5.8 | 6.1 |
| 2031 | 68.3 | 60.5 | 64.3 | 63.9 | 57.0 | 60.4 | 6.4 | 5.8 | 6.1 |
| 2033 | 68.2 | 60.6 | 64.3 | 63.9 | 57.0 | 60.4 | 6.4 | 5.8 | 6.1 |
| 2035 | 68.2 | 60.7 | 64.4 | 63.9 | 57.2 | 60.5 | 6.4 | 5.8 | 6.1 |
| 2040 | 67.9 | 60.2 | 64.0 | 63.6 | 56.8 | 60.1 | 6.4 | 5.8 | 6.1 |
| 2045 | 67.6 | 59.8 | 63.7 | 63.3 | 56.4 | 59.8 | 6.4 | 5.8 | 6.1 |
| 2050 | 67.2 | 59.3 | 63.2 | 62.9 | 55.9 | 59.3 | 6.4 | 5.8 | 6.1 |
| 2055 | 66.6 | 58.9 | 62.7 | 62.4 | 55.5 | 58.9 | 6.4 | 5.8 | 6.1 |
| 2060 | 66.0 | 58.4 | 62.1 | 61.8 | 55.0 | 58.3 | 6.4 | 5.8 | 6.1 |
| Age group | Males | Females | ||||
|---|---|---|---|---|---|---|
| 2025 | 2035 | 2050 | 2025 | 2035 | 2050 | |
| 15-19 | 46.7 | 52.0 | 52.0 | 49.1 | 54.0 | 54.0 |
| 20-24 | 77.2 | 80.0 | 80.0 | 76.1 | 78.0 | 78.0 |
| 25-29 | 89.5 | 92.0 | 92.0 | 86.3 | 89.0 | 89.0 |
| 30-34 | 93.2 | 94.0 | 94.0 | 85.3 | 87.0 | 87.0 |
| 35-39 | 93.6 | 94.0 | 94.0 | 84.6 | 88.0 | 88.0 |
| 40-44 | 93.4 | 94.0 | 94.0 | 86.0 | 89.0 | 89.0 |
| 45-49 | 92.3 | 93.0 | 93.0 | 86.4 | 89.0 | 89.0 |
| 50-54 | 90.5 | 91.0 | 91.0 | 83.5 | 87.0 | 87.0 |
| 55-59 | 83.1 | 84.0 | 84.0 | 73.7 | 76.0 | 76.0 |
| 60-64 | 65.4 | 66.0 | 66.0 | 51.8 | 53.0 | 53.0 |
| 65-69 | 35.1 | 37.0 | 37.0 | 24.0 | 26.0 | 26.0 |
| 70 and over | 11.5 | 13.0 | 13.0 | 5.8 | 6.0 | 6.0 |
| 55-69 | 61.3 | 63.0 | 63.9 | 49.6 | 52.0 | 52.9 |
| 55 and over | 41.4 | 37.9 | 39.4 | 30.8 | 28.0 | 28.8 |
| 18-69 | 81.0 | 83.1 | 82.5 | 73.5 | 76.9 | 76.3 |
| 15 and over | 69.3 | 68.2 | 67.2 | 61.0 | 60.7 | 59.3 |
Despite the recent increases in immigration and projected long-term net migration inflow, the population is still expected to age over the projection period. Given that labour force participation rates are progressively lower for age groups over 50, the aging of the population will result in a larger proportion of the population in age groups with lower participation rates, and thus will decrease the overall participation rate throughout the projection period.
For the purpose of projecting the participation rates, the projection period has been divided into two periods: 2025 to 2035 and from 2035 onward. From 2025 to 2035, the projected participation rates are based on an analysis of historical data and expected trends for each age group and sex. From 2035 onward, the participation rates are held constant. This long-term assumption combined with a slower growth in the working-age population relative to the older age groups results in a rate of growth of approximately 0.4% for the Canadian active population (that is, the labour force) after 2035.
Some examples of the main trends that are taken into account in developing the projected participation rates are discussed below, namely, the narrowing of the male-female gap, longer working lives, and employment opportunities stemming from demographic shifts.
The overall labour force participation rates in Canada (the active population expressed as a proportion of the population aged 15 and over) from 1976 to 2024 clearly show a narrowing of the gap between male and female rates. Although the increase in participation rates of females aged 18 to 69 has slowed down since the mid-2000s, the increase was significant over the previous decades.
In 1976, overall male labour force participation (ages 15 and over) was about 78% compared to only 46% for females, which represents a gap of 32%. This gap has narrowed to 8.5% in 2024 (participation rates of 69.7% for males, 61.2% for females). It is assumed that females will continue to narrow the gap in participation rates but at a slower pace, with the gap gradually reducing to about 7.5% by 2035 (68.2% for males vs. 60.7% for females). A part of this reduction comes from an assumed sustained impact on the female labour force due to the Canada-Wide Early Learning and Child Care plan.
Although the participation rates of older age groups are lower compared to younger groups, the trend towards longer working lives is expected to continue, and as such, it is assumed that there will be further increases in participation rates for older age groups. Continued trends in increasing flexibility in work arrangements, the projected continued increases in life expectancy, and possible insufficient retirement savings are assumed to encourage older workers to delay their retirement and exit the labour force at a later age.
The participation rates for those aged 55 to 59 are assumed to increase from 83.1% to 84.0% for males and from 73.7% to 76.0% for females over the period 2025 to 2050. Over the same period, the participation rates for those aged 60 to 64 are assumed to increase from 65.4% to 66.0% and from 51.8% to 53.0% for males and females, respectively, and the participation rates for those aged 65 to 69 are assumed to increase from 35.1% to 37.0% and from 24.0% to 26.0% for males and females, respectively.
In addition to the assumed future increase in participation rates of women and older workers, as well as an assumed continued reliance on skilled immigrant workers, it is expected that there will be upward pressure on labour force participation rates as the working-age population expands at a slower pace than the older sector of the population. The participation rates for all age groups are thus expected to increase due to the attractive employment opportunities resulting from the demographic shift as the population ages.
Although the participation rates of both men and women and all age groups are expected to increase over the projection period from their 2024 levels, these increases in participation rates are not sufficient to offset the projected decrease in the overall participation rate (ages 15 and over) due to the demographic shift from population aging.
B.4.1.2 Employment (Canada)
In Canada, the annual job creation rate (i.e. the change in the number of persons employed) has been on average about 1.6% since 1976. However, this rate has varied over time. It is assumed that the job creation rate will be -0.7% in 2025, -0.4% in 2026, 1.2% in 2027, 1.0% in 2028, 0.7% in 2029, and then trend lower thereafter.
The job creation rate is associated with the variation in assumed unemployment rates as well as Canada's labour force growth rate. The unemployment rate is assumed to increase from 6.3% in 2024 to 7.0% in 2025, 6.7% in 2026, and 6.4% in 2027, before reaching its ultimate rate of 6.1% in 2028. These rates are based on recent experience and various economic forecasts.
The negative job creation rate in 2025 and 2026 coincides with the projected decrease in the Canadian population attributable to the decrease in the level of NPR as well as the initial assumed increase in unemployment. The rebound in the job creation date from 2027 onward is associated with the decreasing unemployment rate as well as the projected return to growth in the Canadian population.
Over the long term, the job creation rate is projected to be the same as the labour force growth of 0.4%. This reflects the ultimate assumption for the unemployment rate of 6.1% for year 2028 and thereafter.
Table 27 and Table 28 show the projected number of employed persons and employment rate for those aged 18 to 69, for males and females, respectively, in Canada.
| Year | Population (thousands) | Employed (thousands) | Employment rate (%) |
|---|---|---|---|
| 2025 | 14,185 | 10,349 | 73.0 |
| 2026 | 14,017 | 10,266 | 73.2 |
| 2027 | 14,092 | 10,369 | 73.6 |
| 2028 | 14,131 | 10,452 | 74.0 |
| 2029 | 14,169 | 10,504 | 74.1 |
| 2030 | 14,201 | 10,554 | 74.3 |
| 2031 | 14,230 | 10,607 | 74.5 |
| 2033 | 14,289 | 10,727 | 75.1 |
| 2035 | 14,353 | 10,840 | 75.5 |
| 2040 | 14,652 | 11,091 | 75.7 |
| 2045 | 14,974 | 11,312 | 75.5 |
| 2050 | 15,281 | 11,475 | 75.1 |
| 2055 | 15,617 | 11,670 | 74.7 |
| 2060 | 15,887 | 11,849 | 74.6 |
| Year | Population (thousands) | Employed (thousands) | Employment rate (%) |
|---|---|---|---|
| 2025 | 13,897 | 9,354 | 67.3 |
| 2026 | 13,794 | 9,329 | 67.6 |
| 2027 | 13,868 | 9,440 | 68.1 |
| 2028 | 13,916 | 9,538 | 68.5 |
| 2029 | 13,961 | 9,611 | 68.8 |
| 2030 | 14,000 | 9,684 | 69.2 |
| 2031 | 14,037 | 9,759 | 69.5 |
| 2033 | 14,115 | 9,923 | 70.3 |
| 2035 | 14,195 | 10,083 | 71.0 |
| 2040 | 14,517 | 10,335 | 71.2 |
| 2045 | 14,861 | 10,544 | 71.0 |
| 2050 | 15,196 | 10,708 | 70.5 |
| 2055 | 15,540 | 10,901 | 70.1 |
| 2060 | 15,826 | 11,089 | 70.1 |
B.4.2 Annual increase in prices (inflation rate)
The increase in prices (inflation rate) assumption is needed to determine the indexation of benefits for any given calendar year. It is also used in the determination of the annual nominal increase in average employment earnings.
Price increases, as measured by changes in the Consumer Price Index (CPI), fluctuate through time. Since the mid-1950s, the trend was generally upward through the early 1980s and then generally downward until the introduction of the inflation-control targets in the early 1990s, at which point inflation began to stabilize. The average annual increases in the CPI over the 50, 20, and 10-year periods ending in 2024 were 3.7%, 2.2%, and 2.5%, respectively.
On December 13, 2021, the Bank of Canada and the Government renewed their commitment to keep inflation between 1% and 3% with a target at the mid-point of 2% until the end of 2026Footnote 3. They further noted that the Bank will use the flexibility of the 1% to 3% control range to actively seek the maximum sustainable level of employment to an extent that is consistent with keeping medium-term inflation expectations at 2%.
Despite the mid-point target of 2%, inflation, as measured by changes in the CPI, tends to fluctuate from year to year. For instance, supply disruptions during the COVID-19 outbreak, global imbalances in supply and demand, and pent-up demand following the lifting of restrictions in 2021 and 2022, as well as the war in Ukraine that commenced in February 2022, contributed to upward pressure on prices, resulting in inflation peaking at 8.1% in June 2022. As the pandemic became more manageable, fiscal stimulus diminished, and demand and supply returned to equilibrium, the inflation rate gradually aligned with the Bank’s target. The inflation rate reached the target of 2% in August 2024. Price increase continued falling, reaching 1.8% in December 2024 partly due to the temporary GST/HST holidays on certain goods and services, which began on December 14, 2024. On an annual basis, the average inflation rate in 2024 was 2.4%. In 2025, the inflation rate had largely stabilized near the Bank’s target. Although energy prices increased in early 2026 due to the conflict in the Middle East, inflation remained within the Bank of Canada’s 1–3 per cent target range.
The inflation rate in Canada is assumed to be 2.2% in 2025, decreasing to 2.1% in 2026 and returning to the 2% target by 2027. These assumed price increases are based on short-term forecasts from various economistsFootnote 4 as well as the expectation that the Bank of Canada and federal Government will continue to renew the inflation target at 2.0% and that the Bank of Canada will be successful in keeping inflation at its mid-point target in the long term.
B.4.3 Real wage increases
Two wage measure are used in this report: the average annual earnings (AAE) and the average weekly earnings (AWE). The assumed increase in AAE is used to project the income of future beneficiaries, while the assumed increase in the AWE is used to project the increase in the YMPE from one year to the next.
For this report, increases in the real AAE and real AWE are assumed to be the same over the entire projection period, and are referred to as real wage increases. The real wage increase can be measured using the difference between the increases in the nominal average wage and the CPI. In this case, the nominal average wage is defined as the ratio of the total nominal earnings to total civilian employment in the Canadian economy as a whole.
The relationship between real wages and the labour market and overall economy is complex. In general, real wages are subject to downward pressure as the demand for workers decreases. On the other hand, one could expect upward pressure on wages if the size of the labour force fails to keep pace with a growing economy.
For this report, it is assumed that real wages will grow at an annual rate of 0.8% from the year 2025 onward. For comparison, under the 18th OAS Program Actuarial Report, real wages were assumed to increase by 0.9% per year over the long term.
The real wage increase is related to the growth in total labour productivity plus the growth of various factors, as shown in Table 29. More detail on each factor is provided below the table.
| Components | 1961-2023 average | 2000-2023 average | 2010-2023 average | Ultimate assumption |
|---|---|---|---|---|
| Labour productivity growth | 1.51% | 0.79% | 0.76% | 0.95% |
| + Compensation ratio growth | (0.09%) | (0.01%) | (0.01%) | 0.00% |
| + earnings ratio growth | (0.15%) | (0.07%) | (0.02%) | (0.05%) |
| + Average hours worked growth | (0.31%) | (0.26%) | (0.13%) | (0.10%) |
| + Price differential growth | 0.09% | 0.14% | (0.01%) | 0.00% |
| Real wage increase | 1.05% | 0.59% | 0.59% | 0.80% |
Table 29 Footnotes
| ||||
Labour productivity in the above table is defined as the ratio of the real GDP to total hours worked in the Canadian economy. As shown in Table 29, growth in labour productivity has decreased since the 1960s. However, long-term productivity is expected to increase as a result of continued technological advancements, government productivity boosting policies, and increases in capital stock investments. At the same time, a labour force reliance on immigration for future labour force growth and lower gains from increases in skills and education levels are expected to moderate productivity growth.
In addition, labour productivity could be affected by the timing and pace of Canada’s transition to a green economy. There is a substantial uncertainty surrounding the effect of this transition on the composition of Canada’s economy.
Based on the foregoing, a labour productivity growth of 0.95% is assumed for the long term.
The compensation ratio is the ratio of the total compensation received by workers to the nominal GDP, thereby reflecting the extent to which changes in productivity are shared between capital and labour. While the ratio fluctuated during the last 25 years ending in 2023, it is assumed that there will be no change in the compensation ratio over the long term.
The earnings ratio is the ratio of total workers’ earnings to total compensation. Changes in the earnings ratio reflect changes in the compensation structure offered to employees. The historical average decline in the earnings ratio of 0.15% per year from 1961 to 2023 has been primarily due to the faster growth in supplementary labour income, such as employer contributions to pension plans, health benefit plans, the CPP, and the Employment Insurance program, compared to earnings. Given that a significant portion of the historical decrease in the earnings ratio can be explained by the increase in CPP contributions resulting from the increase in the contribution rate from 3.6% in 1986 to 9.9% in 2003, the earnings ratio is not expected to decline as fast as it has in the past. However, it is expected that the cost of health programs will continue to increase in the future and exert downward pressure on the earnings ratio. Based on the foregoing, it is assumed that the long-term earnings ratio will decline by 0.05% per year.
The average hours worked is defined as the ratio of total hours worked to total employment in the Canadian economy. There was a decrease in the average hours worked between 1961 and 2023. In the future, the assumed steady increases in productivity and the higher participation rates of older workers, who generally work fewer hours, could continue to apply negative pressure on the average hours worked. It is assumed that in the long term, the average hours worked will decline by 0.10% per year.
Finally, the price differential or “labour’s terms of trade” is the ratio of the GDP deflator (defined as the ratio of nominal to real GDP) to the CPI. While the ratio has fluctuated in the past, it is assumed that the price differential will remain stable without change over the long term.
B.4.4 Gross domestic product
The GDP is a suitable basis for a comparison of costs since benefits are financed through general revenues and not on the basis of employment earnings.
The long-term GDP is projected using underlying assumptions of productivity, hours worked, and employment growth as determined in the Revised 32nd CPP Actuarial Report. More specifically, the long-term assumed annual rate of productivity growth is 0.95%, while the assumed average annual rate of change in hours worked is -0.1%. Employment growth is assumed to vary over time, reflecting the projected evolution of the labour force and the effects of demographic and population ageing assumptions. In the long run, employment growth is assumed to attain approximately 0.35% per annum, resulting in long-term real GDP growth of approximately 1.2%. The short-term GDP projection is informed by the 2025 Canadian federal budget.
In the previous report, the GDP was projected using the assumed growth in total employment earnings (as projected under the 31st CPP Actuarial Report as at 31 December 2021). The method has been refined to align GDP growth with productivity and labour input drivers, rather than using earnings growth as a proxy. Under the previous approach, the earnings-based projection implicitly incorporated earnings ratio and compensation ratio components; under the refined approach, these components are removed so that GDP growth reflects productivity, hours worked, and employment levels only. This adjustment improves consistency between the GDP projection and the economic assumptions used to determine real wage growth and labour market outcomes.
It is noteworthy that the Consumer Price Index (CPI and the GDP deflator, used to express GDP in nominal terms, are assumed to be the same for the purpose of this report.
B.5 Recipient rates and distribution by level of benefit
The recipient rate for an OAS program benefit refers to the proportion of the Canadian population that has received, receives, or is projected to receive that benefit. Since benefits are computed for age-sex cohorts as opposed to individuals, recipient rates by age, sex, type and level of benefit are required. Beneficiary data from ESDC for years 2010-2024 were used to create a table for each benefit type, consisting of the number of beneficiaries by sex, age, and six levels of benefit as a percentage of the maximum benefit (0-19%, 20-39%, 40-59%, 60-79%, 80‑99%, and 100% and over). Historical statistics provided by ESDC on a similar basis were used for the years 1983 to 2009. The highest level of benefit (100% of the maximum and over) includes those GIS beneficiaries with partial OAS pensions, who consequently see their supplement increased by the difference between the maximum OAS pension payable and the partial pension. The additional amount may result in the supplement exceeding the maximum GIS payable.
The actual recipient rates in each of the cells described above are obtained by dividing the number of beneficiaries in each cell by the relevant population of Canada. The data include benefits paid outside Canada.
B.5.1 OAS basic pension
The historical recipient rates of sex-distinct cohorts for the basic pension were studied to determine the best-estimate assumptions. The ultimate OAS basic pension recipient rates are set equal to the projected recipient rates for the cohort reaching age 65 in 2024. The ultimate recipient rates are determined as follows:
- Ages 65 to 70: average of observed rates for years 2022 to 2024, assumed for all years from 2025 onward.
- Ages 71 and over: based on historical recipient rates from years 2015 to 2024, then projected to decrease according to a linear interpolation between 2024 and the ultimate year. The ultimate year refers to the year when the cohort age 65 in 2024 reaches the given age. The ultimate rates for ages 71 to 74 are further adjusted to provide a smooth transition from age 70 to 75.
As the assumed recipient rates are based on historical experience that already includes voluntary deferrals (effective 1 July 2013), no adjustment is applied to the recipient rates for deferrals. However, voluntary deferrals are assumed in order to develop assumed distributions of the ages of pension take-up for each attained age. These distributions are used in turn to determine the assumed increase in pension applicable at an attained age from the greater effect of pension adjustment from deferral or the accumulation of additional years of residence (for partial pensions).
The assumed deferral rates are based on historical and assumed recipient rates. Table 30 presents the deferral assumptions for cohorts reaching age 65 in 2024 and thereafter, for males and females. The assumptions represent the percentages of the cohorts who defer pension take-up to a given age. This report assumes a greater percentage of the population will defer their take-up than in the previous report.
As shown in Table 30, deferrals past the age of 70 occur, for various reasons, including waiting to accumulate more years of residence for those with partial pensions or not applying for the pension due to unawareness of the benefit.
For the cohort age 65 in 2024 and thereafter, 3.6% of males and females are assumed to start receiving their OAS basic pension midyear at age 65.5.
| Age (midyear) | Males | Females |
|---|---|---|
| 65 | 3.6 | 3.6 |
| 66 | 5.7 | 5.5 |
| 67 | 3.7 | 3.1 |
| 68 | 2.8 | 2.3 |
| 69 | 2.6 | 2.1 |
| 70 | 1.9 | 1.4 |
| 71 | 0.9 | 0.5 |
| 72 | 0.8 | 0.4 |
| 73 | 0.6 | 0.5 |
| 74 | 0.3 | 0.5 |
| 75 | 0.1 | 0.3 |
| Total | 22.9 | 20.3 |
The basic pension recipient rates for cohorts reaching age 65 in 2024 and thereafter are assumed to increase from 74.6% at age 65 to 100.4% at ages 90 and over for males and from 77.6% at age 65 to 99.0% at ages 90 and over for females. OAS basic pension recipient rates include benefits paid outside Canada under international social security agreements, and as such, can exceed 100%.
The basic pension recipient rates by age and sex are further broken down by level of benefit using distributions of recipient rates by level of benefit, expressed as a percentage of the maximum benefit (based on the number of years of residence in Canada). The historical distributions by level of benefit were derived from OAS beneficiary data as at 31 December of each year over the period 2015 to 2023. The distribution by level of benefit at age 65 in 2023 is assumed to apply at age 65 for all years thereafter, and the benefit level distributions for ages 66 and above are assumed to apply for year 2024 and thereafter.
For any given cohort reaching age 65 in 2024 or after, the distributions by level of benefit for ages 66 and over are projected based on historical data that reveal that, for any given cohort, there is a significant proportion of beneficiaries coming into pay who have a small number of years of residence and thus receive partial benefits. Recent experience confirms that the proportion of recipients receiving a partial pension continues to grow, although at a lesser rate than previously projected. As such, it is assumed that as a cohort progresses in age, the proportion of beneficiaries receiving a full pension will decrease while the proportion of beneficiaries receiving a partial benefit will increase, but to a somewhat lesser extent than in the previous report.
Table 31 and Table 32 show the evolution of male and female OAS basic pension recipient rates by age, calendar year, and level of benefit. The assumed ultimate basic pension recipient rates for cohorts age 65 in 2024 and thereafter are fully reached at all ages in calendar year 2049.
| Age | Level of benefit in calendar year 2025 | Level of benefit in calendar year 2030 | Level of benefit in calendar year 2049 and after | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | Total | Partial | Full | Total | Partial | Full | Total | |
| 65 | 8.5 | 66.1 | 74.6 | 8.5 | 66.1 | 74.6 | 8.5 | 66.1 | 74.6 |
| 66 | 11.3 | 70.6 | 81.8 | 11.3 | 70.6 | 81.8 | 11.3 | 70.6 | 81.8 |
| 67 | 12.5 | 73.5 | 86.0 | 12.5 | 73.5 | 86.0 | 12.5 | 73.5 | 86.0 |
| 68 | 13.6 | 75.5 | 89.1 | 13.5 | 75.7 | 89.1 | 13.5 | 75.7 | 89.1 |
| 69 | 14.3 | 77.2 | 91.5 | 14.2 | 77.3 | 91.5 | 14.2 | 77.3 | 91.5 |
| 70 | 14.9 | 79.4 | 94.3 | 15.0 | 79.3 | 94.3 | 15.0 | 79.3 | 94.3 |
| 75 | 13.8 | 83.9 | 97.7 | 15.7 | 81.8 | 97.5 | 16.9 | 80.6 | 97.4 |
| 80 | 12.4 | 86.6 | 99.0 | 14.7 | 84.2 | 98.9 | 18.3 | 80.3 | 98.6 |
| 85 | 13.0 | 87.0 | 100.0 | 14.9 | 85.1 | 99.9 | 19.7 | 79.9 | 99.6 |
| 90+ | 14.0 | 87.0 | 101.0 | 15.8 | 85.1 | 100.9 | 22.1 | 78.3 | 100.4 |
| All Ages | 13.1 | 80.4 | 93.5 | 14.3 | 79.7 | 94.0 | 16.6 | 78.1 | 94.7 |
Table 31 Footnotes
| |||||||||
| Age | Level of benefit in calendar year 2025 | Level of benefit in calendar year 2030 | Level of benefit in calendar year 2049 and after | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | Total | Partial | Full | Total | Partial | Full | Total | |
| 65 | 9.1 | 68.5 | 77.6 | 9.1 | 68.5 | 77.6 | 9.1 | 68.5 | 77.6 |
| 66 | 10.6 | 74.3 | 84.9 | 10.6 | 74.3 | 84.9 | 10.6 | 74.3 | 84.9 |
| 67 | 13.0 | 75.6 | 88.6 | 13.0 | 75.6 | 88.6 | 13.0 | 75.6 | 88.6 |
| 68 | 14.1 | 77.0 | 91.1 | 14.0 | 77.1 | 91.1 | 14.0 | 77.1 | 91.1 |
| 69 | 14.8 | 78.4 | 93.2 | 14.8 | 78.4 | 93.2 | 14.8 | 78.4 | 93.2 |
| 70 | 15.3 | 80.1 | 95.4 | 15.5 | 79.9 | 95.4 | 15.5 | 79.9 | 95.4 |
| 75 | 13.7 | 84.5 | 98.2 | 16.0 | 82.0 | 98.0 | 17.3 | 80.5 | 97.8 |
| 80 | 12.3 | 86.7 | 99.0 | 14.8 | 84.1 | 98.8 | 18.6 | 79.9 | 98.5 |
| 85 | 13.0 | 86.5 | 99.5 | 14.9 | 84.5 | 99.4 | 20.0 | 79.0 | 99.0 |
| 90+ | 12.0 | 87.5 | 99.5 | 14.0 | 85.6 | 99.5 | 20.9 | 78.1 | 99.0 |
| All Ages | 13.2 | 81.7 | 94.9 | 14.5 | 80.6 | 95.1 | 17.2 | 78.4 | 95.6 |
Table 32 Footnotes
| |||||||||
The OAS Recovery Tax reduces the amount of the basic pension payable for high-income pensioners (see section 3 of Appendix A) through a repayment amount. The projected Recovery Tax amounts and number of beneficiaries affected by it presented in this report reflect that various factors may have an impact. These include pension income splitting, TFSA utilization, and future sources of additional income.
Statistics on the proportion of beneficiaries affected (fully or partially) by the OAS Recovery Tax were estimated for tax years 2015 to 2023 using data from ESDC and CRA.
The proportions of beneficiaries affected by the Recovery Tax in 2024 and thereafter is projected from the historical proportions by assuming that initial retirement income will increase in line with wage growth, while the Recovery Tax income limits increase in line with inflation.
Projections from the Revised 32nd CPP Actuarial Report as well as data from ESDC and CRA were used to make adjustments to the Recovery Tax projections in respect of the estimated impacts of TFSAs and the additional CPP and QPP benefits. Given the absence of experience data for the additional CPP and QPP and limited data regarding the TFSAs (introduced in 2009), the results presented in Table 33 and Table 34 should be interpreted with caution.
Table 33 presents the projected number and percentage of OAS beneficiaries affected by the Recovery Tax. The percentage of beneficiaries affected by the OAS Recovery Tax is projected to increase from 8.2% in 2026 (2.7% full and 5.5% partial) to 10.5% (3.5% full and 7.0% partial) by 2060.
| Year | Full Repayment of OAS Pension | Partial Repayment of OAS Pension | Total | ||||
|---|---|---|---|---|---|---|---|
| Number (thousands) | % All OAS beneficiaries | Number (thousands) | % All OAS beneficiaries | Number (thousands)Table 33 Footnote 1 | % All OAS beneficiaries | All OAS Beneficiaries (thousands) | |
| 2025 | 212 | 2.8 | 432 | 5.7 | 643 | 8.4 | 7,617 |
| 2026 | 213 | 2.7 | 434 | 5.5 | 646 | 8.2 | 7,884 |
| 2027 | 213 | 2.6 | 436 | 5.4 | 649 | 8.0 | 8,143 |
| 2028 | 215 | 2.6 | 438 | 5.2 | 653 | 7.8 | 8,402 |
| 2029 | 215 | 2.5 | 440 | 5.1 | 655 | 7.6 | 8,652 |
| 2030 | 216 | 2.4 | 441 | 5.0 | 656 | 7.4 | 8,884 |
| 2031 | 223 | 2.5 | 459 | 5.1 | 682 | 7.5 | 9,082 |
| 2033 | 238 | 2.5 | 492 | 5.2 | 730 | 7.8 | 9,406 |
| 2035 | 254 | 2.6 | 525 | 5.4 | 780 | 8.0 | 9,696 |
| 2040 | 293 | 2.9 | 605 | 5.9 | 898 | 8.8 | 10,223 |
| 2045 | 319 | 3.0 | 637 | 6.0 | 955 | 9.0 | 10,623 |
| 2050 | 348 | 3.1 | 680 | 6.1 | 1,028 | 9.3 | 11,081 |
| 2055 | 385 | 3.3 | 756 | 6.5 | 1,142 | 9.8 | 11,638 |
| 2060 | 434 | 3.5 | 867 | 7.0 | 1,301 | 10.5 | 12,378 |
Table 33 Footnotes
| |||||||
The impact of the OAS Recovery Tax on total benefits payable is obtained using the projected number of beneficiaries who are affected and the assumed reduction in their average benefit (100% reduction for those with a full repayment and a 31.9% reduction in benefit for those with a partial repayment). It is estimated that, in 2026, the Recovery Tax will have the effect of reducing the total amount of basic pensions payable by about $3.3 billion or 4.6%. Table 34 presents the projected repayment amounts.
| Year | Repayment for those subject to full repayments | Repayment for those subject to partial repayments | Total repayment | |||
|---|---|---|---|---|---|---|
| Amount ($ million) | % of Total OAS pensions | Amount ($ million) | % of Total OAS pensions | Amount ($ million)Table 34 Footnote 1 | % of Total OAS pensions | |
| 2025 | 1,919 | 2.9 | 1,254 | 1.9 | 3,174 | 4.8 |
| 2026 | 1,973 | 2.8 | 1,290 | 1.8 | 3,263 | 4.6 |
| 2027 | 2,024 | 2.7 | 1,326 | 1.8 | 3,349 | 4.5 |
| 2028 | 2,080 | 2.6 | 1,362 | 1.7 | 3,442 | 4.4 |
| 2029 | 2,133 | 2.6 | 1,398 | 1.7 | 3,531 | 4.3 |
| 2030 | 2,182 | 2.5 | 1,432 | 1.6 | 3,613 | 4.2 |
| 2031 | 2,310 | 2.5 | 1,516 | 1.7 | 3,826 | 4.2 |
| 2033 | 2,577 | 2.6 | 1,678 | 1.7 | 4,256 | 4.3 |
| 2035 | 2,876 | 2.7 | 1,851 | 1.7 | 4,727 | 4.5 |
| 2040 | 3,684 | 3.0 | 2,317 | 1.9 | 6,002 | 4.8 |
| 2045 | 4,445 | 3.1 | 2,786 | 2.0 | 7,231 | 5.1 |
| 2050 | 5,354 | 3.3 | 3,387 | 2.1 | 8,741 | 5.3 |
| 2055 | 6,519 | 3.4 | 4,204 | 2.2 | 10,723 | 5.6 |
| 2060 | 8,076 | 3.6 | 5,375 | 2.4 | 13,452 | 6.0 |
Table 34 Footnotes
| ||||||
B.5.2 GIS and Allowance
The annual average recipient rates for the GIS and Allowance benefits, by age, sex, type and level of benefit in 2024 are used as the starting point for determining the best-estimate assumptions.
The formulas used in the projection of the GIS and Allowance recipient rates take into account the assumption that, for each cohort of individuals who may become eligible for these benefits, the initial retirement income will consist mainly of CPP and QPP benefits (including the additional benefits) that reflect increases in line with wage growth prior to retirement. At the same time, it is assumed that the income limits for the GIS and Allowance will have increased in line with inflation prior to retirement. Together this would lead to a smaller percentage of individuals expected to become GIS or Allowance beneficiaries over the projection period. However, this decline in eligibility is partially offset by the projected effect of TFSAs over time due to the transfer of non-registered investments, and RRSP and RRIF investments toward TFSAs. In fact, TFSA-related income is excluded from the determination of GIS and Allowance benefits, which leads to an increase in both the number of GIS and Allowance beneficiaries and amount of benefits.
Table 35 to Table 38 presents the projected GIS and Allowance recipient rates for cohorts reaching the ages 60 and 65 by age, sex, type and level of benefit.
| Age | 2025 | 2030 | 2060 | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | Total | Partial | Full | Total | Partial | Full | Total | |
| 65 | 16.9 | 4.3 | 21.2 | 17.2 | 4.2 | 21.4 | 13.4 | 3.6 | 17.0 |
| 70 | 22.1 | 5.3 | 27.4 | 21.2 | 5.1 | 26.3 | 16.3 | 4.2 | 20.5 |
| 75 | 22.9 | 5.4 | 28.3 | 22.1 | 5.3 | 27.4 | 16.5 | 4.3 | 20.8 |
| 80 | 24.1 | 5.6 | 29.6 | 22.8 | 5.4 | 28.2 | 16.1 | 4.4 | 20.5 |
| 85 | 25.2 | 6.1 | 31.3 | 24.2 | 5.9 | 30.1 | 15.9 | 4.7 | 20.6 |
| 90+ | 23.4 | 5.4 | 28.8 | 22.1 | 5.2 | 27.3 | 12.9 | 4.2 | 17.1 |
| All ages | 23.0 | 5.4 | 28.5 | 22.1 | 5.3 | 27.4 | 15.7 | 4.3 | 20.0 |
Table 35 Footnotes
| |||||||||
| Age | 2025 | 2030 | 2060 | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | Total | Partial | Full | Total | Partial | Full | Total | |
| 65 | 17.7 | 4.7 | 22.5 | 18.4 | 4.9 | 23.3 | 13.7 | 4.1 | 17.8 |
| 70 | 24.8 | 6.3 | 31.2 | 24.6 | 6.4 | 31.0 | 18.6 | 5.4 | 24.0 |
| 75 | 27.5 | 6.5 | 34.0 | 27.4 | 6.6 | 34.0 | 20.5 | 5.6 | 26.1 |
| 80 | 30.9 | 7.4 | 38.2 | 30.0 | 7.4 | 37.4 | 21.8 | 6.3 | 28.1 |
| 85 | 33.2 | 8.0 | 41.2 | 32.3 | 7.9 | 40.2 | 22.2 | 6.8 | 29.0 |
| 90+ | 37.6 | 8.2 | 45.8 | 35.7 | 8.0 | 43.7 | 22.6 | 6.8 | 29.4 |
| All ages | 29.1 | 7.0 | 36.1 | 28.6 | 7.0 | 35.6 | 20.5 | 6.0 | 26.5 |
Table 36 Footnotes
| |||||||||
| Age | 2025 | 2030 | 2060 | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | Total | Partial | Full | Total | Partial | Full | Total | |
| 60 | 0.4 | no data - | 0.4 | 0.4 | no data - | 0.5 | 0.4 | no data - | 0.4 |
| 61 | 0.5 | no data - | 0.6 | 0.6 | no data - | 0.6 | 0.4 | no data - | 0.5 |
| 62 | 0.7 | no data - | 0.8 | 0.8 | no data - | 0.8 | 0.6 | no data - | 0.6 |
| 63 | 1.0 | no data - | 1.0 | 1.0 | no data - | 1.1 | 0.8 | no data - | 0.8 |
| 64 | 1.3 | 0.1 | 1.3 | 1.3 | 0.1 | 1.3 | 1.0 | 0.1 | 1.0 |
| All ages | 0.8 | no data - | 0.8 | 0.8 | no data - | 0.9 | 0.6 | no data - | 0.7 |
Table 37 Footnotes
| |||||||||
| Age | 2025 | 2030 | 2060 | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | Total | Partial | Full | Total | Partial | Full | Total | |
| 60 | 2.2 | 0.1 | 2.4 | 2.6 | 0.1 | 2.7 | 2.1 | 0.1 | 2.2 |
| 61 | 3.2 | 0.2 | 3.4 | 3.5 | 0.2 | 3.7 | 2.7 | 0.1 | 2.8 |
| 62 | 4.1 | 0.2 | 4.4 | 4.4 | 0.2 | 4.6 | 3.4 | 0.2 | 3.5 |
| 63 | 5.3 | 0.3 | 5.5 | 5.4 | 0.3 | 5.7 | 4.2 | 0.2 | 4.4 |
| 64 | 6.5 | 0.3 | 6.9 | 6.6 | 0.3 | 6.9 | 5.2 | 0.2 | 5.4 |
| All ages | 4.3 | 0.2 | 4.5 | 4.5 | 0.2 | 4.7 | 3.5 | 0.2 | 3.7 |
Table 38 Footnotes
| |||||||||
B.5.3 Maximum benefits
Table 39 shows the projected maximum monthly amounts of benefits applicable for July of the given year. The amounts presented include the GIS and Allowance top-ups.
| 1 July of year | OAS Table 39 Footnote 1 | GIS Table 39 Footnote 2 | Allowance Table 39 Footnote 2 | |||
|---|---|---|---|---|---|---|
| before age 75 | after age 74 | Single | Married | Regular | Survivor | |
| 2025 | 735 | 808 | 1,098 | 661 | 1,396 | 1,664 |
| 2026 | 751 | 826 | 1,121 | 675 | 1,426 | 1,699 |
| 2027 | 766 | 842 | 1,144 | 689 | 1,454 | 1,734 |
| 2028 | 781 | 859 | 1,167 | 702 | 1,484 | 1,769 |
| 2029 | 797 | 877 | 1,190 | 716 | 1,513 | 1,804 |
| 2030 | 813 | 894 | 1,214 | 731 | 1,544 | 1,840 |
| 2031 | 829 | 912 | 1,238 | 745 | 1,574 | 1,877 |
| 2033 | 863 | 949 | 1,288 | 775 | 1,638 | 1,953 |
| 2035 | 897 | 987 | 1,340 | 807 | 1,704 | 2,031 |
| 2040 | 991 | 1,090 | 1,480 | 891 | 1,882 | 2,243 |
| 2045 | 1,094 | 1,203 | 1,634 | 983 | 2,077 | 2,476 |
| 2050 | 1,208 | 1,329 | 1,804 | 1,086 | 2,294 | 2,734 |
| 2055 | 1,333 | 1,467 | 1,992 | 1,199 | 2,532 | 3,019 |
| 2060 | 1,472 | 1,619 | 2,199 | 1,324 | 2,796 | 3,333 |
Table 39 Footnotes
| ||||||
B.5.4 Average benefits in relation to maximum benefits
The average benefits in relation to maximum benefits are the results of a two-step process. In the first step, for each cell determined by age, sex, type and level of benefit, the average benefit paid was compared to the maximum benefit rate for each of the past five years ending in 2024. The average levels over those five years are then assumed to remain constant over the projection period.
In the second step, the assumed effects of TFSAs, additional CPP and QPP benefits, and voluntary deferrals are introduced, and this results in individuals moving to different benefit levels. This has the effect of changing the distribution of beneficiaries by level and of increasing the aforementioned averages over time. The resulting assumed average benefits as a percentage of their maximum amounts by level (partial, full, and overall average level of benefit) and type are presented in Table 40 and Table 41.
For the OAS and the GIS, it is possible for a beneficiary to receive more than 100% of the maximum benefit. For the OAS, this situation can happen for cases where there is a voluntary deferral and an actuarial adjustment factor is applied making the benefit higher than the maximum. For the GIS, the situation happens if the person is receiving a partial OAS basic pension. In these cases, the maximum GIS benefit is increased by the difference between the full and partial basic pension.
| Benefit | 2025 | 2060 | ||||
|---|---|---|---|---|---|---|
| Partial | FullTable 40 Footnote 1 | All | Partial | FullTable 40 Footnote 1 | All | |
| OAS before age 75 | 63.8 | 102.2 | 96.5 | 66.9 | 103.0 | 97.4 |
| OAS after age 74 | 44.6Table 40 Footnote 2 | 101.0 | 93.5 | 62.8 | 104.7 | 96.6 |
| GIS-Single | 57.4 | 125.8 | 66.8 | 49.4 | 128.9 | 60.7 |
| GIS-Spouse a pensioner | 41.6 | 162.0 | 69.0 | 37.6 | 164.7 | 70.1 |
| GIS-Spouse not a pensioner | 35.7 | 112.9 | 51.9 | 34.3 | 114.6 | 51.1 |
| GIS-Spouse with Allowance | 55.5 | 126.5 | 85.1 | 50.7 | 127.5 | 82.2 |
| Allowance-Regular | 37.6 | 100.0 | 39.3 | 28.7 | 100.0 | 30.3 |
| Allowance-Survivor | 54.2 | 100.0 | 60.1 | 43.5 | 100.0 | 55.5 |
Table 40 Footnotes
| ||||||
| Benefit | 2025 | 2060 | ||||
|---|---|---|---|---|---|---|
| Partial | FullTable 41 Footnote 1 | All | Partial | FullTable 41 Footnote 1 | All | |
| OAS before age 75 | 63.4 | 101.7 | 96.1 | 66.8 | 102.5 | 97.0 |
| OAS after age 74 | 43.2Table 41 Footnote 2 | 100.6 | 93.2 | 63.5 | 103.9 | 96.0 |
| GIS-Single | 53.7 | 135.3 | 68.6 | 48.4 | 138.2 | 65.5 |
| GIS-Spouse a pensioner | 41.9 | 155.9 | 67.8 | 39.3 | 154.7 | 68.8 |
| GIS-Spouse not a pensioner | 42.0 | 115.5 | 56.1 | 43.3 | 117.2 | 58.1 |
| GIS-Spouse with Allowance | 53.0 | 112.7 | 74.2 | 47.4 | 113.2 | 69.6 |
| Allowance-Regular | 43.3 | 100.0 | 44.8 | 34.4 | 100.0 | 35.9 |
| Allowance-Survivor | 51.8 | 100.0 | 58.0 | 42.2 | 100.0 | 53.6 |
Table 41 Footnotes
| ||||||
B.6 Expenditures
B.6.1 Benefits
The expenditure for each year for a given type of benefit was computed as the sum, over all relevant population cells, of the product of:
- the population as at 1 July (by age and sex);
- the recipient rates (that vary by type of benefit, level of benefit, age, sex, and calendar year);
- the average benefit of those in the level-of-benefit cell as a percentage of the maximum benefit (varies by type of benefit, age, sex, and calendar year); and
- 12 times the maximum benefit as at 1 July.
As part of the methodology validation process, the number of beneficiaries and amounts of total annual benefits computed as above are compared to the actual results for 1983 through 2024 by type of benefit. Based on these comparisons, experience adjustment factors are obtained, which are then applied to the future projections of the different types of benefits.
Detailed tables for the projected number of beneficiaries and total expenditures by sex, type and level of benefit are presented in Appendix E.
B.6.2 Administrative Expenses
Based on experience over the last three years, recurrent administrative expenses averaged 0.5% of total benefit payments. Additional administrative expenses related to special projects averaged 0.2% of benefit payments over the same period. Accordingly, the administrative expenses assumption was set to 0.7% of benefit payments for 2025 and 2026, before being gradually reduced to 0.5% starting in 2031.
Appendix C — Detailed reconciliations with previous triennial report
The cost ratio of expenditures to GDP in a given year is an important measure of the program’s cost. One way to explain the differences between the best-estimate projections presented in this report and those set out in the 18th Actuarial Report on the OAS program as at 31 December 2021 is to examine the impact of various contributing factors on this cost ratio. The most significant factors are identified in the reconciliation shown in Table 42 and discussed below.
The results presented in this report differ from those previously projected for several reasons. Differences between the actual experience observed from 2022 through 2024 and that projected in the 18th Actuarial Report on the OAS program for the same period were addressed in section 6.2 of this report. Since historical results provide the starting point for the projections shown in this report, these differences between actual and projected experience have an effect on the projections. The section provides more details on the impact of the experience update and changes in the assumptions and methodology.
This report reflects a number of improvements made to the methodology used in previous reports. The main methodology changes were related to improvements in modeling NPR. The overall impact from the changes in methodology decreases the cost ratio in the long term by 0.11 percentages points.
Overall, the experience update had the effect of reducing the cost ratio by 0.05 percentage points in 2060. This was mainly due to higher than expected GDP at the end of 2024.
Changes made to key best-estimate assumptions since the previous triennial report are outlined in Table 1 and Table 2 of this report. The effects of these changes are also shown in Table 42 and are summarized below:
- The assumed total fertility rates are lower than those assumed in the previous triennial report, and as such lead to a decrease in both expenditures and the GDP, and has a net effect of increasing the cost ratio in the long term.
- The higher mortality improvement rates assumed for this report slightly increase the cost ratio in the long term. However, other changes in mortality assumptions, including the initial lower mortality rates due to Statistics Canada’s data revision, reduce expenditures in the short term.
- The assumed level of net migration excluding NPR is higher over the projection period than in the previous triennial report, which increases the GDP immediately and increases benefits later on. In addition, changes to the assumption on the level of NPR as a percentage of the population result in a decrease in expenditures. The combined effect significantly reduces the cost ratio.
Overall, the changes in the demographic assumptions mostly offset each other in the long term, with a resulting small increase in the cost ratio of one percentage point.
- The decrease in the real wage growth assumption causes the cost ratio to rise due to the resulting projected higher GIS and Allowance benefit expenditures and lower GDP compared to the previous triennial report.
- The assumed inflation rate has a significant impact on the benefit expenditures growth over time. However, it has a small effect on the cost ratio over the long term. The reason is that although benefit expenditures are affected by inflation indexation, the growth in GDP is also affected by inflation.
- In the short term, the combined effect of the assumed labour force participation rates, employment rates, real wage growth, and inflation rate result in an increase in the cost ratio due to the lower projected GDP.
- The revised lower OAS recipient rates assumptions decrease slightly the expenditures and cost ratio due to higher deferrals of the OAS basic pension. The revised lower GIS and Allowance recipient rates assumptions also decrease the expenditures and cost ratio.
Some other assumptions, which are described in Appendix B, were also changed. For example, the administrative expense assumption was revised in the short term to reflect additional ad hoc expenses. Overall, the changes in these other assumptions had a minimal impact on the cost ratio over the long term.
| 2025 | 2060 | |||||
|---|---|---|---|---|---|---|
| Expenditures | GDP | Cost ratio | Expenditures | GDP | Cost ratio | |
| 18th Actuarial Report on the OAS Program | 87.99 | 3,169 | 2.78 | 276.52 | 10,481 | 2.64 |
I. Legislated amendments:
| 0.00 | 0 | 0.00 | 0.00 | 0 | 0.00 |
| Total amendments | 0.00 | 0 | 0.00 | 0.00 | 0 | 0.00 |
| II. Improvements in methodology | (0.17) | (8) | 0.00 | (12.15) | (22) | (0.11) |
| III. Experience update (2022 to 2024) | ||||||
| Demographic | (0.77) | (5) | (0.02) | 2.87 | (41) | 0.04 |
| Economic | 0.64 | 59 | (0.03) | 2.53 | 446 | (0.09) |
| Benefits | (0.41) | 0 | (0.01) | (0.31) | 0 | 0.00 |
| Subtotal: | (0.55) | 54 | (0.06) | 5.09 | 405 | (0.05) |
| IV. Changes in assumptions | ||||||
| Fertility | 0.00 | 0 | 0.00 | (0.41) | (496) | 0.12 |
| Mortality | (0.06) | 133 | 0.00 | 2.38 | 687 | 0.02 |
| Net migration | 0.07 | (1) | (0.11) | 4.24 | (2) | (0.13) |
| Economic assumptions | (0.05) | (100) | 0.08 | 1.21 | (487) | 0.13 |
| Benefits | 0.02 | 0 | 0.00 | 0.81 | 0 | 0.01 |
| Other assumptions | 0.17 | 0 | 0.01 | 0.00 | 0 | 0.00 |
| Subtotal: | 0.17 | 33 | (0.02) | 8.24 | (298) | 0.15 |
| Total of I to IV | (0.55) | 79 | (0.08) | 1.19 | 85 | (0.01) |
| 19th Actuarial Report on the OAS Program | 87.44 | 3,249 | 2.69 | 277.71 | 10,565 | 2.63 |
Appendix D — Uncertainty of results
D.1 Introduction
This actuarial report on the OAS program is based on the projection of its expenditures over a long period of time. The information required by statute, which is presented in the Results section 5 of this report, has been derived using best-estimate assumptions regarding future demographic and economic trends. Given the length of the projection period and the number of assumptions required, it is unlikely that actual future experience will develop precisely in accordance with the best-estimate projections.
The inherent uncertainty of the projections is amplified in the current global context. Emerging and evolving trends such as the impacts of climate change, shifting geopolitical dynamics, evolving trade policies, and rapid technological advancements introduce significant variability into economic and demographic outlooks.
The objective of this Appendix of the report is to illustrate the sensitivity of the long-term projections of the OAS program to changes in the future demographic and economic outlooks.
The future expenditures of the OAS program depend on many demographic and economic factors, including fertility, mortality, migration, the labour force, average earnings, inflation, recipient rates, and indexation of benefits. The expenditures will depend on how these factors affect the size and composition of the beneficiary population and the general level of benefits.
Expenditures are measured relative to the GDP. As a result, changes to assumptions in the sensitivity analysis may affect not only projected expenditures, but also the GDP used as the measurement base.
Section D.2 presents sensitivity tests on individual long-term assumptions that are derived based on judgment (i.e. deterministic). Next, sections D.3 builds on the individual sensitivity tests performed in section D.2 by combining various assumptions of the individual tests to create scenarios of higher and lower long-term economic growth. The combination of the individual sensitivity test assumptions is not intended to represent probable scenarios, but rather to illustrate the potential high-level impacts from different economic environments. Finally, section D.4 makes use of scenario analysis to illustrate certain risks that are relevant in the current context. These scenarios are prepared for illustration purposes only and are not meant to represent forecasts or predictions.
Climate scenarios and a corresponding framework have been developed to illustrate the potential risks of climate change on the OAS program. As stated in the Revised 32nd CPP Actuarial Report, these scenarios are subsets of the Network of Central Banks and Supervisors for Greening the Financial System (NGFS) Phase V scenarios, which incorporate a new physical risk damage function originally published by Kotz et al. in the science journal NatureFootnote 5. The paper received academic critique following its publication, and was retracted on December 3, 2025Footnote 6. To avoid potential misrepresentation of risks, given the concerns regarding the public data used for the illustrative scenarios, this report does not present any results related to climate scenarios. The OCA remains committed to continue assessing the potential impact of climate risk on the OAS program and will publish a quantitative analysis once updated data are released.
D.2 Individual sensitivity tests
The key best-estimate assumptions used for the projections in this report are described in Appendix - B. Individual sensitivity tests have been performed that consist of projecting the expenditures of the OAS program using alternative individual assumptions to illustrate a reasonable range of how experience could vary from the best-estimate projections. The individual results cannot simply be combined, because a change in any one particular assumption may have an impact on other assumptions to varying degrees.
All individual sensitivity tests are deterministic and so based on judgment. The ranges analyzed for each assumption are described below.
The sensitivity tests were performed by varying most of the key assumptions individually and by keeping the remaining assumptions at their best-estimate levels. Each sensitivity test was categorized as either a lower-cost scenario or a higher-cost scenario. In the lower-cost scenarios, the alternative assumptions have the effect of reducing the cost ratios expressed as a percentage of GDP. Conversely, the assumptions for the higher-cost scenarios increase the cost ratios expressed as a percentage of GDP. It should also be noted that once the lower- and higher-cost assumptions reach their ultimate values, they are held constant for the rest of the projection period, and the OAS program is assumed to remain in its current form.
Table 43 summarizes the alternative assumptions used in the individual sensitivity tests. It is followed by a brief discussion of these tests.
| Assumptions | Lower cost | Best estimate | Higher cost |
|---|---|---|---|
| Total fertility rate | 1.65 | 1.35 | 1.05 |
| Mortality: Canadian life expectancy at age 65 in 2050 with future improvements - males | 20.8 | 23.4 | 25.9 |
| Mortality: Canadian life expectancy at age 65 in 2050 with future improvements - females | 23.2 | 25.7 | 28.1 |
| Net migration rateTable 43 Footnote 1 | 0.92% | 0.72% | 0.52% |
| and non-permanent residents level | 4% | 2.5% | 1% |
| GIS recipient rates in 2030 | 24.2% | 30.2% | 36.2% |
| Allowance recipient rates in 2030 | 1.8% | 2.2% | 2.6% |
| Benefit indexation | CPI less 1% | CPI | CPI plus 60% of the real wage increase |
Table 43 Footnotes
| |||
The following provides some observations on the selection of assumptions for lower- and higher-cost scenarios.
- Fertility rates: This test will only have an impact on the long term, when working life starts and impacts the GDP. Experience of all ten provinces was used to generate the lower- and higher-cost scenarios over the projection period.
- Mortality rates: Under the lower‑cost scenario, mortality is assumed to improve at a slower rate than under the best‑estimate scenario, with ultimate values of the mortality improvement rates gradually reduced to 0% for all ages in 2039. Under the higher-cost scenario, mortality is assumed to improve at a faster pace than under the best-estimate scenario with the ultimate mortality improvement rates being doubled compared to their best‑estimate values.
- Net migration rates and non-permanent residents levels: For the lower-cost assumption, the ultimate net migration rate is assumed to increase by 0.20 percentage points, while the ultimate level of non-permanent residents as a percentage of population is assumed to increase to 4.0%. For the higher-cost assumption, the ultimate net migration rate is assumed to decrease by 0.20 percentage points, while the ultimate level of non-permanent residents as a percentage of population is assumed to decrease to 1.0%. The lower-cost and higher-cost assumptions were selected by analyzing historical data and trends.
- GIS and allowance recipient rates: Under the lower-cost scenario, the best-estimate recipient rates for the GIS and Allowance are reduced by 20%. Under the higher-cost scenario, the recipient rates for GIS and Allowance benefits are increased by 20%. The adjustments are applied to the base recipient rates, they are phased in over five years (2026 to 2030) and are maintained thereafter.
- Benefit indexation: Under the lower-cost scenario, the benefit indexation is assumed at CPI minus 1%. Under the higher-cost scenario, the benefit rates are partially increased to reflect the growth in real wages. The assumption made for this test is that benefit rates would be indexed at rates equal to the assumed rate of growth in prices plus 60% of the assumed real wage increase.
D.2.1 Results
Table 44 summarizes the projected impacts on the cost ratio of expenditures to GDP under each of the alternative sets of assumptions.
| Assumption | Scenario | 2025 | 2030 | 2060 |
|---|---|---|---|---|
| All | Best-estimate | 2.69 | 2.90 | 2.63 |
| Total fertility rate | Lower cost | 2.69 | 2.90 | 2.49 |
| Higher cost | 2.69 | 2.90 | 2.78 | |
| Mortality rates | Lower cost | 2.69 | 2.90 | 2.44 |
| Higher cost | 2.69 | 2.91 | 2.80 | |
| Net migration rate | Lower cost | 2.69 | 2.90 | 2.39 |
| Higher cost | 2.69 | 2.91 | 2.91 | |
| GIS and Allowance recipient rates | Lower cost | 2.69 | 2.77 | 2.53 |
| Higher cost | 2.69 | 3.03 | 2.73 | |
| Benefit indexation | Lower cost | 2.69 | 2.74 | 1.79 |
| Higher cost | 2.69 | 2.98 | 3.16 |
D.3 Higher and lower economic growth
While the best-estimate assumptions in this report reflect sustained moderate economic growth in the future, there is significant uncertainty and volatility surrounding the economic environment. Many factors could lead to long-term economic growth in Canada being different than assumed under the best-estimate scenario. These factors could stem from both domestic and global forces, and include geopolitical conflicts, health crises, extreme weather events due to climate change, the timing and pace of transition to a green economy, the pace of technological advances and innovation, shifts in global trade dynamics between protectionism and globalisation, as well as demographic pressures from an aging population.
Given the high level of uncertainty, scenarios of higher and lower economic growth were considered in this report. These alternative economic growth scenarios are constructed using a combination of individual assumptions, specifically, the labour market assumptions and the real wage growth assumption.
In respect of the labour market, employment levels are reflected in the actuarial projection model through the assumptions made regarding labour force participation and job creation rates by year, age, and sex. These rates vary not only with the rate of unemployment, but also reflect the trend of increased female participation rates and trends in the workforce attachment patterns of older workers.
Under the best-estimate scenario, the job creation rate assumption is determined on the basis of expected moderate economic growth and an unemployment rate (ages 15+) that is projected to increase from 6.3% in 2024 to 7.0% in 2025, and then decrease to 6.7% by 2026, reaching an ultimate level of 6.1% by 2028. Furthermore, the participation rates for all age groups are expected to increase due in part to the projected growth in labour force participation rates of women and continuing trends toward longer working lives. Under the best-estimate scenario, the participation rate of those aged 18 to 69 for Canada is expected to increase from 77.3% in 2025 to 80.0% in 2035.
The best-estimate assumption for the real wage increase is assumed to be 0.8% in 2025 and onward. The ultimate real wage increase assumption together with the price increase assumption of 2.0% leads to an ultimate nominal wage increase of 2.8% for 2027 and thereafter.
D.3.1 Higher economic growth
For this higher economic growth scenario, the job creation rate is assumed to increase at a faster pace than under the best-estimate scenario, resulting in an unemployment rate of 4.1% in 2030 and thereafter. In addition, the assumed ultimate participation rates in 2035 are set to increase to higher levels than the best estimates, and the assumed ultimate gap between male and female participation rates in 2035 for those aged 18 to 69 is set equal to 3.1% as opposed to 6.1% under the best-estimate scenario. This results in an overall participation rate of 85.1%.
In addition to the assumed changes in the labour market, the real wage increase is assumed to be 1.4% as opposed to 0.8% under the best-estimate scenario. The higher economic growth scenario results in total employment earnings in 2035 being about 16% higher compared to the best estimate.
D.3.2 Lower economic growth
For this lower economic growth scenario, the job creation rate is assumed to increase at a slower pace than the best estimate, resulting in an unemployment rate of 8.1% in 2030 and thereafter. In addition, male and female participation rates by age group are assumed to remain constant at their 2024 levels. This results in an overall participation rate of 77.8% for those aged 18 to 69 in 2035.
In addition to the assumed changes in the labour market, the real wage increase assumption is 0.2% compared to 0.8% under the best-estimate scenario. The lower economic growth scenario results in total employment earnings in 2035 being about 11% lower compared to the best estimate.
D.3.3 Results
Table 45 present a summary of the assumptions and results used in the sensitivity analysis of economic growth and the resulting cost of the program expressed as a percentage of GDP in 2060.
Under the higher economic growth scenario, the cost ratio of expenditures to GDP decreases to 1.93% compared to 2.63% under the best-estimate scenario. Under the lower economic growth scenario, the cost ratio increases to 3.48%.
| Changes to labour market and real wage increase | Higher economic growth | Best-Estimate | Lower economic growth |
|---|---|---|---|
| Participation rate (age group 18-69) (2035) | 85.1% | 80.0% | 77.8% |
| Unemployment rate (15+) (Ultimate) | 4.1% | 6.1% | 8.1% |
| Real wage increase (Ultimate) | 1.4% | 0.8% | 0.2% |
| Expenditures as % of GDP in 2060 | 1.93% | 2.63% | 3.48% |
D.4 Scenario analysis
D.4.1 Acute economic event
D.4.1.1 Context
The best-estimate assumptions of this report are set in the context of sustained moderate economic growth over the projection period. Individual sensitivity tests and long-term higher and lower growth economic scenarios illustrate the impact of sustained differences in assumptions compared to the best estimates for the program. The purpose of this scenario is to illustrate the impact of an acute, relatively short-term economic event on the cost ratio of OAS program expenditures as a percentage of GDP. This scenario could be instigated by any number of causes, for example, geopolitical events, escalating trade tensions, public health crises, etc. The economic environment resulting from the acute economic shock is characterized by high inflation, high unemployment, and low real wage growth.
The acute economic event scenario draws on historical shocks and patterns in underlying variables but is not based on one particular period of history.
The event would be characterized by a short burst of high inflation that surpasses what was seen during the COVID-19 pandemic. The disruption in the economy would cause immediate job losses. Real wages would decline as the weak labour markets would not result in wages keeping up with the high inflation.
D.4.1.2 Assumptions
The acute economic event scenario introduces economic shocks beginning in 2026 and is assumed to unfold over a four-year period. Under such a scenario, inflation is projected to rise sharply in 2026 before gradually returning to the Bank of Canada’s target range within three years, following a similar trajectory as observed during the COVID-19 pandemic. Specifically, inflation is assumed to reach 7% in 2026, then decline to 4% in 2027, 3% in 2028, and return to the 2% target rate by 2029.
It is assumed that unemployment rates will remain elevated relative to the best-estimate assumptions for a few years following the acute economic event. The unemployment rate is assumed to peak at 11.0% in 2026, then decline to 9.0% in 2027. Further decreases are assumed in 2028 and 2029, with rates of 8.0% and 7.0%, respectively. By 2030, the unemployment rate is assumed to return to the best-estimate ultimate level of 6.1%.
It is assumed that only a portion of inflation is reflected in nominal wage increases, leading to lower real wage growth under this scenario. This pass-through rate is projected to gradually rise, reaching 100% by 2028. Real wage growth is assumed to be -4% in 2026, -2% in 2027, and 0% in 2028, before returning to the ultimate best-estimate assumption of 0.8% in 2029.
D.4.1.3 Results
Under the acute economic event scenario, OAS program expenditures increase by about 3% in 2026 and 8% after 2030 due to inflation. On the other hand, the GDP decreases under the scenario by 4% in 2026 and by about 0.5% by 2030 due to lower nominal wages and higher unemployment. The combined impact on the cost ratio of expenditures to GDP is an increase of 0.23 percentage points (from 2.76% to 2.99%) in 2026 and about 0.28 percentage points (from 2.90% to 3.18%) by 2030. After 2030, the increase in the cost ratio gradually declines to about 0.25 percentage points by 2060, resulting in a cost ratio of 2.88% under the acute economic event scenario compared to 2.63% under the best-estimate scenario. While the acute economic scenario illustrates short-term shocks, its effects on the OAS program extend beyond the immediate period, with both short- and long-term impacts on expenditures and the cost ratios.
Appendix E — Detailed projections of beneficiaries and expenditures
The following tables present detailed projections of the number of beneficiaries and amounts of expenditures for the OAS basic pension, GIS, and Allowance benefits. All figures shown include benefits paid outside Canada.
The tables providing GIS projections account for the increase in the supplement paid to individuals receiving partial OAS pensions. For these individuals, the GIS is increased by the difference between the full and partial OAS pension.
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 46 Footnote 2 | Partial | Full | TotalTable 46 Footnote 2 | Partial | Full | TotalTable 46 Footnote 2 | |
| 2025 | 493 | 3,013 | 3,505 | 570 | 3,541 | 4,112 | 1,063 | 6,554 | 7,617 |
| 2026 | 519 | 3,115 | 3,634 | 601 | 3,649 | 4,250 | 1,120 | 6,764 | 7,884 |
| 2027 | 545 | 3,213 | 3,758 | 633 | 3,752 | 4,384 | 1,178 | 6,965 | 8,143 |
| 2028 | 573 | 3,310 | 3,883 | 665 | 3,854 | 4,519 | 1,238 | 7,164 | 8,402 |
| 2029 | 601 | 3,402 | 4,003 | 697 | 3,952 | 4,649 | 1,298 | 7,354 | 8,652 |
| 2030 | 627 | 3,486 | 4,113 | 729 | 4,042 | 4,771 | 1,357 | 7,527 | 8,884 |
| 2031 | 652 | 3,554 | 4,206 | 759 | 4,117 | 4,876 | 1,411 | 7,671 | 9,082 |
| 2032 | 675 | 3,609 | 4,284 | 787 | 4,180 | 4,967 | 1,462 | 7,789 | 9,251 |
| 2033 | 696 | 3,658 | 4,354 | 813 | 4,239 | 5,052 | 1,509 | 7,897 | 9,406 |
| 2034 | 716 | 3,704 | 4,420 | 838 | 4,296 | 5,134 | 1,554 | 8,000 | 9,554 |
| 2035 | 735 | 3,748 | 4,483 | 862 | 4,351 | 5,213 | 1,597 | 8,099 | 9,696 |
| 2040 | 807 | 3,900 | 4,707 | 959 | 4,557 | 5,516 | 1,766 | 8,457 | 10,223 |
| 2045 | 857 | 4,020 | 4,877 | 1,028 | 4,718 | 5,745 | 1,885 | 8,738 | 10,623 |
| 2050 | 902 | 4,189 | 5,091 | 1,084 | 4,906 | 5,990 | 1,987 | 9,095 | 11,081 |
| 2055 | 948 | 4,420 | 5,368 | 1,132 | 5,138 | 6,269 | 2,079 | 9,558 | 11,638 |
| 2060 | 1,011 | 4,741 | 5,752 | 1,190 | 5,436 | 6,626 | 2,201 | 10,177 | 12,378 |
Table 46 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 47 Footnote 2 | Partial | Full | TotalTable 47 Footnote 2 | Partial | Full | TotalTable 47 Footnote 2 | |
| 2025 | 2,504 | 28,205 | 30,708 | 2,829 | 33,129 | 35,957 | 5,332 | 61,333 | 66,666 |
| 2026 | 2,745 | 29,859 | 32,605 | 3,117 | 34,932 | 38,049 | 5,862 | 64,792 | 70,654 |
| 2027 | 2,996 | 31,497 | 34,494 | 3,416 | 36,715 | 40,131 | 6,412 | 68,213 | 74,625 |
| 2028 | 3,261 | 33,172 | 36,433 | 3,731 | 38,544 | 42,275 | 6,992 | 71,716 | 78,708 |
| 2029 | 3,536 | 34,856 | 38,392 | 4,059 | 40,393 | 44,452 | 7,595 | 75,249 | 82,844 |
| 2030 | 3,817 | 36,507 | 40,323 | 4,394 | 42,220 | 46,614 | 8,210 | 78,727 | 86,937 |
| 2031 | 4,093 | 38,061 | 42,154 | 4,726 | 43,958 | 48,684 | 8,819 | 82,019 | 90,838 |
| 2032 | 4,363 | 39,523 | 43,887 | 5,056 | 45,631 | 50,687 | 9,420 | 85,155 | 94,574 |
| 2033 | 4,632 | 40,962 | 45,594 | 5,387 | 47,300 | 52,687 | 10,019 | 88,262 | 98,281 |
| 2034 | 4,901 | 42,407 | 47,308 | 5,718 | 48,993 | 54,712 | 10,619 | 91,401 | 102,020 |
| 2035 | 5,169 | 43,865 | 49,035 | 6,051 | 50,716 | 56,767 | 11,220 | 94,581 | 105,802 |
| 2040 | 6,446 | 50,839 | 57,285 | 7,666 | 59,131 | 66,798 | 14,113 | 109,970 | 124,083 |
| 2045 | 7,654 | 58,002 | 65,656 | 9,221 | 67,787 | 77,008 | 16,875 | 125,789 | 142,664 |
| 2050 | 8,933 | 66,670 | 75,603 | 10,819 | 77,828 | 88,648 | 19,753 | 144,498 | 164,251 |
| 2055 | 10,350 | 77,562 | 87,912 | 12,462 | 89,910 | 102,373 | 22,812 | 167,473 | 190,285 |
| 2060 | 12,185 | 91,779 | 103,964 | 14,459 | 104,976 | 119,435 | 26,644 | 196,755 | 223,399 |
Table 47 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 48 Footnote 1 | Partial | Full | TotalTable 48 Footnote 1 | Partial | Full | TotalTable 48 Footnote 1 | |
| 2025 | 873 | 208 | 1,081 | 1,195 | 292 | 1,487 | 2,068 | 500 | 2,568 |
| 2026 | 908 | 216 | 1,124 | 1,244 | 303 | 1,546 | 2,152 | 519 | 2,670 |
| 2027 | 943 | 223 | 1,166 | 1,293 | 314 | 1,607 | 2,236 | 537 | 2,772 |
| 2028 | 978 | 230 | 1,208 | 1,343 | 325 | 1,668 | 2,321 | 555 | 2,876 |
| 2029 | 1,012 | 237 | 1,249 | 1,394 | 335 | 1,729 | 2,405 | 573 | 2,978 |
| 2030 | 1,036 | 243 | 1,279 | 1,432 | 345 | 1,777 | 2,468 | 587 | 3,056 |
| 2031 | 1,052 | 247 | 1,299 | 1,464 | 353 | 1,817 | 2,515 | 600 | 3,115 |
| 2032 | 1,065 | 250 | 1,315 | 1,493 | 361 | 1,854 | 2,558 | 611 | 3,169 |
| 2033 | 1,076 | 253 | 1,329 | 1,521 | 368 | 1,889 | 2,597 | 621 | 3,218 |
| 2034 | 1,086 | 256 | 1,342 | 1,547 | 375 | 1,922 | 2,633 | 631 | 3,264 |
| 2035 | 1,095 | 259 | 1,354 | 1,572 | 381 | 1,953 | 2,667 | 640 | 3,307 |
| 2040 | 1,120 | 266 | 1,386 | 1,665 | 405 | 2,071 | 2,786 | 671 | 3,457 |
| 2045 | 1,115 | 267 | 1,382 | 1,694 | 417 | 2,111 | 2,810 | 684 | 3,493 |
| 2050 | 1,115 | 270 | 1,385 | 1,702 | 423 | 2,125 | 2,817 | 693 | 3,510 |
| 2055 | 1,105 | 273 | 1,378 | 1,669 | 426 | 2,095 | 2,775 | 699 | 3,473 |
| 2060 | 1,120 | 282 | 1,402 | 1,659 | 435 | 2,094 | 2,778 | 718 | 3,496 |
Table 48 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 49 Footnote 1 | Partial | Full | TotalTable 49 Footnote 1 | Partial | Full | TotalTable 49 Footnote 1 | |
| 2025 | 4,838 | 2,932 | 7,770 | 7,159 | 4,628 | 11,787 | 11,997 | 7,560 | 19,557 |
| 2026 | 5,114 | 3,100 | 8,214 | 7,575 | 4,901 | 12,477 | 12,689 | 8,001 | 20,690 |
| 2027 | 5,388 | 3,270 | 8,658 | 7,997 | 5,180 | 13,177 | 13,385 | 8,450 | 21,835 |
| 2028 | 5,668 | 3,446 | 9,114 | 8,431 | 5,469 | 13,899 | 14,099 | 8,914 | 23,013 |
| 2029 | 5,947 | 3,623 | 9,570 | 8,875 | 5,765 | 14,640 | 14,822 | 9,389 | 24,210 |
| 2030 | 6,195 | 3,783 | 9,978 | 9,286 | 6,048 | 15,334 | 15,481 | 9,832 | 25,312 |
| 2031 | 6,399 | 3,933 | 10,331 | 9,660 | 6,324 | 15,984 | 16,059 | 10,257 | 26,315 |
| 2032 | 6,579 | 4,073 | 10,652 | 10,022 | 6,598 | 16,620 | 16,601 | 10,671 | 27,272 |
| 2033 | 6,748 | 4,211 | 10,959 | 10,379 | 6,873 | 17,252 | 17,128 | 11,084 | 28,211 |
| 2034 | 6,914 | 4,348 | 11,261 | 10,737 | 7,151 | 17,888 | 17,650 | 11,499 | 29,149 |
| 2035 | 7,079 | 4,485 | 11,565 | 11,096 | 7,430 | 18,526 | 18,176 | 11,915 | 30,091 |
| 2040 | 7,828 | 5,130 | 12,958 | 12,819 | 8,784 | 21,603 | 20,647 | 13,914 | 34,561 |
| 2045 | 8,458 | 5,737 | 14,195 | 14,220 | 10,064 | 24,284 | 22,677 | 15,801 | 38,478 |
| 2050 | 9,234 | 6,397 | 15,631 | 15,620 | 11,299 | 26,920 | 24,854 | 17,697 | 42,551 |
| 2055 | 10,110 | 7,156 | 17,266 | 16,952 | 12,583 | 29,535 | 27,062 | 19,738 | 46,801 |
| 2060 | 11,235 | 8,139 | 19,375 | 18,522 | 14,160 | 32,682 | 29,758 | 22,299 | 52,057 |
Table 49 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 50 Footnote 1 | Partial | Full | TotalTable 50 Footnote 1 | Partial | Full | TotalTable 50 Footnote 1 | |
| 2025 | 422 | 68 | 489 | 830 | 185 | 1,014 | 1,251 | 253 | 1,504 |
| 2026 | 438 | 70 | 508 | 863 | 191 | 1,054 | 1,301 | 261 | 1,562 |
| 2027 | 454 | 72 | 526 | 896 | 198 | 1,095 | 1,351 | 270 | 1,621 |
| 2028 | 470 | 75 | 545 | 931 | 205 | 1,136 | 1,401 | 279 | 1,681 |
| 2029 | 486 | 77 | 563 | 965 | 212 | 1,177 | 1,451 | 288 | 1,740 |
| 2030 | 498 | 78 | 577 | 992 | 217 | 1,210 | 1,491 | 296 | 1,786 |
| 2031 | 507 | 80 | 587 | 1,015 | 223 | 1,237 | 1,522 | 302 | 1,824 |
| 2032 | 515 | 81 | 595 | 1,037 | 227 | 1,264 | 1,551 | 308 | 1,859 |
| 2033 | 521 | 82 | 602 | 1,058 | 232 | 1,289 | 1,578 | 314 | 1,892 |
| 2034 | 527 | 83 | 609 | 1,078 | 236 | 1,314 | 1,604 | 319 | 1,923 |
| 2035 | 532 | 83 | 615 | 1,098 | 241 | 1,338 | 1,630 | 324 | 1,954 |
| 2040 | 550 | 87 | 636 | 1,179 | 259 | 1,438 | 1,728 | 346 | 2,074 |
| 2045 | 557 | 89 | 646 | 1,219 | 271 | 1,490 | 1,776 | 360 | 2,137 |
| 2050 | 569 | 92 | 661 | 1,243 | 279 | 1,522 | 1,812 | 371 | 2,183 |
| 2055 | 575 | 95 | 670 | 1,229 | 283 | 1,512 | 1,804 | 378 | 2,182 |
| 2060 | 590 | 98 | 688 | 1,224 | 288 | 1,512 | 1,814 | 386 | 2,200 |
Table 50 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 51 Footnote 1 | Partial | Full | TotalTable 51 Footnote 1 | Partial | Full | TotalTable 51 Footnote 1 | |
| 2025 | 3,185 | 1,123 | 4,308 | 5,873 | 3,293 | 9,166 | 9,058 | 4,416 | 13,474 |
| 2026 | 3,364 | 1,186 | 4,550 | 6,210 | 3,485 | 9,695 | 9,573 | 4,671 | 14,245 |
| 2027 | 3,541 | 1,250 | 4,791 | 6,550 | 3,682 | 10,232 | 10,091 | 4,931 | 15,023 |
| 2028 | 3,722 | 1,316 | 5,038 | 6,900 | 3,885 | 10,786 | 10,623 | 5,202 | 15,824 |
| 2029 | 3,902 | 1,383 | 5,286 | 7,259 | 4,095 | 11,354 | 11,161 | 5,479 | 16,640 |
| 2030 | 4,067 | 1,443 | 5,511 | 7,594 | 4,297 | 11,892 | 11,662 | 5,741 | 17,402 |
| 2031 | 4,204 | 1,500 | 5,704 | 7,903 | 4,495 | 12,398 | 12,107 | 5,995 | 18,102 |
| 2032 | 4,326 | 1,553 | 5,879 | 8,202 | 4,692 | 12,894 | 12,528 | 6,245 | 18,773 |
| 2033 | 4,440 | 1,606 | 6,046 | 8,498 | 4,892 | 13,390 | 12,938 | 6,498 | 19,436 |
| 2034 | 4,551 | 1,661 | 6,211 | 8,796 | 5,096 | 13,893 | 13,347 | 6,757 | 20,104 |
| 2035 | 4,662 | 1,717 | 6,378 | 9,098 | 5,304 | 14,402 | 13,760 | 7,021 | 20,781 |
| 2040 | 5,169 | 1,991 | 7,160 | 10,573 | 6,343 | 16,917 | 15,743 | 8,334 | 24,077 |
| 2045 | 5,624 | 2,273 | 7,897 | 11,825 | 7,365 | 19,191 | 17,450 | 9,638 | 27,087 |
| 2050 | 6,205 | 2,591 | 8,796 | 13,092 | 8,363 | 21,455 | 19,297 | 10,954 | 30,251 |
| 2055 | 6,863 | 2,932 | 9,795 | 14,276 | 9,357 | 23,634 | 21,139 | 12,289 | 33,428 |
| 2060 | 7,686 | 3,333 | 11,019 | 15,621 | 10,515 | 26,136 | 23,308 | 13,848 | 37,155 |
Table 51 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 52 Footnote 1 | Partial | Full | TotalTable 52 Footnote 1 | Partial | Full | TotalTable 52 Footnote 1 | |
| 2025 | 329 | 97 | 426 | 329 | 97 | 426 | 658 | 194 | 852 |
| 2026 | 344 | 101 | 445 | 344 | 101 | 445 | 688 | 202 | 889 |
| 2027 | 359 | 105 | 464 | 359 | 105 | 464 | 718 | 210 | 927 |
| 2028 | 374 | 109 | 483 | 374 | 109 | 483 | 748 | 218 | 966 |
| 2029 | 389 | 113 | 502 | 389 | 113 | 502 | 778 | 226 | 1,004 |
| 2030 | 400 | 116 | 517 | 400 | 116 | 517 | 801 | 233 | 1,033 |
| 2031 | 409 | 119 | 528 | 409 | 119 | 528 | 818 | 239 | 1,057 |
| 2032 | 417 | 122 | 539 | 417 | 122 | 539 | 834 | 245 | 1,079 |
| 2033 | 424 | 125 | 549 | 424 | 125 | 549 | 848 | 250 | 1,098 |
| 2034 | 430 | 127 | 558 | 430 | 127 | 558 | 860 | 255 | 1,115 |
| 2035 | 435 | 130 | 565 | 435 | 130 | 565 | 871 | 259 | 1,130 |
| 2040 | 448 | 136 | 584 | 448 | 136 | 584 | 896 | 272 | 1,168 |
| 2045 | 437 | 135 | 572 | 437 | 135 | 572 | 874 | 270 | 1,144 |
| 2050 | 420 | 134 | 554 | 420 | 134 | 553 | 840 | 267 | 1,107 |
| 2055 | 401 | 132 | 533 | 401 | 132 | 533 | 803 | 263 | 1,066 |
| 2060 | 395 | 135 | 530 | 395 | 135 | 530 | 790 | 271 | 1,060 |
Table 52 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 53 Footnote 1 | Partial | Full | TotalTable 53 Footnote 1 | Partial | Full | TotalTable 53 Footnote 1 | |
| 2025 | 1,086 | 1,246 | 2,332 | 1,093 | 1,199 | 2,292 | 2,179 | 2,444 | 4,623 |
| 2026 | 1,154 | 1,324 | 2,479 | 1,163 | 1,273 | 2,436 | 2,318 | 2,597 | 4,915 |
| 2027 | 1,225 | 1,405 | 2,630 | 1,235 | 1,349 | 2,584 | 2,460 | 2,754 | 5,214 |
| 2028 | 1,297 | 1,488 | 2,785 | 1,309 | 1,427 | 2,736 | 2,606 | 2,916 | 5,521 |
| 2029 | 1,371 | 1,574 | 2,945 | 1,385 | 1,508 | 2,893 | 2,755 | 3,082 | 5,838 |
| 2030 | 1,436 | 1,656 | 3,092 | 1,452 | 1,584 | 3,037 | 2,889 | 3,240 | 6,129 |
| 2031 | 1,494 | 1,736 | 3,230 | 1,513 | 1,659 | 3,172 | 3,007 | 3,395 | 6,402 |
| 2032 | 1,549 | 1,817 | 3,366 | 1,571 | 1,733 | 3,304 | 3,121 | 3,550 | 6,670 |
| 2033 | 1,602 | 1,896 | 3,498 | 1,627 | 1,805 | 3,433 | 3,230 | 3,701 | 6,931 |
| 2034 | 1,653 | 1,973 | 3,626 | 1,681 | 1,876 | 3,557 | 3,335 | 3,849 | 7,184 |
| 2035 | 1,702 | 2,048 | 3,750 | 1,733 | 1,944 | 3,677 | 3,435 | 3,992 | 7,428 |
| 2040 | 1,905 | 2,381 | 4,287 | 1,952 | 2,243 | 4,195 | 3,858 | 4,624 | 8,482 |
| 2045 | 2,014 | 2,635 | 4,649 | 2,070 | 2,481 | 4,550 | 4,083 | 5,116 | 9,199 |
| 2050 | 2,102 | 2,861 | 4,962 | 2,170 | 2,690 | 4,860 | 4,271 | 5,551 | 9,822 |
| 2055 | 2,199 | 3,135 | 5,334 | 2,283 | 2,947 | 5,229 | 4,482 | 6,081 | 10,563 |
| 2060 | 2,360 | 3,543 | 5,904 | 2,465 | 3,327 | 5,792 | 4,826 | 6,870 | 11,696 |
Table 53 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 54 Footnote 1 | Partial | Full | TotalTable 54 Footnote 1 | Partial | Full | TotalTable 54 Footnote 1 | |
| 2025 | 97 | 26 | 122 | 31 | 7 | 38 | 128 | 33 | 161 |
| 2026 | 100 | 26 | 126 | 32 | 8 | 39 | 132 | 34 | 166 |
| 2027 | 103 | 27 | 130 | 33 | 8 | 40 | 136 | 35 | 170 |
| 2028 | 106 | 27 | 133 | 34 | 8 | 41 | 139 | 35 | 175 |
| 2029 | 109 | 28 | 136 | 34 | 8 | 42 | 143 | 36 | 179 |
| 2030 | 109 | 28 | 137 | 35 | 8 | 43 | 144 | 36 | 180 |
| 2031 | 107 | 28 | 135 | 34 | 8 | 42 | 141 | 36 | 177 |
| 2032 | 105 | 27 | 133 | 34 | 8 | 42 | 139 | 36 | 175 |
| 2033 | 103 | 27 | 131 | 34 | 8 | 42 | 137 | 35 | 172 |
| 2034 | 102 | 27 | 129 | 34 | 8 | 42 | 136 | 35 | 170 |
| 2035 | 101 | 26 | 127 | 34 | 8 | 42 | 135 | 35 | 169 |
| 2040 | 96 | 25 | 122 | 33 | 8 | 41 | 130 | 33 | 163 |
| 2045 | 95 | 25 | 120 | 33 | 8 | 41 | 129 | 33 | 162 |
| 2050 | 98 | 26 | 124 | 34 | 8 | 42 | 132 | 34 | 166 |
| 2055 | 101 | 26 | 127 | 34 | 8 | 42 | 134 | 35 | 169 |
| 2060 | 104 | 27 | 131 | 34 | 9 | 43 | 138 | 36 | 174 |
Table 54 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 55 Footnote 1 | Partial | Full | TotalTable 55 Footnote 1 | Partial | Full | TotalTable 55 Footnote 1 | |
| 2025 | 456 | 380 | 836 | 172 | 112 | 284 | 627 | 492 | 1,120 |
| 2026 | 478 | 398 | 876 | 180 | 118 | 298 | 658 | 516 | 1,174 |
| 2027 | 499 | 415 | 914 | 189 | 123 | 312 | 687 | 538 | 1,225 |
| 2028 | 520 | 433 | 953 | 197 | 128 | 326 | 718 | 561 | 1,278 |
| 2029 | 540 | 449 | 988 | 206 | 133 | 339 | 746 | 582 | 1,328 |
| 2030 | 553 | 460 | 1,013 | 213 | 138 | 351 | 766 | 598 | 1,364 |
| 2031 | 559 | 467 | 1,026 | 218 | 141 | 359 | 777 | 608 | 1,385 |
| 2032 | 561 | 471 | 1,032 | 222 | 143 | 366 | 783 | 614 | 1,398 |
| 2033 | 562 | 475 | 1,037 | 227 | 146 | 373 | 790 | 621 | 1,410 |
| 2034 | 566 | 479 | 1,044 | 233 | 149 | 382 | 798 | 628 | 1,426 |
| 2035 | 571 | 484 | 1,055 | 238 | 152 | 390 | 809 | 636 | 1,445 |
| 2040 | 601 | 511 | 1,112 | 266 | 167 | 433 | 867 | 678 | 1,545 |
| 2045 | 655 | 559 | 1,215 | 294 | 184 | 478 | 950 | 744 | 1,693 |
| 2050 | 738 | 634 | 1,372 | 324 | 207 | 531 | 1,062 | 841 | 1,903 |
| 2055 | 832 | 723 | 1,555 | 355 | 233 | 588 | 1,187 | 956 | 2,143 |
| 2060 | 940 | 829 | 1,769 | 392 | 265 | 657 | 1,332 | 1,094 | 2,426 |
Table 55 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 56 Footnote 1 | Partial | Full | TotalTable 56 Footnote 1 | Partial | Full | TotalTable 56 Footnote 1 | |
| 2025 | 25 | 18 | 44 | 5 | 3 | 8 | 30 | 21 | 51 |
| 2026 | 26 | 19 | 45 | 5 | 3 | 8 | 31 | 21 | 53 |
| 2027 | 27 | 19 | 46 | 5 | 3 | 8 | 32 | 22 | 54 |
| 2028 | 27 | 20 | 47 | 5 | 3 | 8 | 33 | 22 | 55 |
| 2029 | 28 | 20 | 48 | 5 | 3 | 8 | 33 | 23 | 56 |
| 2030 | 28 | 20 | 48 | 5 | 3 | 8 | 34 | 23 | 57 |
| 2031 | 28 | 20 | 48 | 5 | 3 | 8 | 34 | 23 | 57 |
| 2032 | 28 | 20 | 48 | 5 | 3 | 8 | 33 | 23 | 56 |
| 2033 | 28 | 20 | 47 | 5 | 3 | 8 | 33 | 23 | 56 |
| 2034 | 27 | 19 | 47 | 5 | 3 | 8 | 33 | 22 | 55 |
| 2035 | 27 | 19 | 46 | 5 | 3 | 8 | 32 | 22 | 54 |
| 2040 | 26 | 18 | 44 | 5 | 3 | 8 | 31 | 21 | 52 |
| 2045 | 26 | 18 | 44 | 5 | 3 | 8 | 31 | 20 | 51 |
| 2050 | 28 | 19 | 46 | 5 | 3 | 8 | 33 | 21 | 54 |
| 2055 | 28 | 20 | 48 | 5 | 3 | 8 | 34 | 23 | 57 |
| 2060 | 31 | 21 | 52 | 6 | 3 | 9 | 37 | 24 | 61 |
Table 56 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 57 Footnote 1 | Partial | Full | TotalTable 57 Footnote 1 | Partial | Full | TotalTable 57 Footnote 1 | |
| 2025 | 112 | 182 | 294 | 21 | 25 | 46 | 133 | 207 | 340 |
| 2026 | 117 | 191 | 309 | 22 | 26 | 48 | 140 | 217 | 356 |
| 2027 | 123 | 200 | 323 | 23 | 27 | 50 | 146 | 227 | 373 |
| 2028 | 129 | 209 | 338 | 24 | 28 | 52 | 153 | 236 | 389 |
| 2029 | 135 | 217 | 351 | 25 | 29 | 54 | 160 | 245 | 405 |
| 2030 | 139 | 224 | 363 | 26 | 29 | 55 | 164 | 253 | 417 |
| 2031 | 142 | 229 | 370 | 26 | 30 | 56 | 168 | 259 | 426 |
| 2032 | 143 | 232 | 375 | 26 | 30 | 56 | 169 | 262 | 431 |
| 2033 | 144 | 234 | 378 | 26 | 30 | 56 | 170 | 264 | 434 |
| 2034 | 144 | 235 | 379 | 26 | 30 | 56 | 170 | 265 | 435 |
| 2035 | 145 | 236 | 381 | 26 | 30 | 56 | 171 | 266 | 438 |
| 2040 | 152 | 247 | 398 | 28 | 31 | 59 | 179 | 278 | 457 |
| 2045 | 165 | 269 | 434 | 30 | 34 | 64 | 195 | 303 | 498 |
| 2050 | 189 | 312 | 501 | 35 | 39 | 74 | 224 | 351 | 575 |
| 2055 | 216 | 366 | 582 | 39 | 46 | 84 | 255 | 411 | 666 |
| 2060 | 249 | 435 | 683 | 44 | 53 | 97 | 292 | 488 | 780 |
Table 57 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 58 Footnote 1 | Partial | Full | TotalTable 58 Footnote 1 | Partial | Full | TotalTable 58 Footnote 1 | |
| 2025 | 10 | 1 | 10 | 56 | 3 | 59 | 66 | 4 | 70 |
| 2026 | 10 | 1 | 10 | 57 | 3 | 60 | 67 | 4 | 70 |
| 2027 | 10 | 1 | 11 | 57 | 3 | 60 | 67 | 4 | 71 |
| 2028 | 10 | 1 | 11 | 57 | 3 | 60 | 67 | 4 | 71 |
| 2029 | 10 | 1 | 11 | 57 | 3 | 60 | 68 | 3 | 71 |
| 2030 | 10 | no data- | 11 | 57 | 3 | 60 | 67 | 3 | 71 |
| 2031 | 10 | no data- | 10 | 57 | 3 | 59 | 66 | 3 | 70 |
| 2032 | 10 | no data- | 10 | 56 | 3 | 59 | 66 | 3 | 69 |
| 2033 | 10 | no data- | 10 | 55 | 3 | 58 | 64 | 3 | 68 |
| 2034 | 9 | no data- | 10 | 54 | 3 | 57 | 63 | 3 | 66 |
| 2035 | 9 | no data- | 10 | 53 | 3 | 56 | 62 | 3 | 65 |
| 2040 | 9 | no data- | 9 | 50 | 2 | 52 | 58 | 3 | 61 |
| 2045 | 9 | no data- | 9 | 48 | 2 | 51 | 57 | 3 | 60 |
| 2050 | 9 | no data- | 10 | 50 | 2 | 53 | 60 | 3 | 63 |
| 2055 | 9 | 1 | 10 | 52 | 3 | 54 | 61 | 3 | 64 |
| 2060 | 10 | 1 | 10 | 55 | 3 | 57 | 64 | 3 | 67 |
Table 58 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 59 Footnote 1 | Partial | Full | TotalTable 59 Footnote 1 | Partial | Full | TotalTable 59 Footnote 1 | |
| 2025 | 74 | 10 | 83 | 456 | 58 | 514 | 530 | 67 | 597 |
| 2026 | 75 | 10 | 85 | 467 | 58 | 526 | 543 | 68 | 611 |
| 2027 | 77 | 10 | 87 | 477 | 59 | 536 | 554 | 69 | 623 |
| 2028 | 78 | 10 | 87 | 485 | 59 | 544 | 563 | 69 | 632 |
| 2029 | 78 | 10 | 88 | 492 | 59 | 551 | 570 | 68 | 639 |
| 2030 | 78 | 10 | 88 | 497 | 58 | 554 | 575 | 68 | 643 |
| 2031 | 78 | 10 | 88 | 498 | 58 | 555 | 576 | 68 | 643 |
| 2032 | 78 | 10 | 88 | 497 | 58 | 555 | 575 | 68 | 642 |
| 2033 | 77 | 10 | 87 | 494 | 58 | 552 | 571 | 68 | 639 |
| 2034 | 76 | 10 | 86 | 489 | 58 | 548 | 566 | 68 | 634 |
| 2035 | 76 | 10 | 86 | 486 | 58 | 544 | 561 | 68 | 629 |
| 2040 | 75 | 11 | 86 | 479 | 59 | 538 | 554 | 70 | 624 |
| 2045 | 79 | 12 | 91 | 497 | 63 | 561 | 576 | 76 | 652 |
| 2050 | 86 | 14 | 100 | 541 | 69 | 610 | 627 | 83 | 710 |
| 2055 | 95 | 17 | 111 | 598 | 78 | 675 | 692 | 94 | 787 |
| 2060 | 102 | 18 | 120 | 659 | 84 | 743 | 761 | 102 | 864 |
Table 59 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 60 Footnote 1 | Partial | Full | TotalTable 60 Footnote 1 | Partial | Full | TotalTable 60 Footnote 1 | |
| 2025 | 8 | no data- | 8 | 42 | 2 | 44 | 50 | 2 | 52 |
| 2026 | 8 | no data- | 8 | 43 | 2 | 46 | 51 | 2 | 53 |
| 2027 | 8 | no data- | 8 | 44 | 2 | 46 | 52 | 2 | 54 |
| 2028 | 8 | no data- | 8 | 45 | 2 | 47 | 53 | 2 | 55 |
| 2029 | 8 | no data- | 8 | 46 | 2 | 48 | 54 | 2 | 56 |
| 2030 | 8 | no data- | 8 | 47 | 2 | 48 | 55 | 2 | 57 |
| 2031 | 8 | no data- | 8 | 47 | 2 | 48 | 55 | 2 | 57 |
| 2032 | 8 | no data- | 8 | 47 | 2 | 48 | 55 | 2 | 56 |
| 2033 | 8 | no data- | 8 | 46 | 2 | 47 | 54 | 2 | 56 |
| 2034 | 8 | no data- | 8 | 45 | 2 | 47 | 53 | 2 | 55 |
| 2035 | 8 | no data- | 8 | 45 | 2 | 46 | 52 | 2 | 54 |
| 2040 | 7 | no data- | 8 | 43 | 2 | 44 | 50 | 2 | 52 |
| 2045 | 7 | no data- | 8 | 42 | 2 | 44 | 50 | 2 | 51 |
| 2050 | 8 | no data- | 8 | 45 | 2 | 46 | 53 | 2 | 54 |
| 2055 | 8 | no data- | 8 | 47 | 2 | 48 | 55 | 2 | 57 |
| 2060 | 9 | no data- | 9 | 51 | 2 | 52 | 59 | 2 | 61 |
Table 60 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 61 Footnote 1 | Partial | Full | TotalTable 61 Footnote 1 | Partial | Full | TotalTable 61 Footnote 1 | |
| 2025 | 47 | 4 | 51 | 305 | 21 | 326 | 353 | 25 | 377 |
| 2026 | 49 | 4 | 53 | 320 | 22 | 342 | 369 | 25 | 395 |
| 2027 | 51 | 4 | 55 | 335 | 22 | 357 | 386 | 26 | 412 |
| 2028 | 53 | 4 | 57 | 349 | 23 | 372 | 402 | 27 | 428 |
| 2029 | 54 | 4 | 58 | 363 | 23 | 386 | 417 | 27 | 444 |
| 2030 | 56 | 4 | 60 | 373 | 24 | 397 | 429 | 28 | 457 |
| 2031 | 56 | 4 | 60 | 379 | 24 | 404 | 435 | 29 | 464 |
| 2032 | 56 | 4 | 60 | 382 | 25 | 407 | 438 | 29 | 467 |
| 2033 | 56 | 4 | 60 | 382 | 25 | 407 | 437 | 29 | 467 |
| 2034 | 56 | 4 | 60 | 381 | 26 | 406 | 436 | 30 | 466 |
| 2035 | 55 | 4 | 60 | 380 | 26 | 406 | 436 | 30 | 466 |
| 2040 | 56 | 4 | 60 | 385 | 27 | 412 | 440 | 32 | 472 |
| 2045 | 59 | 5 | 64 | 407 | 30 | 437 | 466 | 35 | 500 |
| 2050 | 65 | 6 | 71 | 456 | 34 | 490 | 522 | 39 | 561 |
| 2055 | 73 | 6 | 79 | 514 | 40 | 554 | 587 | 46 | 633 |
| 2060 | 82 | 7 | 89 | 584 | 47 | 631 | 666 | 54 | 720 |
Table 61 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 62 Footnote 1 | Partial | Full | TotalTable 62 Footnote 1 | Partial | Full | TotalTable 62 Footnote 1 | |
| 2025 | 2 | no data- | 3 | 14 | 2 | 16 | 16 | 2 | 18 |
| 2026 | 2 | no data- | 3 | 14 | 2 | 15 | 16 | 2 | 18 |
| 2027 | 2 | no data- | 3 | 13 | 2 | 14 | 15 | 2 | 17 |
| 2028 | 2 | no data- | 2 | 12 | 2 | 14 | 14 | 2 | 16 |
| 2029 | 2 | no data- | 2 | 11 | 1 | 13 | 13 | 2 | 15 |
| 2030 | 2 | no data- | 2 | 11 | 1 | 12 | 12 | 2 | 14 |
| 2031 | 2 | no data- | 2 | 10 | 1 | 11 | 12 | 2 | 13 |
| 2032 | 2 | no data- | 2 | 9 | 1 | 11 | 11 | 2 | 13 |
| 2033 | 2 | no data- | 2 | 9 | 1 | 10 | 11 | 1 | 12 |
| 2034 | 2 | no data- | 2 | 9 | 1 | 10 | 10 | 1 | 12 |
| 2035 | 2 | no data- | 2 | 8 | 1 | 9 | 10 | 1 | 11 |
| 2040 | 1 | no data- | 2 | 7 | 1 | 8 | 9 | 1 | 10 |
| 2045 | 1 | no data- | 2 | 6 | 1 | 7 | 8 | 1 | 9 |
| 2050 | 1 | no data- | 2 | 6 | 1 | 7 | 7 | 1 | 8 |
| 2055 | 1 | no data- | 2 | 5 | 1 | 6 | 6 | 1 | 7 |
| 2060 | 1 | no data- | 1 | 4 | 1 | 5 | 5 | 1 | 6 |
Table 62 Footnotes
| |||||||||
| Year | Males Level of benefit: | Females Level of benefit: | Both sexes Level of benefit: | ||||||
|---|---|---|---|---|---|---|---|---|---|
| Partial | Full | TotalTable 63 Footnote 1 | Partial | Full | TotalTable 63 Footnote 1 | Partial | Full | TotalTable 63 Footnote 1 | |
| 2025 | 26 | 6 | 32 | 151 | 37 | 188 | 177 | 43 | 220 |
| 2026 | 26 | 6 | 32 | 147 | 37 | 184 | 173 | 43 | 216 |
| 2027 | 26 | 6 | 32 | 142 | 37 | 179 | 168 | 43 | 211 |
| 2028 | 25 | 6 | 31 | 136 | 36 | 172 | 161 | 42 | 203 |
| 2029 | 24 | 6 | 30 | 130 | 36 | 165 | 153 | 41 | 195 |
| 2030 | 23 | 6 | 28 | 123 | 34 | 157 | 146 | 40 | 186 |
| 2031 | 22 | 6 | 28 | 118 | 33 | 152 | 140 | 39 | 179 |
| 2032 | 22 | 6 | 27 | 115 | 33 | 148 | 137 | 39 | 176 |
| 2033 | 21 | 6 | 27 | 112 | 33 | 145 | 133 | 39 | 172 |
| 2034 | 21 | 6 | 27 | 109 | 33 | 141 | 130 | 38 | 168 |
| 2035 | 20 | 6 | 26 | 105 | 32 | 137 | 126 | 38 | 164 |
| 2040 | 19 | 7 | 26 | 94 | 32 | 126 | 113 | 38 | 152 |
| 2045 | 20 | 8 | 28 | 91 | 34 | 124 | 111 | 41 | 152 |
| 2050 | 20 | 9 | 29 | 85 | 35 | 120 | 105 | 44 | 149 |
| 2055 | 22 | 10 | 32 | 84 | 38 | 122 | 106 | 48 | 154 |
| 2060 | 20 | 11 | 31 | 75 | 37 | 113 | 96 | 48 | 144 |
Table 63 Footnotes
| |||||||||
Footnotes
- Footnote 1
For 2024, the net migration rate of 2.88% is the net result of: 1.12% immigration rate, −0.12% net emigration rate, and +1.88% net changes in NPR.
- Footnote 2
The 2019 life expectancies under the 18th OAS Program Actuarial Report and the 19th OAS Program Actuarial Report differ, as Statistics Canada revised the values in their Life Tables dataset used for the current report relative to the one used in the previous report.
- Footnote 3
- Footnote 4
As of January 2025
- Footnote 5
Kotz, M., Levermann, A. & Wenz, L.: The economic commitment of climate change. Nature 628, 551–557 (2024).
- Footnote 6
Retraction Note: The economic commitment of climate change | Nature